 Polypropylene Rigid Food Containers Market
: Global Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 198

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Polypropylene Rigid Food Containers Market
Sakshi Gurunule
Research Associate

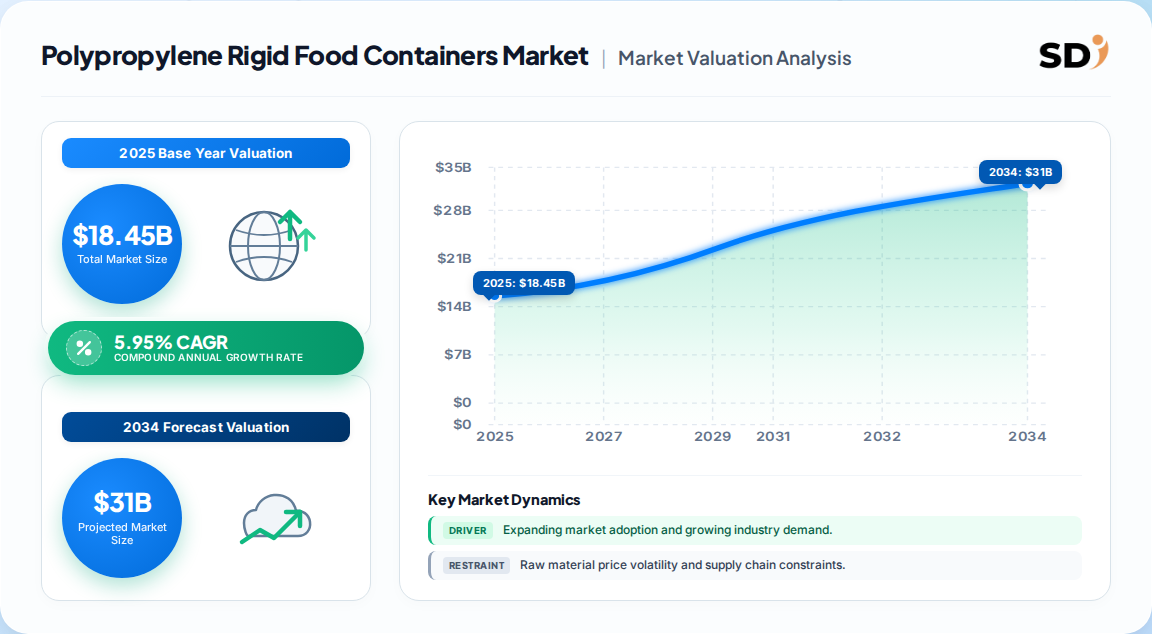
| Year | Market Size |
|---|---|
| 2025 | 18.45 B |
| 2026 | 19.55 B |
| 2027 | 20.71 B |
| 2028 | 21.94 B |
| 2029 | 23.25 B |
| 2030 | 24.63 B |
| 2031 | 26.10 B |

The Polypropylene Rigid Food Containers Market covers durable, thermoformed or injection-moulded PP packaging used to store, transport, reheat and serve food — including tubs, jars, trays, clamshells, takeaway containers, cups and lids — sold to retail packaged-food brands, foodservice operators and bulk food processors.
This report sizes and forecasts global PP rigid food containers across four product families (tubs and jars, trays and clamshells, takeaway/foodservice containers, cups and lids) and five end-use channels (retail packaged food, foodservice and restaurants, industrial/bulk food processors, convenience and on-the-go, and others). Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa.
This analysis does not cover flexible packaging, polyethylene terephthalate (PET) bottles, paperboard or moulded-fibre containers, metal cans, glass jars, or non-food PP packaging such as cosmetic and industrial containers.
The most defensible baseline is 18.45 Billion in 2025, growing to 32.9 Billion by 2035 at a 5.95% CAGR — a direct, product-specific estimate rather than a top-down residual from broader rigid food packaging.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 18.45 Billion | 2025 | 2035 | 5.95% | PP rigid food containers: tubs, jars, trays, clamshells, takeaway containers, cups and lids | One published vendor-focused analysis |
| 82.18 Billion | 2025 | 2035 | 5.38% | All-material rigid food packaging (plastic, metal, glass, paperboard) | A competing analysis |
| 241.3 Billion | 2025 | 2033 | 4.9% | Broad rigid food packaging incl. bottles, cans, paperboard cartons | A separate published estimate |
| 380.0 Billion | 2026 | 2036 | 5.2% | Total food packaging, rigid plus flexible plus secondary | A third published estimate |
The wide spread across sources reflects definitional scope, not disagreement on direction. Our analysis suggests the 18.45 Billion figure is the most defensible for buyers because it isolates the PP rigid container category; broader 82–380 billion figures embed metal, glass, paperboard and flexible formats that dilute PP-specific procurement and investment signals. The implied 5.95% CAGR sits modestly above the 4.9–5.4% range for all-material rigid packaging, consistent with PP taking share from PS and PVC foam on recyclability and microwave performance.
Segmentation follows two non-geographic axes — product format and end-use channel — with product format the primary lens for capacity planning and end-use the primary lens for account targeting.
| Parent | Children |
|---|---|
| By Product | Tubs & Jars; Trays & Clamshells; Takeaway/Foodservice Containers; Cups & Lids |
| By End Use | Retail Packaged Food; Foodservice & Restaurants; Industrial/Bulk Food Processors; Convenience & On-the-go; Others |
Trays and clamshells anchor the fresh-protein, bakery and ready-meal trade, while foodservice containers absorb the fastest volume growth from delivery and takeaway. Our analysis suggests cups and lids deserve disproportionate attention: single-serve dairy and dessert formats carry higher margins per gram of resin than commodity takeaway bases.
North America generates the largest demand, underpinned by an established foodservice sector, high packaged-food consumption and organised retail; Asia-Pacific is the fastest-growing region, driven by urbanisation, delivery expansion and food-retail formalisation in China and India.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.3% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
| Region | Estimated share (2025) |
|---|---|
| North America | 34% |
| Europe | 24% |
| Asia-Pacific | 30% |
| South America | 6% |
| Middle East & Africa | 6% |
Note that Mexico appears in both North America and Latin America in published regional conventions; we allocate it to North America for demand continuity with US supply chains. The 30% Asia-Pacific share understates the region's strategic weight — its growth premium implies roughly 40% of incremental 2026–2035 revenue, making it the priority region for capacity investment.
Demand is being pulled by convenience food, food delivery and microwave-safe requirements; it is being pulled back by virgin-resin cost volatility, single-use plastic regulation and food-contact recycled-resin bottlenecks.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Convenience, ready-to-eat and delivery meals | Driver | Strong | Higher container turns per meal occasion; takeaway and cloud-kitchen volumes |
| Microwave-safe, lightweight, leak-proof performance | Driver | Strong | PP displaces PS foam and weaker formats in hot-fill and reheat applications |
| Recyclability and mono-material design | Driver | Moderate | Retailer recyclability mandates favour PP over multi-material laminates |
| Recycled PP food-contact approval constraints | Restraint | Moderate | Limited approved PCR supply forces virgin/co-extruded inner layers |
| Virgin resin and energy price volatility | Restraint | Strong | Margin compression across thin-wall converters |
| Single-use plastics regulation | Restraint | Moderate | Bans and EPR fees raise compliance cost in Europe and parts of Asia-Pacific |
The balance favours growth: convenience and delivery demand is structural, while regulatory pressure is manageable through mono-material design and recycled content. Our analysis suggests the binding constraint through 2030 is not demand but approved food-contact recycled PP supply — brands are committing to recycled content faster than decontamination capacity is being authorised.
The market is moderately consolidated, with Tier-1 players holding roughly half of revenue and competing on thermoforming scale, food-contact compliance and multinational account coverage.
| Company | HQ / base | Strategic position |
|---|---|---|
| Berry Global Group | USA | Broad rigid and flexible portfolio; large foodservice and retail footprint |
| Amcor plc | Switzerland / Australia | Global scale; sustainability-led product platforms |
| Huhtamaki Oyj | Finland | Strong foodservice and fibre-plus-plastic hybrid capability |
| Pactiv Evergreen | USA | Foodservice and retail rigid containers; acquired by Novolex in 2024 |
| ALPLA Group | Austria | Injection-moulded and thin-wall PP capability; global recycling investment |
| Sonoco Products | USA | Consumer and industrial rigid; European metal integration via Eviosys |
| Silgan Holdings | USA | Closures and rigid containers; high-barrier focus |
| Plastipak Holdings | USA | Bottles and rigid formats; PCR integration |
| Winpak | Canada | Barrier rigid and lidding; North American food processors |
| Graham Packaging | USA | Blow-moulded and rigid formats; custom design |
| Cosmo Films | India | Films-led but expanding rigid and specialty packaging |
Differentiation rests on tooling amortisation across high-volume SKUs, food-contact regulatory dossiers per jurisdiction, and closed-loop recycled PP access. Our analysis suggests the 2024 consolidation wave — Novolex/Pactiv Evergreen, Sonoco/Eviosys — signals that scale in recycling and regulatory capability, not thermoforming capacity, is becoming the decisive moat.
Selection should weigh five mission-critical criteria: food-contact compliance in each destination market, microwave and hot-fill temperature performance, leak-proofness under delivery conditions, recycled-content availability, and tooling changeover economics.
Procurement risk concentrates in resin pass-through clauses and recycled PP availability. Buyers signing multi-year agreements should index resin, specify approved-PCR grades explicitly, and lock decontamination-validated supply before retail commitments are made. Switching costs are moderate for standard tubs and trays but high for custom-tooled clamshells and printed lids, where changeover can take 8–16 weeks.
Regulatory compliance is fragmented: US FDA food-contact listings, EU plastics recycling process assessments, and national single-use plastic rules each impose different evidence requirements. Operators should treat compliance documentation as a vendor-qualification gate rather than an after-sales formality.
The balance of evidence favours sustained mid-single-digit growth with share migration toward PP, but the growth is unevenly distributed: format mix and geography matter more than headline CAGR. The strongest counter-argument is that regulatory restrictions on single-use plastics could compress foodservice container volumes faster than retail formats grow — a risk our analysis views as real but largely offset by PP's recyclability relative to PS foam and by the shift from foam to PP in banned jurisdictions.
Our judgment is that the market's centre of gravity is moving from commodity takeaway bases to specification-heavy, sustainability-compliant formats: high-clarity cups, microwave-safe sealed trays and PCR-blended tubs. Vendors that treat PP as a commodity resin business will face margin compression; those that invest in food-contact recycled supply and compliance dossiers will capture premium pricing.
Actionable Strategy
What would change our view: evidence of accelerated EU or Asia-Pacific single-use bans covering PP foodservice formats, or a failure of food-contact recycled PP approvals to scale by 2028, would lower the growth trajectory toward the 4.9% all-material rigid baseline.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.95% from 2020-2034 |
| Segmentation |
|
The global market was valued at approximately 18.45 Billion in 2025 and is projected to reach 32.9 Billion by 2035, expanding at a 5.95% CAGR over the 2026–2035 forecast period.
Asia-Pacific is the fastest-growing region, driven by urbanisation, food delivery expansion and organised retail growth in China, India, Japan and South Korea. North America remains the largest demand region.
The market is segmented into tubs and jars, trays and clamshells, takeaway/foodservice containers, and cups and lids. Trays and clamshells lead volume, while cups and tubs grow fastest.
Berry Global, Amcor, Huhtamaki, Pactiv Evergreen, ALPLA, Sonoco, Silgan, Plastipak, Winpak and Graham Packaging lead the market, with Tier-1 players holding roughly half of revenue.
Polypropylene offers microwave safety, lightweight durability, leak resistance and recyclability. It maintains food-contact compliance under US FDA listings and outperforms polystyrene foam on sustainability and heat performance.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program is built on a 70/30 primary-to-secondary split, with 70% of analytical effort devoted to direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain: polypropylene resin suppliers, specialised thermoforming and injection-moulding producers, contract manufacturers serving QSR and retail brands, and global distributors of foodservice packaging. Interviewees were drawn from decision-maker roles including VP of Sourcing, Heads of R&D and Packaging Development, Technical Directors, and Commercial Operations Leads, ensuring that both technical and commercial perspectives inform our sizing.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VPs of Sourcing & Procurement Directors | 35% |
| Heads of R&D & Packaging Development | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| PP Resin & Material Suppliers | 30% |
| Thermoforming & Injection-Moulding Producers | 40% |
| Contract Manufacturers & Brand Owners | 18% |
| Global Distributors & Traders | 12% |
Secondary validation draws on official multilateral trade statistics from UN Comtrade (HS Chapter 39 and 3924 trade flows), WTO tariff and trade data, US ITC import statistics, and Eurostat trade and production indices. Corporate annual filings (10-K, SEC filings, investor presentations) from listed packaging producers inform capacity and revenue triangulation. Patent databases and technical standards published by recognised industry and standards bodies are used to validate technology trajectories.
We run simultaneous top-down and bottom-up models. The top-down model allocates rigid food packaging revenue to PP containers using material and format shares from trade and industry data. The bottom-up model aggregates manufacturer capacity, average selling prices by format, and end-use consumption volumes across retail, foodservice and bulk channels. Divergence between the two is reconciled through weighted averaging and scenario testing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |