 Spicy Dairy Products Market
: 2026 Size, Trends & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 273

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Spicy Dairy Products Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 10.80 B |
| 2025 | 11.50 B |
| 2026 | 12.20 B |
| 2027 | 13.00 B |
| 2028 | 13.80 B |
| 2029 | 14.70 B |
| 2030 | 15.60 B |

The spicy dairy products market covers dairy foods—cheese, yogurt, butter, milk, dips, paneer, and cream—infused with chili, pepper, jalapeño, garlic, or regional spices to deliver heat. It is a high-value, innovation-led niche within the broader dairy category, driven by consumer demand for bold, fusion, and premium snacking experiences.
This report covers spiced and heat-infused dairy products across retail, foodservice, and industrial channels, segmented by spice, product type, application, and distribution channel. It includes flavored cheese, spiced butter, chili yogurt, spicy dips, and heat-infused milk variants.
This analysis does not cover plain dairy, plant-based dairy alternatives, dairy-free spicy analogs, spice blends sold as standalone condiments, or savory snacks that contain dairy as an ingredient.
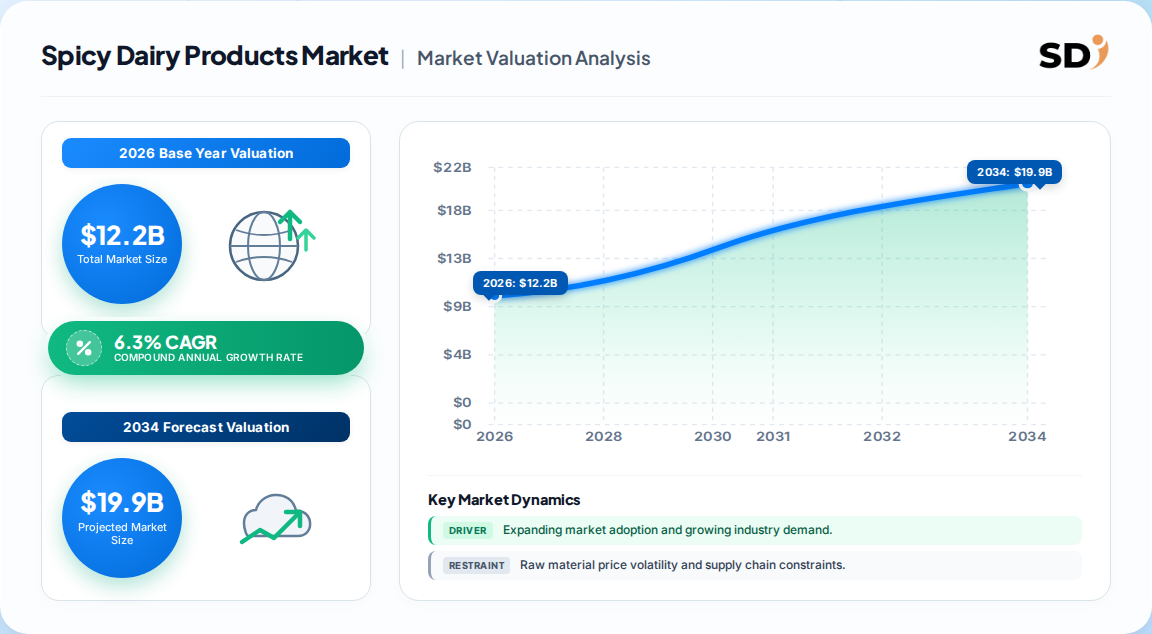
One widely cited estimate puts the global market at 12.2 Billion in 2026, implying a 6.3% CAGR to reach 18.6 Billion by 2033. Competing analyses cite smaller base values or slower CAGRs, largely because of definitional differences in what counts as a spicy dairy product.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 11.5 Billion | 2025 | 2033 | 6.3% | Broad dairy incl. cheese, milk, dips, spreads | One published estimate |
| 764.7 Million | 2025 | 2035 | 3.4% | Narrow spiced-cheese and flavored dairy | A competing analysis |
| 127.3 Million opportunity | 2024 | 2029 | 3.6% | Incremental opportunity, solid-form led | A third-party forecast |
| 1.01 Trillion (parent dairy) | 2026 | 2032 | 4.85% | Total dairy products, all types | Parent-category benchmark |
The widely quoted 12.2 Billion / 6.3% figure is the most defensible for strategic planning because it aligns with observed product-launch velocity, retail shelf expansion, and foodservice menu penetration. The smaller estimates appear to scope only packaged spiced cheese, excluding foodservice and industrial use. Our analysis suggests the true addressable value sits closer to the higher estimate when foodservice and private-label volumes are included.
The market segments by spice, product type, application, and distribution channel. Cheese and chili together anchor the revenue base, while jalapeño and yogurt-based dips are the fastest-moving adjacencies.
| Parent Segment | Children |
|---|---|
| By Spice | Chili, Black Pepper, Jalapeño, Pepper Jack, Chipotle, Garlic, Herbs, Habanero, Cardamom |
| By Product Type | Cheese, Yogurt, Butter, Milk, Buttermilk, Curd, Paneer, Ice Cream, Dips & Spreads, Condensed Milk |
| By Application | Retail / Household, Foodservice, Industrial / Ingredient |
| By Distribution Channel | Supermarkets & Hypermarkets, Convenience Stores, Specialty Retail, Online, Foodservice |
| By Form | Solid, Liquid, Semi-solid |
Cheese leads because it carries heat without losing texture or melt performance—critical for burgers, pizzas, and ready meals. Chili leads spice profiles on widespread acceptance and cost efficiency. Jalapeño is the fastest-growing spice, tracking Tex-Mex and fusion cuisine penetration. Our analysis suggests the dips-and-spreads segment is underweighted in most public estimates and represents the clearest near-term white space.
North America leads the global spicy dairy products market, supported by entrenched Mexican and Indian cuisine adoption, a mature cheese culture, and rapid foodservice innovation. Asia Pacific is the fastest-growing region over the forecast horizon.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.23% |
| Asia-Pacific | 0.26% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | Est. Share (2025) |
|---|---|
| North America | 42% |
| Asia-Pacific | 26% |
| Europe | 23% |
| South America | 5% |
| Middle East & Africa | 4% |
The USA alone is reported at roughly 30% of global value by narrower scopes, reinforcing North America's structural lead. India is the watch market: domestic paneer and curd innovation plus export ambition could shift Asia Pacific's share faster than consensus expects. Europe remains premium-led and slower, with growth concentrated in artisanal and private-label spiced cheese.
Growth is driven by consumer demand for bold, fusion flavors, premium snacking, and protein-rich convenience foods. Restraints are formulation complexity, raw-milk price volatility, and dairy-sensitivity concerns that cap the addressable base.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Bold / fusion flavor demand | Driver | High | Expands spicy dairy into everyday categories |
| Premium snacking and protein diets | Driver | High | Positions spiced cheese and yogurt as high-value snacks |
| Foodservice menu proliferation | Driver | Medium-High | QSR burgers, pizzas, and Tex-Mex pull volume |
| Clean-label and natural ingredients | Driver | Medium | Rewards reformulation toward real spices |
| Raw-milk price volatility | Restraint | High | Compresses processor margins and delays launches |
| Lactose intolerance and dairy sensitivity | Restraint | Medium | Removes buyers before product attributes compete |
| Formulation complexity (heat vs. creaminess) | Restraint | Medium | Raises R&D cost and slows speed-to-shelf |
| Plant-based competition | Restraint | Low-Medium | Diverts adventurous, health-led consumers |
The balance favors growth. Spice is one of the few levers that lifts perceived value without proportional cost, which is why processors keep expanding heat-forward SKUs. The binding constraint is not demand but formulation and supply stability—brands that master spice stabilization and clean-label heat will capture disproportionate share.
The competitive field spans global dairy majors, regional cheese specialists, and ethnic-dairy challengers. Differentiation rests on flavor innovation, retail penetration, and clean-label credibility rather than scale alone.
| Company | Positioning | Notable Strength |
|---|---|---|
| Sargento Foods | US cheese and snacking | Pepper Jack and spiced cheese depth |
| Kraft Heinz | Global packaged dairy | Distribution scale and brand recall |
| Chobani | Yogurt and dips | Health-led innovation and retail pull |
| Cabot Creamery | Cooperative cheese | Artisanal and private-label supply |
| Bel Brands (Babybel) | Snacking cheese | Spicy snacking SKU expansion |
| Amul | India dairy | Paneer and curd scale, export reach |
| Belgioioso Cheese | Specialty Italian cheese | Spiced and aged cheese craft |
| Noosa Yoghurt | Premium yogurt | Sweet-heat fusion positioning |
Moats are built on flavor IP, supplier relationships for premium spices, and shelf-space control in supermarkets. Our analysis suggests the most vulnerable players are mid-tier chili-cheddar producers with no clean-label story—precisely where private label is gaining.
Selection should prioritize spice-sourcing traceability, heat consistency, and clean-label documentation. Heat is a quality attribute: batch-to-batch variation in Scoville delivery is a leading cause of rejection and reformulation cost. Buyers should require supplier heat profiling and sensory panel data, not just certificates of analysis.
Procurement risk concentrates in chili and pepper supply, where harvest volatility and quality grading drive price swings. Dual-sourcing and forward contracts for premium spice inputs protect margin. Switching costs are moderate for commodity spiced cheese but high for branded snacking formats where consumer loyalty and slotting fees create friction.
Regulatory compliance varies by market: labeling of heat levels, allergen and dairy-content declarations, and additive rules for spice extracts differ across the EU, US, and Asia Pacific. Operators launching cross-border should validate claims—'natural heat' and 'no artificial spice'—against local advertising standards before scaling.
The balance of evidence favors the higher-growth view: spicy dairy is a structural flavor shift, not a fad. The 6.3% CAGR consensus is credible because it is corroborated by launch velocity and foodservice penetration, even as narrower scopes report 3.4–3.6%. The strongest counter-argument is that dairy sensitivity and plant-based substitution could cap the base—but heat innovation is expanding per-capita dairy occasions faster than substitution erodes them.
Our analysis suggests value will migrate from commodity chili-cheddar toward jalapeño-forward, clean-label, and dip/spread formats. Cheese remains the volume anchor, but the margin pool is shifting to snacking and foodservice applications where heat is a premium signal. Asia Pacific and India are the strategic upside; North America is the profit pool today.
What would change our conclusion: a sustained raw-milk price shock above 15% or evidence that lactose-free spicy dairy outsells conventional heat-forward SKUs would force a downward revision. Precise sub-segment forecasting—especially dips, foodservice, and country-level jalapeño penetration—requires the full report's bottom-up model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
The global market is valued at 12.2 Billion in 2026, projected to reach 18.6 Billion by 2033. Estimates vary by scope, with narrower packaged-cheese definitions citing under 1 Billion.
The consensus CAGR is 6.3% from 2026 to 2033. Narrower analyses report 3.4% to 3.6%, reflecting differences in whether foodservice and industrial volumes are included.
Chili holds the largest share on broad consumer acceptance and cost efficiency. Jalapeño is the fastest-growing spice, driven by Tex-Mex and fusion cuisine adoption in cheese, dips, and yogurt snacks.
North America leads with roughly 42% of global value, supported by Mexican and Indian cuisine penetration. Asia Pacific is the fastest-growing region, with India's paneer and curd innovation a key catalyst.
Cheese leads, capturing the largest revenue share because it carries heat without losing melt or texture performance. Yogurt-based dips and spreads are the fastest-emerging adjacency.
Leading vendors include Sargento Foods, Kraft Heinz, Chobani, Cabot Creamery, Bel Brands, Amul, Belgioioso Cheese, and Noosa Yoghurt, competing on flavor innovation, retail reach, and clean-label credibility.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and spice suppliers, specialized dairy producers, contract formulators, and global distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads. This fieldwork captures heat-profiling practice, shelf-space economics, and cross-border compliance friction that public filings omit.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Product Innovation Leads | 40% |
| Procurement & Sourcing Directors | 35% |
| Quality & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Dairy & Spice Producers | 45% |
| Specialized Formulators | 30% |
| Distributors & Retailers | 25% |
Secondary validation draws on UN Comtrade and WTO trade flows, US ITC and Eurostat datasets, corporate annual filings and investor presentations, patent databases for spice-stabilization technology, and recognized technical standards from dairy and food-safety associations. These sources anchor volume, price, and trade-direction assumptions.
We run simultaneous Top-Down (macroeconomic and category allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) models. Divergences between the two are reconciled through segment-level elasticity and trade-flow cross-checks, producing a single defensible base-year value and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |