 Dairy Free Ice Cream Market
 Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 268

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dairy Free Ice Cream Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 1.830 B |
| 2026 | 2.050 B |
| 2027 | 2.290 B |
| 2028 | 2.560 B |
| 2029 | 2.860 B |
| 2030 | 3.200 B |
| 2031 | 3.580 B |

The dairy free ice cream market covers frozen desserts formulated without cow's milk, using plant bases such as coconut, oat, almond, soy or cashew, sold through retail and foodservice channels. It spans tubs, bars, cones and foodservice formats, serving lactose-intolerant, vegan, allergen-avoidant and flexitarian consumers seeking indulgent alternatives.
This analysis covers global retail and off-trade value for plant-based frozen desserts across base type, flavor, packaging format and distribution channel, with forecast to 2031. This analysis does not cover conventional dairy ice cream, frozen yogurt, sorbet-only lines, plant-based milk or cheese, or dairy-free confectionery outside frozen dessert formats.
Estimates converge on a market approaching USD 2 Billion in 2026, but headline figures diverge sharply because publishers define 'dairy-free' against different bases — some count only vegan-certified products, others include lactose-free dairy.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.1 Billion | 2024 | 2030 | 15.3% | Dairy-free ice cream, retail value | One published estimate |
| USD 732 Million | 2025 | 2034 | 4.24% | Vegan-certified ice cream only | A competing analysis |
| USD 2.05 Billion | 2026 | 2031 | 11.83% | Dairy-free ice cream, off-trade, global | Another published analysis |
| USD 2.9 Billion | 2026 | 2036 | 9.8% | Broader plant-based ice cream, all formats | A third published analysis |
The USD 2.05 Billion figure is the most defensible for buyers because it aligns with the mid-single-digit-to-low-teens growth band supported by lactose-intolerance prevalence data and retail freezer expansion. Our analysis suggests the 4.24% vegan-only estimate is the outlier: it captures a narrower certified segment and understates the flexitarian household that actually drives volume. The 15.3% figure likely reflects a smaller base and a shorter horizon.
Segmentation follows base ingredient, flavor, packaging format and distribution channel; base type is the most commercially decisive split because it governs texture, cost and allergen positioning.
| Parent | Children |
|---|---|
| By Source | Coconut milk, Oat milk, Almond milk, Soy milk, Cashew milk, Blends |
| By Flavor | Vanilla, Chocolate, Strawberry, Caramel, Coffee, Fruit, Nut |
| By Packaging | Tubs, Cups, Cones, Bars, Others |
| By Distribution Channel | Supermarkets/Hypermarkets, Convenience stores, Online retail, Foodservice, Others |
Coconut leads on natural fat content and stable scoopability, but single-source bases create technical defects; blended bases now hold a majority of form demand because they combine coconut fat with oat or cashew protein to prevent icy crystallization in commercial freezers.
North America leads with roughly 42–47% of global value, supported by mature plant-based retail infrastructure and high lactose-intolerance awareness; Asia Pacific is the fastest-growing region on alternative-protein investment.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.27% |
| Asia-Pacific | 0.19% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
The divergence matters: North America monetises through premium pricing and freezer visibility, while Asia Pacific grows from a small base aided by expanding cold chains. Our analysis suggests Europe is the swing region — its animal-welfare and sustainability policy environment supports steady conversion, but price premiums over dairy remain the binding constraint on household replenishment.
Growth is structurally underwritten by lactose malabsorption affecting roughly two-thirds of adults worldwide, plus clean-label and allergen-friendly demand; the binding constraint is price premium and cold-chain fragility rather than lack of consumer interest.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Lactose intolerance and dairy allergy prevalence | Driver | High | Medical necessity creates non-discretionary purchase |
| Vegan and flexitarian lifestyle adoption | Driver | High | Widens buyer pool beyond allergy sufferers |
| Texture and taste reformulation gains | Driver | Medium-High | Closes sensory gap versus dairy, enabling trial |
| Premium pricing versus dairy | Restraint | High | Limits repeat purchase in price-sensitive households |
| Cold-chain temperature fluctuation | Restraint | Medium | Causes heat shock and icy texture in transit |
| Regulatory labeling clarity | Driver | Medium | Reduced compliance friction accelerates shelf entry |
The balance favours growth, but with a caveat: demand is proven and supply execution is the bottleneck. This divergence implies margin will accrue to operators who solve logistics and formulation rather than to brands that simply claim 'dairy-free'.
The field is fragmented and low-concentration, with global FMCG majors competing against specialist plant-based brands and regional artisanal producers on formulation credibility and freezer placement.
| Company | Positioning | Core strength |
|---|---|---|
| Unilever PLC | Global mass-premium | Distribution scale and brand trust |
| Danone SA | Global plant-based portfolio | Dairy-alternative R&D depth |
| Oatly Group AB | Specialist oat base | Brand equity and oat texture IP |
| Van Leeuwen Ice Cream | Premium artisanal | Flavor innovation and premium pricing |
| Oregon Ice Cream Company | Private-label and regional | Manufacturing flexibility and cost control |
Moats are thin at brand level and thick at formulation and cold-chain level. Our analysis suggests specialist brands hold differentiation through proprietary base blends, while majors win on shelf space and promotional depth — a structure that favours acquisition or partnership over head-on brand competition.
Selection should prioritise proven melt performance and freezer stability over claims, because texture failure is the single largest cause of delisting. Procurement teams should stress-test suppliers on overrun consistency and heat-shock tolerance across the distribution chain, not just on sample quality.
Switching costs are moderate: reformulation is capital-light but requalification of allergen labeling is not, so buyers should secure multi-year supply terms before committing shelf space. Regulatory exposure centres on allergen declaration and descriptor rules, which now permit plant-based attributes alongside conventional ice cream terms in major markets — reducing launch risk but raising the bar on label accuracy.
The balance of evidence favours the mid-range forecast: roughly 11–12% CAGR to 2031, with the market doubling in value. The strongest counter-argument is that premium pricing collapses as private label enters, compressing value growth well below volume growth — a real risk in North America, where retailer own-brand freezer space is expanding fastest.
Our judgment is that the dairy free ice cream market is transitioning from a health-driven niche to a texture-driven mainstream category. The winners will be operators who treat creaminess and price parity as engineering problems, not marketing claims, and who secure freezer visibility rather than relying on e-commerce discovery alone.
What would change our conclusion: a sustained fall in plant-protein input costs that narrows the dairy price gap below 10%, which would accelerate volume far beyond current forecasts and shift advantage toward scale players.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
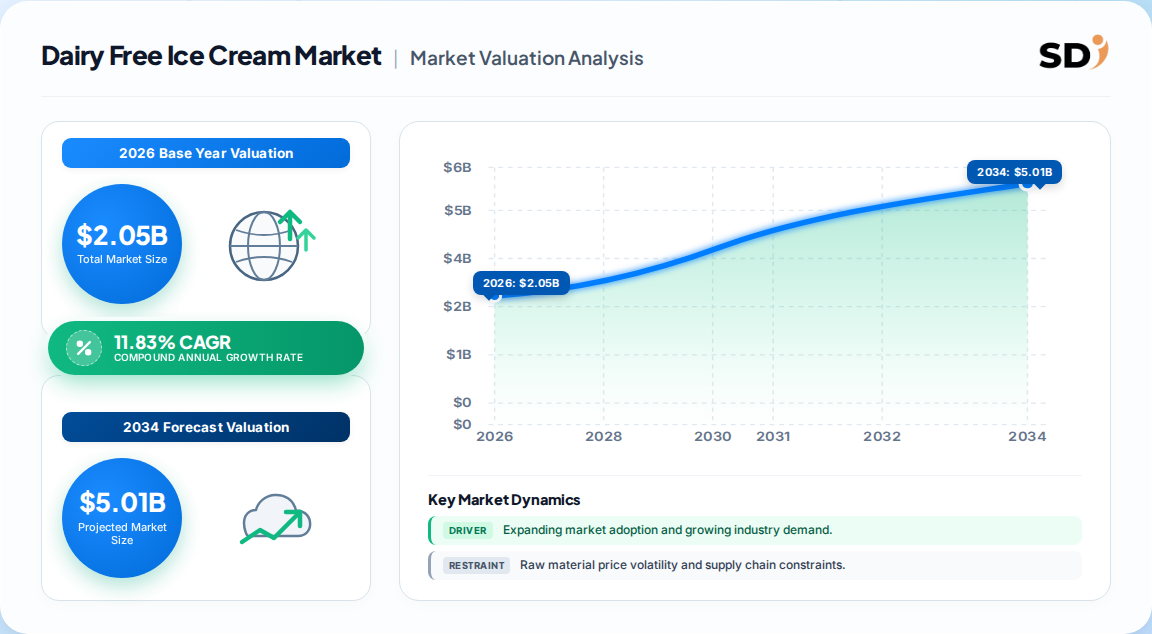
| Growth Rate | CAGR of 11.83% from 2020-2034 |
| Segmentation |
|
It is estimated at USD 2.05 Billion in 2026 and projected to reach USD 3.58 Billion by 2031, representing roughly 11.8% compound annual growth over the five-year forecast period.
Coconut milk leads with approximately 37–38% of value, valued for natural fat content and scoopability. Oat-based formulations are the fastest-growing base, expanding near 16.6% annually as texture technology improves.
North America holds the largest share, around 42–47% of global value, driven by mature plant-based retail and high lactose-intolerance awareness. Asia Pacific is the fastest-growing region, supported by alternative-protein investment.
Premium pricing relative to dairy ice cream and cold-chain temperature instability are the main constraints. Both affect repeat household purchase more than initial trial, which is largely driven by health and allergy needs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritising direct industry fieldwork over published benchmarks.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Product Development Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Plant-Protein Raw Material Suppliers | 30% |
| Specialised Dairy-Free Producers | 35% |
| Contract Formulators & Co-Manufacturers | 20% |
| Cold-Chain Distributors & Retailers | 15% |
In-depth interviews were conducted across the value chain with plant-protein raw material suppliers, specialised dairy-free frozen dessert producers, contract formulators and co-manufacturers, and global cold-chain distributors. Within these organisations we engaged VP-level Sourcing, Heads of R&D and Product Development, Technical Directors, and Commercial Operations Leads to capture both capability and commercial constraints.
Findings were cross-checked against UN Comtrade and Eurostat trade flows for plant proteins and frozen desserts, US ITC tariff schedules, corporate annual filings and investor presentations (10-K and equivalent), patent databases covering plant-based fat and stabiliser systems, and recognised technical standards from food-science and allergen-labelling bodies. No competitor research publications were used as validation inputs.
We run simultaneous top-down allocation from macroeconomic food-category spend and bottom-up modelling of manufacturer capacity, product pricing and end-use consumption. Divergence between the two is reconciled at segment level before forecasts are published.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
All primary fieldwork is anonymised and aggregated; no single respondent exceeds 5% of the modelled base-year value.