 Reconciliation Software Market
: 2025 Size, Share & 2033 Forecast
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 192

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Reconciliation Software Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 2.530 B |
| 2025 | 2.810 B |
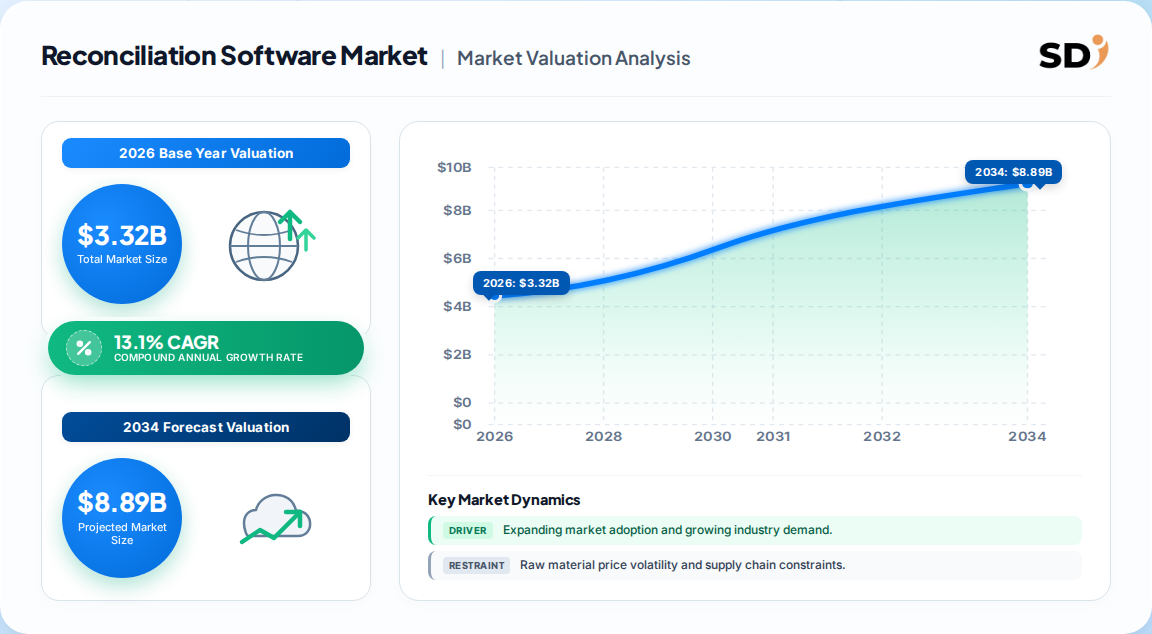
| 2026 | 3.320 B |
| 2027 | 3.760 B |
| 2028 | 4.250 B |
| 2029 | 4.800 B |
| 2030 | 5.430 B |

The reconciliation software market consists of automated platforms that match, verify and explain financial records across ledgers, banks, ERP and payment systems, replacing manual spreadsheets. These tools enforce accuracy, shorten financial close cycles and generate auditable trails for regulatory compliance across banks, fintech, retail, insurance and enterprises.
This report covers global reconciliation software revenue across cloud and on-premise deployment, enterprise and SME buyers, and end-user verticals including BFSI, retail & e-commerce, manufacturing and healthcare. It spans 2024 historical data through 2033 forecasts. This analysis does not cover adjacent markets such as general ledger accounting suites, treasury management systems, expense management or ERP implementation services except where bundled into reconciliation offerings.
Estimates cluster in the low single-digit billions for the mid-2020s, but published figures differ because definitions vary—some include services and implementation, others count only software licenses and subscriptions. The table below compares the leading published benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2.53 Billion | 2024 | 2033 | 13.1% | Software revenue, broad segments | One published estimate |
| 3.32 Billion | 2026 | 2030 | 18.6% | Software plus related services, factory-gate | A competing analysis |
| 8.79 Billion | 2034 | 2034 | 13.7% | Software, deployment/enterprise/end-user | A third published analysis |
| 2.81 Billion | 2025 | 2033 | 15.48% | Cloud & on-premise, banks & enterprise | A fourth published analysis |
Our analysis suggests the 13.1%–13.7% long-horizon CAGR band is the most defensible because it aligns with the underlying driver stack: transaction volume growth, regulatory tightening and cloud migration. The 18.6% figure likely reflects a narrower base year and inclusion of services, which inflates near-term growth. Buyers should anchor budgets on the 13–14% band for multi-year planning and treat higher figures as segment-level upside rather than baseline.
Base-year anchor: 3.32 Billion (2026)
Mid-cycle projection: 7.54 Billion (2033)
Implied CAGR: ~13.1%
Segmentation splits along deployment, enterprise size and end-user vertical, with cloud and BFSI acting as the gravitational centers of demand. The table below summarizes the non-geographic structure.
| Parent Segment | Children | Leading Share |
|---|---|---|
| Deployment Type | Cloud, On-premise | Cloud (~60.2%) |
| Enterprise Size | Large Enterprises, SMEs | Large Enterprises dominant |
| End User / Industry | BFSI, Retail & E-commerce, Manufacturing, Healthcare, Others | BFSI (~47.2%) |
Cloud dominance reflects lower upfront cost, remote accessibility and seamless updates; on-premise retains a durable niche in banking, insurance and government where data sovereignty and auditability are non-negotiable. SMEs are the fastest-growing enterprise tier, driven by SaaS pricing and plug-and-play ERP connectors.
North America leads with roughly 35.5% of global revenue, underpinned by mature financial infrastructure, early automation adoption and the presence of major vendors. Asia-Pacific is the fastest-growing region at mid-to-high teens CAGR, propelled by fintech expansion in China and India.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.2% |
| Asia-Pacific | 0.28% |
| South America | 0.07% |
| Middle East & Africa | 0.1% |
| Region | Share (2024/25) | Growth Profile |
|---|---|---|
| North America | ~35.5% | Mature, steady |
| Europe | ~20% | Steady, regulation-led |
| Asia-Pacific | ~28% | Fastest growing |
| Middle East & Africa | ~10% | Emerging |
| South America | ~6.5% | Emerging |
The regional divergence implies a two-speed market: North America monetizes replacement and AI-upgrade cycles, while Asia-Pacific monetizes first-time digitization. Vendors must run different pricing and channel playbooks for each.
Growth is driven by transaction complexity, regulatory scrutiny and cloud economics, while adoption is restrained by integration cost, legacy resistance and cybersecurity caution in regulated sectors.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising transaction volume & digital payments | Driver | High | More records to match, manual fails at scale |
| Regulatory compliance (IFRS, SOX, audit trails) | Driver | High | Automation enforces auditable reconciliation |
| Cloud & SaaS scalability | Driver | High | Low upfront cost, fast deployment |
| AI/ML anomaly detection | Driver | Medium-High | Real-time exception flagging, fewer false matches |
| ERP/core banking integration demand | Driver | High | End-to-end visibility, no manual re-entry |
| High implementation & integration cost | Restraint | Medium | ROI justification harder for SMEs |
| Legacy system resistance & skills gap | Restraint | Medium | Change management burden |
| Cybersecurity & data-privacy concerns | Restraint | Medium | Cloud caution in BFSI and government |
The balance favors growth, but the constraints are concentrated in the SME and legacy-heavy segments, which is precisely where the next wave of adoption must come from. Our analysis suggests vendors that solve the "integration tax"—prebuilt connectors and templated migrations—will unlock the SME tier faster than feature-led competitors.
Competition is fragmented but consolidating, with horizontal financial-close suites, BFSI specialists and ERP-native platforms competing on matching depth, integration breadth and AI capability.
| Vendor | Positioning | Notable Strength |
|---|---|---|
| BlackLine | Financial close & reconciliation suite | Large enterprise install base |
| Trintech | Close automation, acquired Fiserv reconciliation assets | Cloud reconciliation depth |
| Oracle | ERP-native reconciliation | Ecosystem lock-in |
| SAP SE | ERP-native reconciliation | Global enterprise reach |
| AutoRek | BFSI reconciliation specialist | Regulatory reporting |
| FloQast | Close management & reconciliation | Mid-market usability |
| HighRadius | AI-led receivables & reconciliation | Autonomous finance positioning |
| OneStream | Unified finance platform | Consolidation + reconciliation |
| Wolters Kluwer | Compliance-led reconciliation | Regulatory content depth |
| Broadridge | Post-trade & reconciliation | Capital markets niche |
The moat is shifting from matching algorithms to data connectivity and AI exception management. Vendors that own the ERP/bank connector layer and can prove real-time matching accuracy have the strongest pricing power; standalone tools risk being bundled into suites.
Buyers should prioritize matching accuracy, integration breadth and auditability over raw feature count. The most common procurement failure is underestimating integration effort with legacy core banking and ERP systems; total cost of ownership often exceeds licence cost within two years. Switching costs rise steeply once reconciliation workflows, rules and audit trails are embedded, so contract governance and exit clauses matter.
Regulatory compliance is a non-negotiable selection criterion in BFSI, where audit trails, data residency and explainability of AI matching are scrutinized. Operators should insist on model explainability and configurable rule overrides, since opaque AI matching can create audit risk. Real-time reconciliation is becoming a baseline expectation in retail and e-commerce, where exception resolution windows are shrinking to hours.
The balance of evidence favors sustained double-digit expansion anchored at 13–14% CAGR, with cloud and BFSI as the load-bearing segments. The strongest counter-argument is that consolidation into ERP and close-management suites could compress standalone reconciliation pricing; however, regulatory depth and real-time matching requirements make full substitution unlikely in the near term.
Our analysis suggests the competitive axis is moving from deployment model to AI-driven exception intelligence and connector ecosystems. Vendors pricing on seat count alone will erode margins as cloud competition intensifies; those monetizing match accuracy and audit-grade explainability will defend pricing.
Actionable strategy for investors and operators:
The evidence that would change this conclusion: a sharp decline in cloud ASPs combined with ERP vendors bundling reconciliation at no incremental cost, which would compress standalone market value below the 13% baseline.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.1% from 2020-2034 |
| Segmentation |
|
Published estimates place the global market at roughly 2.5–3.3 billion in the 2024–2026 window, depending on definitional scope. Our baseline anchors at 3.32 billion for 2026, growing toward 7.54 billion by 2033.
Long-horizon estimates cluster at 13.1%–13.7% CAGR through 2033–2034. Near-term figures as high as 18.6% reflect narrower bases and service inclusion rather than a different demand trajectory.
Cloud deployment leads with about 60% share and is the fastest-growing model. BFSI is the largest end-user vertical at roughly 47%, while retail and e-commerce is the fastest-growing vertical.
Asia-Pacific is expected to be the fastest-growing region, driven by fintech expansion and digital payments in China and India, while North America retains the largest share at about 35.5%.
Leading vendors include BlackLine, Trintech, Oracle, SAP, AutoRek, FloQast, HighRadius, OneStream and Wolters Kluwer, with competition intensifying around AI matching and ERP integration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with structured depth interviews conducted across the value chain: reconciliation software vendors, specialized AI-matching module developers, ERP and core-banking integration partners, and global channel distributors. Decision-makers interviewed include VP of Finance Technology, Heads of Financial Close, Technical Directors of Integration, and Commercial Operations Leads. Interviews were structured to isolate willingness-to-pay, integration effort and switching-cost thresholds.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Finance Technology | 35% |
| Heads of Financial Close | 30% |
| Technical Integration Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Reconciliation Software Vendors | 40% |
| AI/Matching Module Developers | 25% |
| ERP & Core Banking Integrators | 20% |
| Global Distributors & Channel Partners | 15% |
We validate demand against official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards bodies and industry associations. Vendor revenue is cross-checked against disclosed segment reporting and channel disclosures.
Sizing uses simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (vendor capacity, subscription pricing, and end-use consumption modeling) triangulation. Divergences are reconciled through weighted averaging and sensitivity testing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |