 Us Cell Culture Media Cell Lines Market
 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 185

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Cell Culture Media Cell Lines Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 5.100 B |
| 2025 | 5.600 B |
| 2026 | 6.100 B |
| 2027 | 6.700 B |
| 2028 | 7.300 B |
| 2029 | 8.000 B |
| 2030 | 8.800 B |

The U.S. cell culture media and cell lines market covers nutrient formulations — classical, specialty, serum-free and chemically defined — plus immortalized and primary cell lines such as CHO, HEK293 and HeLa, sold to biopharma, CROs, diagnostics labs and academic institutes for biologics production, drug screening and regenerative research.
This analysis covers U.S. revenue from cell culture media (basal, classical, specialty, serum-free, chemically defined, stem cell media) and cell lines (traditional immortalized lines, stem cells and blood-derived cells), segmented by product, application and end use through 2034. This analysis does not cover bioreactors and single-use hardware, cell culture plastics and consumables, ancillary reagents such as transfection agents, or cell and gene therapy manufacturing services.
The U.S. market is best framed at roughly USD 5.3–6.1 billion in 2025–2026, depending on whether cell-line licensing revenue is counted alongside media.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 5.8B (global) → USD 11.2B | 2026 | 2033 | 9.8% | Media plus cell lines, global, all end uses | One published estimate |
| USD 4.57B (U.S.) | 2024 | 2034 | 9.20% | Media plus cell lines, U.S. only | A competing analysis |
| USD 3.9B → USD 10.8B (media only, global) | 2025 | 2035 | 10.8% | Media only, excludes cell lines | A third published estimate |
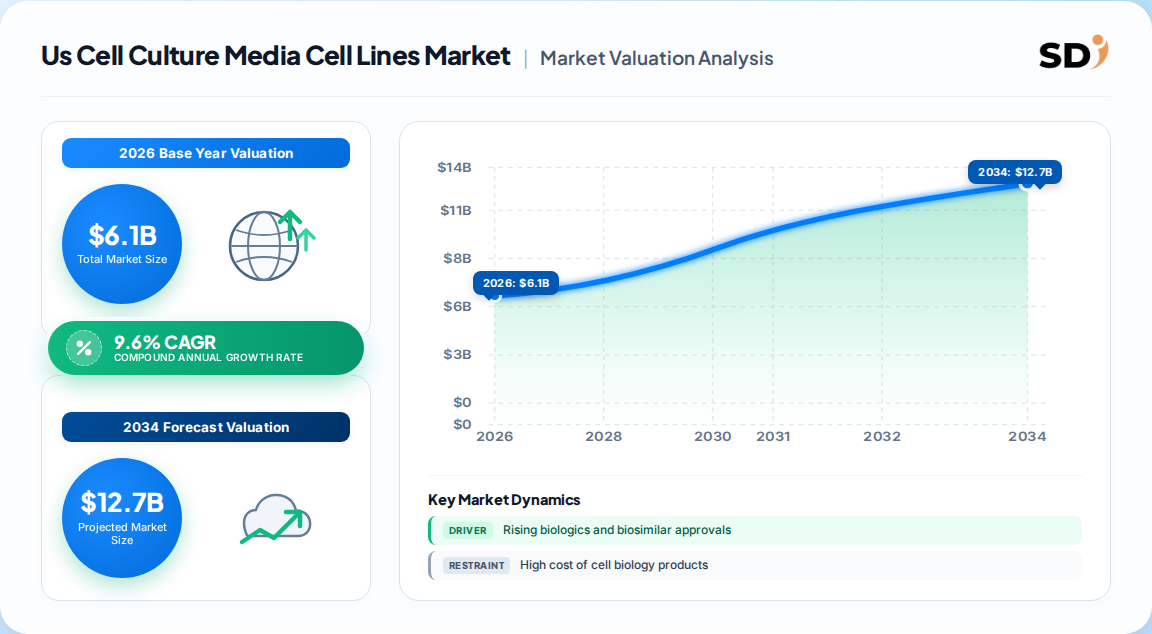
| USD 6.1B (U.S., modeled) | 2026 | 2034 | 9.6% | Media plus cell lines, U.S., all end uses | Our synthesis of the above |
The most defensible figure is the 9.2% U.S.-specific trajectory: it is the only estimate scoped precisely to this geography and product bundle. Our analysis suggests the media-only global CAGR of 10.8% is inflated by a narrower denominator and should not be transplanted onto a U.S. market where licensing and cell-line revenues grow more slowly. The implication: plan on high-single-digit growth, not double digits.
Product is the decisive segmentation axis: media and cell lines have different margin structures, qualification cycles and regulatory exposure, and buyers rarely procure them through the same channel.
| Parent segment | Children |
|---|---|
| By Product | Traditional cell lines, stem cells and blood-derived cells, classical media, specialty media, serum-free media, chemically defined media |
| By Application | Biopharmaceutical production, diagnostics, drug screening and development, tissue engineering and regenerative medicine, other |
| By End Use | Large biopharmaceutical companies, small and mid-sized biotechs, CROs/CMOs, research and academic institutes, hospitals and diagnostic laboratories |
Specialty media at 44.12% of U.S. product revenue reflects a structural shift: buyers pay a premium for formulations tied to a specific clone or workflow. Cell lines, by contrast, are increasingly licensed rather than sold outright, which suppresses reported product revenue while raising switching costs.
The United States is itself the market, so the meaningful geography question is internal: which state clusters concentrate demand and supply.
California and Massachusetts together anchor discovery-stage and CGT demand; North Carolina and Maryland concentrate large-scale manufacturing capacity. Our analysis suggests capacity additions in the Research Triangle will make it the fastest-growing sub-national demand node through 2030, which matters for distributors sizing local inventory and service coverage.
Biologics pipeline expansion and the shift to serum-free, chemically defined media are the dominant growth engines, while media cost and regulatory complexity cap conversion at smaller buyers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Biosimilar and biologics approvals | Growth | High | Each commercial-scale program locks in multi-year media volume |
| Serum-free and chemically defined transition | Growth | High | Higher price per litre, better reproducibility |
| Cell and gene therapy pipeline (2,000+ programs globally) | Growth | Medium | Custom formulations for stem cells and viral vectors |
| CDMO outsourcing | Growth | Medium | Consolidated, specification-locked purchasing |
| High cost of cell biology products | Restraint | High | Delays adoption at academic and small biotech buyers |
| Stringent regulatory requirements | Restraint | Medium | Long qualification cycles slow vendor switching |
The balance favors suppliers with regulatory documentation depth. Restraints are largely friction rather than demand destruction — buyers defer, they rarely cancel. That asymmetry implies pricing power persists for qualified vendors, but only where technical files support audit readiness.
Five suppliers control roughly 78.1% of global media revenue, and the U.S. market is even more concentrated because all five have domestic manufacturing and applications labs.
| Vendor | Position | Differentiation |
|---|---|---|
| Thermo Fisher Scientific | Leader, >35% share | Broadest portfolio, Gibco brand, deep U.S. applications support |
| Merck KGaA | Top-tier | Strong chemically defined and process-scale offering |
| Cytiva (Danaher) | Top-tier | Integrated bioprocessing plus viral vector capability |
| Sartorius | Top-tier | Media paired with single-use hardware and analytics |
| FUJIFILM Irvine Scientific | Top-tier | Specialist in serum-free and stem cell formulations |
| Lonza, ATCC, Corning | Specialist | Cell lines, licensing and platform media |
Moats are built on regulatory documentation, not formulation chemistry. Once a media is written into a filed process, switching requires comparability work costing months and six figures. This is why M&A activity — such as platform and cell-line acquisitions — targets qualification assets rather than manufacturing capacity.
Selection criteria are dominated by regulatory documentation and supply continuity. Buyers should demand drug master files, lot-to-lot traceability, and evidence of dual-site manufacturing before qualifying a single-source supplier. Price negotiation is secondary to qualification risk.
Procurement risk is highest where a formulation is tied to a licensed cell line from the same vendor; that bundle creates near-total lock-in and exposes the buyer to allocation decisions during demand spikes. Operators should model a qualified second source at least eighteen months before commercial launch.
Switching costs are asymmetric: media changes require comparability studies, while cell-line changes can invalidate prior analytical validation entirely. Regulatory compliance obligations under cGMP and USP guidance make this a multi-quarter project, not a purchase-order decision.
The balance of evidence favors a high-single-digit growth market (9.2–9.8%) concentrated in a handful of qualified suppliers, not the double-digit media-only figures circulating in some analyses. The strongest counter-argument is that cell and gene therapy customization could push specialty media growth well above the blended rate — plausible, but CGT remains a small revenue base relative to monoclonal antibody production through 2030.
Our analysis suggests the real competitive battleground is documentation and local applications support, not formulation novelty. Vendors that invest in regulatory files and U.S.-based process support will convert pipeline wins into decade-long revenue locks; those competing on price will be confined to research-grade demand with thin margins.
For buyers, the corollary is that supply resilience is now a strategic asset. Dual-sourcing costs less than a stalled commercial batch.
What would change this conclusion: sustained CGT approval volumes above twenty per year, or a credible serum-free alternative that shortens comparability timelines. Either would compress switching costs and reward price-led entrants.
Our analysis rests on a 70/30 primary-to-secondary split. We conducted structured interviews with raw material and hydrolysate suppliers, specialty media formulators, cell-line repositories and licensors, contract formulators, and U.S. distributors. Within these organizations we interviewed VP-level sourcing leads, heads of R&D, technical directors, and commercial operations leads to calibrate qualification timelines and switching costs.
We triangulated against U.S. International Trade Commission trade flows, UN Comtrade biological reagent categories, SEC 10-K filings and investor presentations from listed suppliers, patent filings covering chemically defined formulations, and USP and ISO guidance governing biological starting materials.
Top-down allocation from U.S. biopharmaceutical manufacturing expenditure was run simultaneously with bottom-up modeling of supplier capacity, price per litre by media class, and end-use consumption. Divergence between the two was reconciled at segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | USD value, 2026 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2034 | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | U.S. sub-national demand | Trade flow and consumption analysis | High |
| Competitive Landscape | Leading suppliers | Annual reports and capacity mapping | High |
| Region | Market Share (%) |
|---|---|
| North America | 0.96% |
| Europe | 0.02% |
| Asia-Pacific | 0.02% |
| Middle East & Africa | 0.01% |

| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.6% from 2020-2034 |
| Segmentation |
|
Approximately USD 6.1 billion in 2026 on our synthesis, with published estimates ranging from USD 4.57 billion to nearly USD 6 billion depending on whether cell-line licensing is included.
Around 9.6% annually through 2034. Published U.S.-specific estimates cluster near 9.2%, while broader global media-only forecasts reach 10.8% on a narrower denominator.
Specialty media led U.S. product revenue at 44.12% in 2024, and biopharmaceutical production is the largest application at roughly 45.8% of global revenue.
Thermo Fisher Scientific leads with over 35% global share; Merck KGaA, Cytiva, Sartorius and FUJIFILM Irvine Scientific follow, together holding 78.1% of global media revenue.
Media specified in a filed regulatory process requires comparability studies to change, typically taking months and significant cost, which creates durable lock-in once a commercial program is qualified.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a 70/30 primary-to-secondary research split. Structured interviews were conducted across the value chain: raw material and hydrolysate suppliers, specialty media formulators, cell-line repositories and licensors, contract formulators, and U.S. distributors. Within these organizations we engaged decision-makers designated as VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, calibrating qualification cycles, switching costs, and allocation behavior under demand stress.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Hydrolysate Suppliers | 30% |
| Specialty Media Formulators | 40% |
| Cell Line Repositories & Licensors | 15% |
| U.S. Distributors | 15% |
We benchmarked against U.S. International Trade Commission trade statistics, UN Comtrade biological reagent categories, WTO tariff schedules, SEC 10-K filings and investor presentations from listed suppliers, patent databases covering chemically defined and serum-free formulations, and USP, ISO and FDA guidance governing biological starting materials and cGMP manufacturing.
Top-down allocation from U.S. biopharmaceutical manufacturing expenditure ran simultaneously with bottom-up modeling of supplier capacity, price per litre by media class, and end-use consumption. Segment-level divergence between the two approaches was reconciled and weighted by evidence confidence.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | USD value for 2026 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2034 projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | U.S. sub-national demand | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading suppliers | Annual reports, capacity mapping, commercial filings | High |