 AI Assistant Software Market
 Outlook, Size & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 207

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 AI Assistant Software Market
Srinwanti Kar
Senior Research Analyst

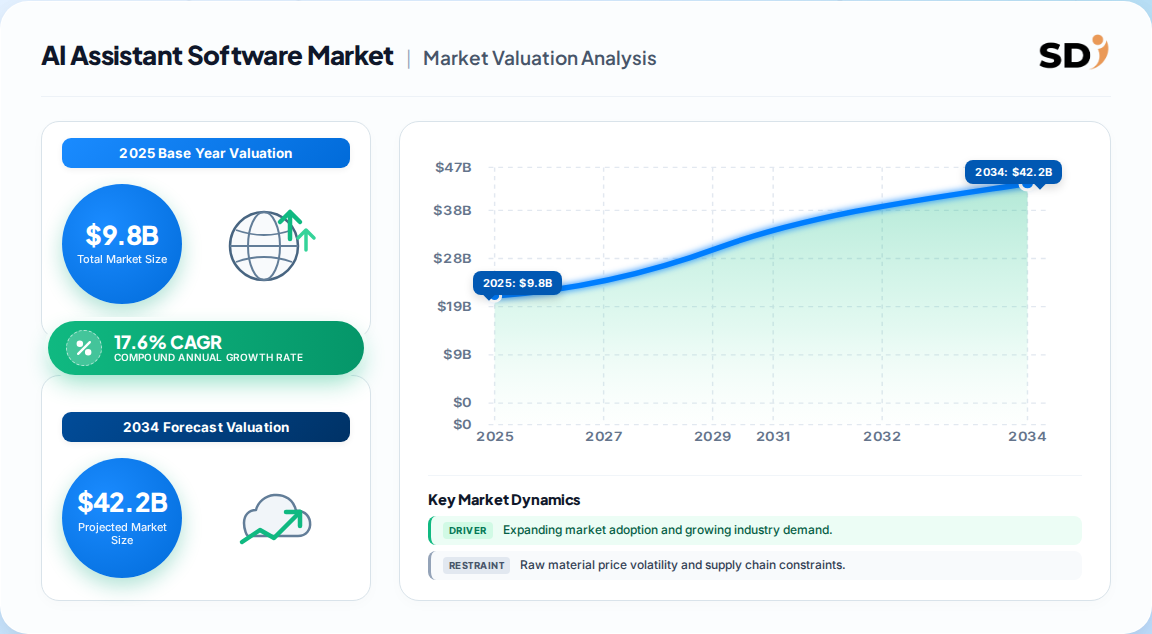
| Year | Market Size |
|---|---|
| 2025 | 9.800 B |
| 2026 | 11.50 B |
| 2027 | 13.50 B |
| 2028 | 15.90 B |
| 2029 | 18.70 B |
| 2030 | 22.00 B |
| 2031 | 25.90 B |

The AI Assistant Software Market covers software and services that use large language models, NLP and machine learning to interpret natural-language requests and execute tasks — drafting content, summarizing, retrieving knowledge and triggering workflows — across customer service, IT, sales and knowledge management in cloud, on-premises and hybrid deployments.
This analysis covers AI assistant software platforms and associated implementation, integration and managed services across chatbots, generative assistants, task-specific assistants and general-purpose assistants, segmented by component, functionality, application and region. It includes enterprise and consumer deployments. This analysis does not cover AI model training infrastructure, GPU/hardware supply, standalone robotic process automation tooling, or AI writing-assistant point solutions treated as a discrete category.
One published estimate puts the market at USD 9.8 billion in 2025, growing to USD 35.7 billion by 2033 at 17.6% CAGR — a mid-teens trajectory consistent with enterprise adoption curves for productivity software at scale. A rival analysis of the adjacent AI writing-assistant niche implies far higher growth, which requires reconciliation.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 9.8B → USD 35.7B | 2025 | 2033 | 17.6% | Full AI assistant software + services (chatbots, generative, task-specific, general-purpose) | One published industry estimate |
| USD 1.77B → USD 4.88B | 2025 | 2030 | 22.49% | AI writing assistants only (narrow content-creation subset) | A competing analysis |
| USD 91.3B → USD 988.5B | 2025 | 2035 | 26.90% | Broad "AI writing assistant" definition, apparently absorbing adjacent productivity software | A competing analysis |
Our analysis suggests the USD 9.8B base is the most defensible: it is the only figure with a scope definition tightly matched to assistant software rather than productivity suites generally. The USD 91B-plus figure almost certainly double-counts embedded assistants inside office suites, which inflates the base by an order of magnitude and is not usable for procurement benchmarking.
Segmentation matters because growth rates diverge sharply by layer: software outpaces services, and generative assistants are displacing rule-based chatbots fastest. Buyers should map spend against these buckets rather than treating "AI assistant" as one line item.
| Parent Segment | Children | 2025 Share / Signal |
|---|---|---|
| Component | Software, Services | Software 66.9% |
| Functionality | Chatbots, Generative AI Assistants, Task-specific Assistants, General-purpose Assistants | Chatbots 33.7% |
| Application | Customer Service & Support, IT & Operations, Sales & Marketing, Knowledge Management, Software Development | Customer Service 34.9% |
| Deployment | Cloud, On-premises, Hybrid | Hybrid rising fastest |
| End User | Large Enterprise, SME, Individual | Large enterprise dominant |
The chatbot lead is a legacy artefact — installed base, not growth. Generative assistants carry higher contract values and are cannibalizing chatbot renewals, so the segment share table understates where new budget is actually flowing.
North America led with 37.4% of 2025 revenue, supported by mature cloud infrastructure and early enterprise generative-AI budgets. Asia Pacific is the fastest-growing region, driven by large-scale platform launches and government-backed AI infrastructure investment.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 Revenue Share |
|---|---|
| North America | 37.4% |
| Asia Pacific | 26.8% |
| Europe | 24.3% |
| Latin America | 6.2% |
| Middle East & Africa | 5.3% |
The divergence implies a two-speed market: North America monetizes governance and integration services, while Asia Pacific compresses unit pricing through platform bundling. Our analysis suggests European share is capped near-term by data-residency and watermarking compliance overhead rather than demand.
Generative AI and LLM maturity is the primary engine, enabling assistants to handle open-ended, multi-step business interactions rather than scripted queries. The binding constraint is not demand but integration cost and data-governance risk.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Generative AI / LLM adoption | Driver | Strong | Expands task scope from FAQ to drafting, reasoning and execution |
| Enterprise productivity SaaS demand | Driver | Strong | Shifts spend from pilot budgets to core productivity lines |
| Digital marketing content volume | Driver | Moderate | Sustains conversational and content assistant usage |
| Multifunctional platform consolidation | Driver | Moderate | Reduces tool sprawl, raises per-seat value |
| High implementation & integration cost | Restraint | Strong | Delays mid-market deployment, favors incumbents |
| Data privacy and IP ownership | Restraint | Strong | Blocks regulated-sector rollouts, EU especially |
| Hallucination and brand risk | Restraint | Moderate | Requires human-in-the-loop, caps automation rate |
| Compute cost volatility | Restraint | Moderate | Constrains margin at high-volume, low-price tiers |
So what? The restraint side is operational, not structural — it slows deals rather than cancelling them. Vendors that solve governance first (policy controls, data residency, audit logging) convert stalled pipelines into multi-year contracts, which is exactly the pattern observed when copilot governance consoles launched.
The field splits into platform bundlers, model owners and domain specialists. Bundlers win on distribution and procurement simplicity; model owners win on capability cadence; specialists survive only where compliance or vertical depth is defensible.
| Vendor | Positioning | Core Strength | Strategic Vulnerability |
|---|---|---|---|
| Microsoft | Suite-bundled copilot | Enterprise distribution, governance controls | Perceived as forced attach; pricing scrutiny |
| Model + workspace integration | Model capability, consumer reach | Fragmented enterprise go-to-market | |
| OpenAI | Model and assistant API | Frontier capability, developer mindshare | Limited enterprise governance layer |
| IBM | Regulated-industry assistant | Compliance, hybrid deployment | Slower feature cadence |
| Alibaba | Asia Pacific platform | Regional scale, integrated reasoning | Geopolitical market-access limits |
| Grammarly-type specialists | Writing-focused assistant | Domain tuning, brand trust | Bundling pressure from suites |
Our analysis suggests the moat is migrating from model quality to workflow integration and data access. Model parity is arriving faster than integration parity, which means distribution — not benchmarks — determines renewal outcomes.
Selection should be anchored on four criteria: integration depth into existing systems of record, governance and data-residency posture, measurable task-completion accuracy on your own corpus, and pricing model durability. Vendors frequently demo well on generic prompts and underperform on proprietary data, so require a scored pilot against internal benchmarks before commitment.
Procurement risk concentrates in pricing structure. Seat-based licensing looks predictable but caps value if assistants execute work; consumption pricing aligns incentives but exposes buyers to cost drift. Negotiate hybrid terms with usage ceilings and annual true-down rights. Switching costs are moderate for front-end assistants but severe once an assistant is embedded in CRM or ITSM workflows via custom connectors.
Regulatory compliance is now a gating factor, not a checkbox. EU data-residency, content-watermarking and IP-ownership rules, plus sector rules in financial services and healthcare, determine whether deployments clear audit. Buyers in regulated verticals should prioritize vendors with documented policy-control consoles and contractual indemnities for generated output. Precise sub-segment forecasting by functionality and vertical requires the full report.
The balance of evidence favors a consolidation thesis over a fragmentation thesis. A 17.6% CAGR on a USD 9.8B base is high but not explosive — it is consistent with assistants becoming an embedded layer of productivity suites rather than a standalone category. The strongest counter-argument is Asia Pacific platform bundling, which could accelerate growth beyond 17.6% while simultaneously destroying per-seat pricing power; that combination would produce higher volume with lower vendor margins.
Our judgment: value accrues to whoever controls the workflow surface, not the model. Two data points support this — the chatbot segment's outsized share reflects installed workflow position, and the multifunctional platform trend reflects vendors racing to own end-to-end task execution. Buyers should therefore treat integration capability as the primary diligence item and model capability as a fast-depreciating secondary one.
Actionable strategy:
What would change our conclusion: a sustained step-change in agentic task autonomy that decouples assistants from existing software surfaces, or regulatory clarity that removes European deployment friction. Either would shift the opportunity toward pure-play assistant vendors and away from suite bundlers.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.6% from 2020-2034 |
| Segmentation |
|
The global AI Assistant Software Market was valued at approximately USD 9.8 billion in 2025 and is estimated at USD 11.5 billion in 2026, with a forecast of USD 35.7 billion by 2033 at 17.6% CAGR.
The market is projected to grow at 17.6% CAGR from 2026 to 2033. That is roughly three times baseline enterprise software growth, reflecting budget reallocation toward automation rather than incremental new spend.
North America led with 37.4% of 2025 revenue, supported by mature cloud infrastructure and early generative-AI enterprise budgets. Asia Pacific is the fastest-growing region, driven by platform launches and government-backed AI infrastructure investment.
Software held 66.9% of 2025 component revenue, chatbots led functionality at 33.7%, and Customer Service & Support led applications at 34.9%. Chatbot share reflects installed base more than growth, as generative assistants cannibalize renewals.
High implementation and integration costs, data-privacy and IP-ownership concerns, hallucination and brand risk, and compute-cost volatility. These are operational frictions that delay deals rather than structural limits on demand.
Leading vendors include Microsoft, Google, OpenAI, IBM, Alibaba and domain specialists such as Grammarly. Platform bundlers win on distribution and procurement simplicity, while model owners compete on capability cadence.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted with decision-makers across the value chain: enterprise software buyers, systems integrators, cloud infrastructure providers, independent software vendors and managed-service operators. On the demand side, we interviewed VP-level sourcing leads, Heads of IT and Digital Transformation, Chief Data and Compliance Officers, and Commercial Operations Leads responsible for tooling budgets. Interviews captured deployment economics, procurement criteria, renewal behavior and governance requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| IT & Digital Transformation Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Compliance & Data Privacy Officers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Enterprise Software Buyers | 40% |
| ISVs & Platform Vendors | 30% |
| Systems Integrators & Cloud Providers | 20% |
| Managed Service Operators | 10% |
Secondary validation draws on official multilateral and national sources: UN Comtrade and WTO services-trade statistics, US ITC digital-services filings, Eurostat ICT usage surveys, corporate annual reports and SEC 10-K disclosures from publicly listed software vendors, patent databases for assistant-related IP filings, and recognized industry associations and technical standards bodies publishing AI governance frameworks.
Sizing runs two parallel tracks. Top-down allocation applies macroeconomic software-spend envelopes to the assistant category by industry and region. Bottom-up modeling aggregates vendor revenue, seat and consumption volumes, average contract values and end-use deployment counts. Divergence between tracks is reconciled at segment level before forecast publication.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade-flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capability mapping, filings | High |