Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Data Diode Market Size, Trends & Forecast to 2030
Data Diode Market
Data Diode Market Size, Trends & Forecast to 2030
Data Diode Market by Type (Ruggedized, Non-Ruggedized), by Component (Hardware Components, Software Components, Services), by Deployment Type (On-Premises Deployment, Cloud-Based Deployment), by Key Technologies (Optical Isolation, Protocol Conversion, Traffic Filtering And Packet Inspection), by End-User (Government Agencies, Private Sector Organizations, Critical Infrastructure Operators, Healthcare Providers, Financial Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 218
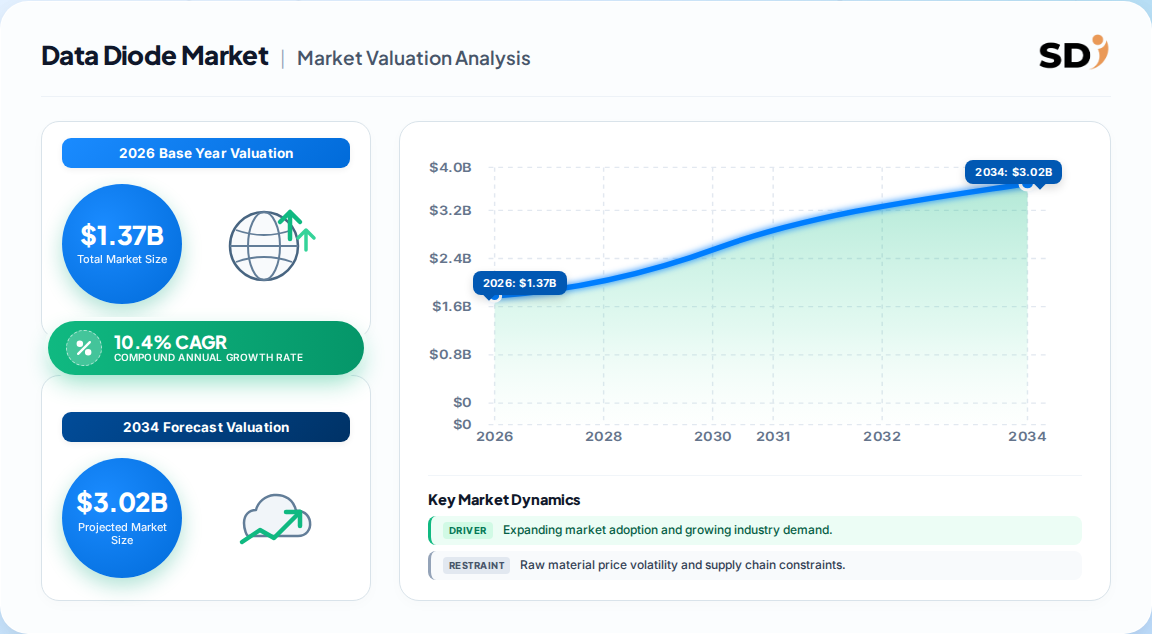
The global Data Diode Market reached 1.37 Billion in 2026, on track to 2.03 Billion by 2030 at a 10.4% CAGR, reflecting sustained demand for unidirectional security gateways.
On-premises deployment is the largest opportunity, adding 520.91 Million in incremental value through 2030, driven by critical infrastructure and defense use cases.
Optical isolation technology leads adoption, with an expected gain of 430.31 Million, as buyers prioritize physically enforced one-way data flows over software-based segmentation.
North America remains the largest regional market (≈36% share), while Asia-Pacific is the fastest-growing region, fueled by smart grid and industrial digitization.
Leading vendors include Owl Cyber Defense Solutions, Advenica AB, and Forcepoint LLC, alongside specialists like Waterfall Security and ST Engineering.
Why this matters for decision-makers: Buyers must prioritize vendors with certified optical isolation and OT-protocol coverage; commoditized software diodes will face margin compression as regulatory mandates tighten.
Data Diode Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.230 B
2025
1.370 B
2026
1.510 B
2027
1.670 B
2028
1.840 B
2029
2.030 B
2030
Data Diode Market Size (In Billion)
Year
Market Size
2025
1.230 B
2026
1.370 B
2027
1.510 B
2028
1.670 B
2029
1.840 B
2030
2.030 B
What is the Data Diode Market?
The Data Diode Market comprises hardware and software systems that enforce one-way data transfer between networks, physically preventing inbound access. These unidirectional gateways protect air-gapped and critical OT environments from cyber threats while enabling secure data egress for monitoring and compliance.
Scope: what this report covers and excludes
This analysis covers global data diode hardware, software, and services across government, defense, energy, and industrial end-users. It segments by type (ruggedized/non-ruggedized), component, deployment, technology, and end-user. This analysis does not cover adjacent markets such as firewalls, VPNs, or general network security appliances.
How big is the market for Data Diode Market?
The Data Diode Market is valued between 644.10 Million and 1.37 Billion depending on scope definition, with a consensus forecast of 2.03 Billion by 2030. The divergence stems from differing inclusions of services and software versus hardware-only counting.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
1.37 Billion
2026
2030
10.4%
Hardware + software + services, global
Published market report (2026)
644.10 Million
2025
2035
8.10%
Data diode solutions (narrower scope)
Competing analysis (EMR)
1.23 Billion
2025
2030
11.2%
Historical base for 2026 estimate
Published market report (2026)
Our analysis suggests the 1.37 Billion (2026) figure is most defensible for procurement planning because it captures the full solution stack—including integration services—that buyers actually purchase. The narrower 644.10 Million estimate likely excludes services and software-defined deployments, understating total addressable spend.
How is the market segmented?
The Data Diode Market segments by type, component, deployment, technology, and end-user, with on-premises and optical isolation dominating value. Ruggedized variants command premium pricing in defense and energy.
North America leads the Data Diode Market with approximately 36% share, driven by defense and critical infrastructure spending, while Asia-Pacific is the fastest-growing region at a double-digit CAGR.
Data Diode Market Regional Market Share
Loading chart...
Data Diode Market Regional Market Share
Region
Market Share (%)
North America
0.36%
Europe
0.27%
Asia-Pacific
0.24%
Latin America
0.07%
Middle East & Africa
0.06%
North America (USA, Canada, Mexico)
USA
Canada
Mexico
Europe (Germany, UK, France, Italy)
Germany
UK
France
Italy
Asia Pacific (China, Japan, India, South Korea)
China
Japan
India
South Korea
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
This geographic concentration implies that vendors should maintain strong North American channel presence while investing in Asia-Pacific localization to capture the fastest growth.
What is driving growth — and what is holding it back?
Rising cyber threats and regulatory mandates are the primary growth drivers, while high deployment costs and complexity restrain broader adoption. The balance favors growth, as ransomware attacks on OT systems accelerate spending.
Factor
Direction
Evidence Strength
Mechanism
Rising cyber threats
Driver
High
Increased attacks on critical infrastructure drive adoption
IIoT expansion creates need for secure data egress
High deployment cost
Restraint
Medium
Hardware and integration costs limit SMB adoption
Complexity of integration
Restraint
Medium
Protocol conversion challenges slow deployment
Who are the leading vendors?
Leading vendors include Owl Cyber Defense Solutions, Advenica AB, and Forcepoint LLC, with Waterfall Security and ST Engineering as notable specialists. Competition centers on certified optical isolation and OT protocol support.
Company
Headquarters
Key Differentiator
Owl Cyber Defense Solutions
USA
Broad certified product portfolio
Advenica AB
Sweden
High-assurance optical isolation
Forcepoint LLC
USA
Integrated data security platform
Waterfall Security Solutions
Israel
OT-focused unidirectional gateways
ST Engineering
Singapore
Ruggedized defense-grade diodes
Differentiation is built on certifications (Common Criteria, FIPS 140-2) and protocol coverage; vendors lacking OT-specific certifications face pricing pressure.
What do buyers and operators need to know?
Buyers must prioritize certified optical isolation, OT protocol coverage, and vendor support for regulatory audits. Procurement risks include integration complexity with legacy SCADA systems and long qualification cycles. Switching costs are high once deployed in air-gapped environments, so total cost of ownership should be evaluated over a 5–7 year horizon. Regulatory compliance—such as NERC CIP, IEC 62443, and NIS2—should be a mandatory selection criterion, not an afterthought.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors sustained double-digit growth in the Data Diode Market, driven by regulatory mandates and OT security spending. The strongest counter-argument is that software-defined segmentation could cannibalize hardware diode demand; however, physical one-way enforcement remains irreplaceable for the highest-assurance environments.
Our analysis suggests vendors should focus on certified optical isolation and OT protocol breadth to capture premium segments. Buyers should prioritize vendors with proven integration support and regulatory alignment to reduce deployment risk.
Actionable Strategy:
Investors should target vendors with ruggedized, certified portfolios serving defense and energy, where margins are defensible.
Operators should mandate IEC 62443 and NERC CIP compliance in RFPs to future-proof deployments.
Vendors should invest in Asia-Pacific localization to capture the fastest-growing regional demand.
What would change our conclusion: a sharp decline in regulatory enforcement or rapid commoditization of optical isolation hardware would lower the growth trajectory.
Data Diode Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Data Diode Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.4% from 2020-2034
Segmentation
By Type
Ruggedized
Non-Ruggedized
By Component
Hardware Components
Software Components
Services
By Deployment Type
On-Premises Deployment
Cloud-Based Deployment
By Key Technologies
Optical Isolation
Protocol Conversion
Traffic Filtering And Packet Inspection
By End-User
Government Agencies
Private Sector Organizations
Critical Infrastructure Operators
Healthcare Providers
Financial Institutions
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Ruggedized
5.1.2. Non-Ruggedized
5.2. Market Analysis, Insights and Forecast - by Component
5.2.1. Hardware Components
5.2.2. Software Components
5.2.3. Services
5.3. Market Analysis, Insights and Forecast - by Deployment Type
5.3.1. On-Premises Deployment
5.3.2. Cloud-Based Deployment
5.4. Market Analysis, Insights and Forecast - by Key Technologies
5.4.1. Optical Isolation
5.4.2. Protocol Conversion
5.4.3. Traffic Filtering And Packet Inspection
5.5. Market Analysis, Insights and Forecast - by End-User
5.5.1. Government Agencies
5.5.2. Private Sector Organizations
5.5.3. Critical Infrastructure Operators
5.5.4. Healthcare Providers
5.5.5. Financial Institutions
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Ruggedized
6.1.2. Non-Ruggedized
6.2. Market Analysis, Insights and Forecast - by Component
6.2.1. Hardware Components
6.2.2. Software Components
6.2.3. Services
6.3. Market Analysis, Insights and Forecast - by Deployment Type
6.3.1. On-Premises Deployment
6.3.2. Cloud-Based Deployment
6.4. Market Analysis, Insights and Forecast - by Key Technologies
6.4.1. Optical Isolation
6.4.2. Protocol Conversion
6.4.3. Traffic Filtering And Packet Inspection
6.5. Market Analysis, Insights and Forecast - by End-User
6.5.1. Government Agencies
6.5.2. Private Sector Organizations
6.5.3. Critical Infrastructure Operators
6.5.4. Healthcare Providers
6.5.5. Financial Institutions
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Ruggedized
7.1.2. Non-Ruggedized
7.2. Market Analysis, Insights and Forecast - by Component
7.2.1. Hardware Components
7.2.2. Software Components
7.2.3. Services
7.3. Market Analysis, Insights and Forecast - by Deployment Type
7.3.1. On-Premises Deployment
7.3.2. Cloud-Based Deployment
7.4. Market Analysis, Insights and Forecast - by Key Technologies
7.4.1. Optical Isolation
7.4.2. Protocol Conversion
7.4.3. Traffic Filtering And Packet Inspection
7.5. Market Analysis, Insights and Forecast - by End-User
7.5.1. Government Agencies
7.5.2. Private Sector Organizations
7.5.3. Critical Infrastructure Operators
7.5.4. Healthcare Providers
7.5.5. Financial Institutions
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Ruggedized
8.1.2. Non-Ruggedized
8.2. Market Analysis, Insights and Forecast - by Component
8.2.1. Hardware Components
8.2.2. Software Components
8.2.3. Services
8.3. Market Analysis, Insights and Forecast - by Deployment Type
8.3.1. On-Premises Deployment
8.3.2. Cloud-Based Deployment
8.4. Market Analysis, Insights and Forecast - by Key Technologies
8.4.1. Optical Isolation
8.4.2. Protocol Conversion
8.4.3. Traffic Filtering And Packet Inspection
8.5. Market Analysis, Insights and Forecast - by End-User
8.5.1. Government Agencies
8.5.2. Private Sector Organizations
8.5.3. Critical Infrastructure Operators
8.5.4. Healthcare Providers
8.5.5. Financial Institutions
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Ruggedized
9.1.2. Non-Ruggedized
9.2. Market Analysis, Insights and Forecast - by Component
9.2.1. Hardware Components
9.2.2. Software Components
9.2.3. Services
9.3. Market Analysis, Insights and Forecast - by Deployment Type
9.3.1. On-Premises Deployment
9.3.2. Cloud-Based Deployment
9.4. Market Analysis, Insights and Forecast - by Key Technologies
9.4.1. Optical Isolation
9.4.2. Protocol Conversion
9.4.3. Traffic Filtering And Packet Inspection
9.5. Market Analysis, Insights and Forecast - by End-User
9.5.1. Government Agencies
9.5.2. Private Sector Organizations
9.5.3. Critical Infrastructure Operators
9.5.4. Healthcare Providers
9.5.5. Financial Institutions
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Ruggedized
10.1.2. Non-Ruggedized
10.2. Market Analysis, Insights and Forecast - by Component
10.2.1. Hardware Components
10.2.2. Software Components
10.2.3. Services
10.3. Market Analysis, Insights and Forecast - by Deployment Type
10.3.1. On-Premises Deployment
10.3.2. Cloud-Based Deployment
10.4. Market Analysis, Insights and Forecast - by Key Technologies
10.4.1. Optical Isolation
10.4.2. Protocol Conversion
10.4.3. Traffic Filtering And Packet Inspection
10.5. Market Analysis, Insights and Forecast - by End-User
10.5.1. Government Agencies
10.5.2. Private Sector Organizations
10.5.3. Critical Infrastructure Operators
10.5.4. Healthcare Providers
10.5.5. Financial Institutions
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Data Diode Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Data Diode Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Data Diode Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Data Diode Market Revenue (Billion), by Component 2026 & 2034
Figure 5: North America Data Diode Market Revenue Share (%), by Component 2026 & 2034
Figure 6: North America Data Diode Market Revenue (Billion), by Deployment Type 2026 & 2034
Figure 7: North America Data Diode Market Revenue Share (%), by Deployment Type 2026 & 2034
Figure 8: North America Data Diode Market Revenue (Billion), by Key Technologies 2026 & 2034
Figure 9: North America Data Diode Market Revenue Share (%), by Key Technologies 2026 & 2034
Figure 10: North America Data Diode Market Revenue (Billion), by End-User 2026 & 2034
Figure 11: North America Data Diode Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Data Diode Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Data Diode Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Data Diode Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Europe Data Diode Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Data Diode Market Revenue (Billion), by Component 2026 & 2034
Figure 17: Europe Data Diode Market Revenue Share (%), by Component 2026 & 2034
List of Tables
Table 1: Data Diode Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Data Diode Market Revenue Billion Forecast, by Component 2020 & 2034
Table 3: Data Diode Market Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 4: Data Diode Market Revenue Billion Forecast, by Key Technologies 2020 & 2034
Table 5: Data Diode Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 6: Data Diode Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Data Diode Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: North America Data Diode Market Revenue Billion Forecast, by Component 2020 & 2034
Table 9: North America Data Diode Market Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 10: North America Data Diode Market Revenue Billion Forecast, by Key Technologies 2020 & 2034
Table 11: North America Data Diode Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 12: North America Data Diode Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Data Diode Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Data Diode Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Data Diode Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Data Diode Market Revenue Billion Forecast, by Type 2020 & 2034
Europe Data Diode Market Revenue Billion Forecast, by Component 2020 & 2034
Frequently Asked Questions
1. What is the Data Diode Market size in 2026?
The Data Diode Market reached 1.37 Billion in 2026 and is forecast to grow to 2.03 Billion by 2030 at a 10.4% CAGR, driven by rising cyber threats and regulatory mandates.
2. Which region leads the Data Diode Market?
North America leads with approximately 36% share, while Asia-Pacific is the fastest-growing region due to smart grid and industrial digitization investments.
3. Who are the key players in the Data Diode Market?
Leading vendors include Owl Cyber Defense Solutions, Advenica AB, and Forcepoint LLC, along with specialists like Waterfall Security and ST Engineering.
4. What drives Data Diode Market growth?
Rising cyber threats, regulatory compliance mandates (NERC CIP, NIS2), and OT/IT convergence are the primary drivers, while high deployment costs restrain broader adoption.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain—including hardware component manufacturers, specialized data diode producers, system integrators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring granular validation of demand drivers, pricing, and deployment trends.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
30%
Heads of R&D
30%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hardware Component Manufacturers
40%
Specialized Data Diode Producers
30%
System Integrators & Service Providers
20%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies such as IEC, NIST, and ISA. This corroborates market sizing and validates competitive positioning.
Demand Modeling & Market Sizing Triangulation
Our simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) modeling ensures robust triangulation. Historical CAGR and demand elasticity inform multi-year projections.
 Data Diode Market