 AI Filmmaking Market
 Size, CAGR & Industry Outlook 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 274

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 AI Filmmaking Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 1.800 B |
| 2025 | 2.300 B |
| 2026 | 2.800 B |
| 2027 | 3.600 B |
| 2028 | 4.500 B |
| 2029 | 5.600 B |
| 2030 | 7.100 B |

The AI filmmaking market covers software, platforms and services that apply machine learning, computer vision, NLP and generative models across the film value chain — script analysis, pre-visualization, virtual production, editing, VFX, dubbing, and audience analytics — sold to studios, production houses, agencies and independent creators.
This report covers the global AI filmmaking market: production, marketing and distribution, and adjacent creative applications; technologies spanning machine learning, computer vision, NLP, deep learning and generative AI; and deployment across cloud, on-premises and hybrid environments. Revenue tracks software, platform subscriptions and related services sold to film, TV and episodic content creators. This analysis does not cover general-purpose enterprise AI infrastructure, gaming-engine licensing, cinema exhibition hardware, or consumer video-editing apps outside professional filmmaking workflows.
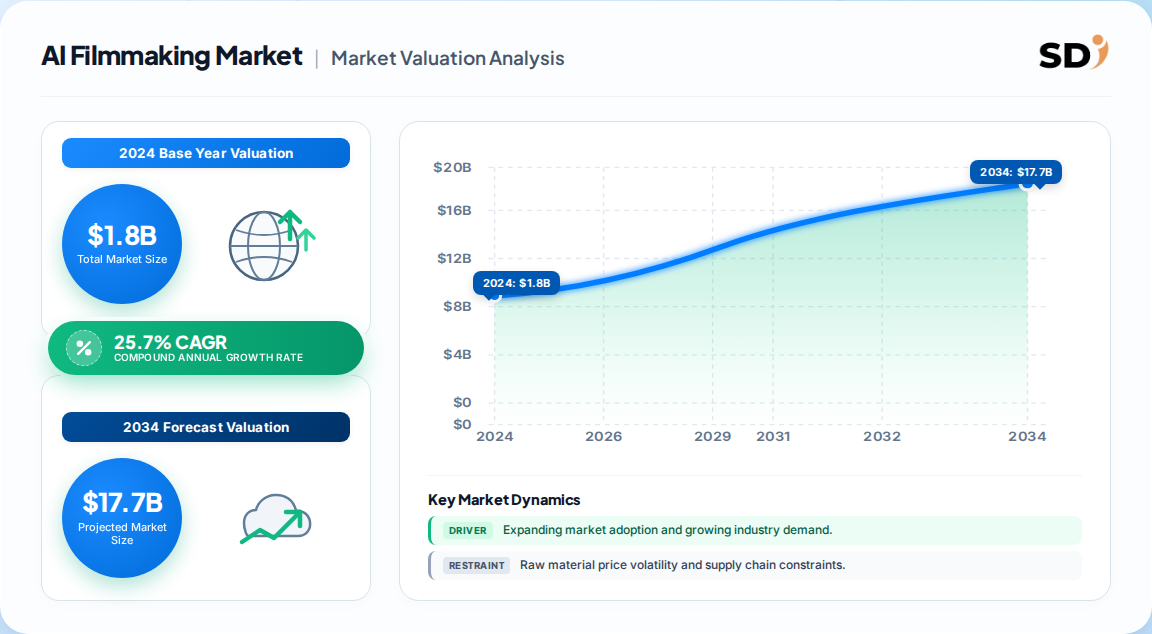
The market is best framed as USD 1.8 billion in 2024, growing to roughly USD 14.1 billion by 2033 at a 25.7% CAGR — but published estimates diverge materially on both base and horizon, so buyers should reconcile scope before committing budgets.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.8B → 14.1B | 2024 | 2033 | 25.7% | AI software & services across film production, marketing and distribution | One published estimate |
| USD 1.97B → 4.6B | 2026 | 2030 | 23.6% | AI in film, narrower scope excluding some adjacent creative tools | A competing analysis |
| Generative AI in movies: USD 359M → 3.857B | 2023 | 2033 | 26.8% | Generative video, character animation and scene creation only | One published estimate |
Our analysis suggests the 14.1 billion by 2033 figure is defensible only if generative video, virtual production and post-production automation are all counted; the narrower 4.6 billion forecast reflects a film-only lens that excludes marketing spend and adjacent content categories. The divergence implies buyers should anchor on the generative-AI sub-segment CAGR (26.8%) rather than the headline figure when modeling near-term tooling spend.
| Year | Market value |
|---|---|
| 2024 | 1.8 Billion |
| 2025 | 2.3 Billion |
| 2026 | 2.8 Billion |
| 2027 | 3.6 Billion |
| 2028 | 4.5 Billion |
| 2029 | 5.6 Billion |
| 2030 | 7.1 Billion |
| 2031 | 8.9 Billion |
| 2032 | 11.2 Billion |
| 2033 | 14.1 Billion |
Segmentation splits by application — production dominates at over 58% — while technology layers stack machine learning, computer vision, NLP, deep learning and generative models, deployed via cloud, on-premises or hybrid models.
| Parent segment | Children |
|---|---|
| By Application | Production, Marketing and Distribution, Others |
| By Technology | Machine Learning, Computer Vision, Natural Language Processing, Deep Learning, Generative AI, Others |
| By Deployment | Cloud, On-Premises, Hybrid |
| By End User | Studios & Major Production Houses, Independent Filmmakers, Advertising & Brand Agencies, Broadcasters & Streamers |
North America leads the global AI filmmaking market with more than 40% share (USD 0.5 billion in 2023), anchored by Hollywood, Silicon Valley AI research and a highly skilled creative-technical workforce.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.24% |
| Asia-Pacific | 0.23% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
Europe follows at roughly 24%, with the UK's VFX ecosystem and EU public-broadcast digitization as the main growth pockets. Asia-Pacific is the fastest-moving region — AI video generation, dubbing and anime pipelines give China, Japan and India outsized near-term upside even if absolute spend trails North America. Our analysis suggests the regional share mix will shift toward Asia-Pacific by 2030 as cloud rendering removes hardware capex barriers.
Cost compression and workflow speed are the dominant drivers; ethical and regulatory friction is the primary restraint. The net effect: adoption accelerates inside studios but slows at the enterprise procurement and IP-clearance layer.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Cost reduction | Driver | High | 85% pre-production planning cost cut; 40% editing-time reduction |
| Streaming platform expansion | Driver | High | 40.3% of total TV usage is streaming (Nielsen, 2024) |
| Predictive analytics | Driver | Medium | Script analysis predicts box-office success at 90% (vendor claim) |
| Personalized content | Opportunity | Medium | AI recommendation engines lift engagement ~20% |
| Ethical & authenticity concerns | Restraint | High | Talent, guild and IP disputes; deepfake liability |
| Data privacy & regulation | Challenge | Medium | Evolving AI rules on IP and likeness rights |
| Tariffs on GPU hardware | Restraint / driver | Medium | Raises on-prem capex; accelerates cloud adoption |
Our analysis suggests the tariff effect is a second-order accelerant: higher GPU import duties push studios toward cloud-based AI pipelines, lowering barriers for mid-tier production houses and shifting revenue to subscription models.
The vendor field spans creative-software incumbents (Adobe, NVIDIA, Autodesk), AI-native platforms (Runway ML, Synthesia, Flawless AI) and analytics specialists (Cinelytic, ScriptBook, Vault AI), each defending a different layer of the production stack.
| Vendor | Primary positioning | Strategic moat |
|---|---|---|
| Adobe | Creative suite with generative AI integration | Installed base and workflow lock-in |
| NVIDIA | GPU and AI infrastructure for virtual production | Hardware and CUDA ecosystem |
| Autodesk (Wonder Dynamics) | AI-driven 3D animation and VFX | Professional pipeline integration (2024 acquisition) |
| Runway ML | Generative video generation | Diffusion model performance and creator adoption |
| Synthesia | AI avatars and synthetic presenters | Enterprise compliance and localization |
| Flawless AI | Automated dubbing and visual translation | Deepfake-grade lip-sync technology |
| Cinelytic | Audience and box-office analytics | Data partnerships and studio workflow fit |
| ScriptBook | Script analysis and success prediction | Proprietary NLP models |
Differentiation is shifting from model quality to pipeline integration and rights-cleared data. Incumbents (Adobe, NVIDIA, Autodesk) win on distribution; AI-native vendors win on capability but face margin pressure as foundational models commoditize. Our analysis suggests consolidation — Autodesk's Wonder Dynamics acquisition is a template — will favor vendors that own both the model and the workflow.
Procurement is now a pipeline decision, not a tooling decision. Buyers should prioritize rights-cleared training data, IP indemnification and guild-compliant contracts — the three areas where AI vendors face the greatest legal exposure and where indemnity gaps create the highest switching costs. Studios integrating generative video into standard workflows should insist on native integration with existing NLE and VFX pipelines (Premiere, Resolve, Nuke, Maya) to avoid re-tooling overhead. Cloud-based deployment is more resilient to hardware tariffs and scales better than on-premises GPU clusters. Regulatory compliance is uneven by jurisdiction: EU AI Act transparency obligations, SAG-AFTRA consent rules and evolving likeness-rights law all affect what a vendor can legally deliver. Buyers should demand audit trails for AI-generated assets and contractual clarity on model-training data provenance. Finally, switching costs rise sharply once a vendor's outputs are embedded in a production pipeline — evaluation should happen before, not after, integration.
The balance of evidence favors a bullish, but segmented, view: the AI filmmaking market is in a sustained adoption phase rather than a speculative spike, with 80% of U.S. film and animation companies integrating AI and 86% of creators using it daily. The most defensible reading is that headline forecasts diverge because of scope, not demand — generative AI video alone grew from USD 359 million in 2023 toward a projected USD 3.857 billion by 2033. The strongest counter-argument is regulatory and labor pushback: guild disputes, likeness lawsuits and EU AI Act compliance could delay studio-scale deployment by 12–24 months and compress near-term revenue for vendors selling into risk-averse buyers.
Our analysis suggests the sharper strategic insight is structural: AI is compressing the cost of pre-production and post-production faster than it is compressing principal photography, which means vendors selling into storyboard, script and edit workflows will capture revenue earlier than those targeting on-set virtual production. The tariff environment further tilts the market toward cloud rendering and software pipelines, advantaging subscription-model vendors over hardware-heavy on-premises competitors.
Evidence that would change our conclusion: a sustained slowdown in studio AI budgets, a major adverse IP ruling against a leading generative-video vendor, or guild agreements that materially restrict AI use in principal photography would push the market toward the lower 4.6 billion by 2030 trajectory rather than the 14.1 billion by 2033 path.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 25.7% from 2020-2034 |
| Segmentation |
|
The market is growing at roughly 25.7% annually through 2033, from USD 1.8 billion in 2024 to USD 14.1 billion. A narrower competing analysis implies a 23.6% CAGR to USD 4.6 billion by 2030, reflecting different scope definitions.
Film production applications dominate with over 58% of 2023 revenue. Within technology, machine learning holds more than 35% share, though generative AI video is the fastest-growing sub-segment at a 26.8% CAGR.
North America holds more than 40% of global revenue, anchored by Hollywood, Silicon Valley AI research and a deep creative-technical workforce. Asia-Pacific is the fastest-growing region, driven by AI video, dubbing and anime pipelines.
Key players include Adobe, NVIDIA, Autodesk (Wonder Dynamics), Runway ML, Synthesia, Flawless AI, MARZ, Cinelytic, ScriptBook and Respeecher, spanning creative software, AI-native video generation and audience analytics.
IP and likeness liability, combined with uneven regulation across jurisdictions, is the biggest procurement risk. Buyers should demand rights-cleared training data, audit trails and contractual indemnification before integrating AI tools into production pipelines.
Published benchmarks report 85% cost reduction in pre-production planning, 70% faster initial script development, 40% faster editing and 45% faster post-production timelines — savings that materially improve margins for studios and independent producers alike.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study is built on a 70/30 primary-to-secondary research split. Our analysts conducted in-depth interviews with decision-makers across the film and media value chain, including creative software platform providers, AI-native video generation startups, VFX and post-production studios, independent production companies, and studio technology procurement teams. Interview targets were designated by role: VP of Production Technology, Head of Post-Production, Chief Technology Officer at mid-tier studios, and Commercial Operations Leads at AI platform vendors. Each session probed adoption barriers, procurement criteria, integration timelines and regulatory exposure.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Production Technology & Operations Leads | 38% |
| Studio Procurement & Sourcing Directors | 27% |
| Creative & Post-Production Heads | 22% |
| Legal, IP & Compliance Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Creative Software & AI Platform Vendors | 40% |
| VFX & Post-Production Studios | 25% |
| Studios & Production Houses | 20% |
| Independent Filmmakers & Creators | 15% |
We triangulated findings against official multilateral and standards sources: UN Comtrade digital-services trade flows, WTO audiovisual services statistics, US ITC filings, Eurostat creative-industry data, SEC 10-K filings and annual investor presentations from listed vendors, patent filings in generative video and computer vision, and recognized industry associations including the Motion Picture Association and the Society of Motion Picture and Television Engineers (SMPTE). These sources anchor market sizing and validate vendor positioning claims.
We apply simultaneous Top-Down and Bottom-Up modeling. The top-down model allocates global media and entertainment software spend by segment and region using macroeconomic and industry segment data. The bottom-up model builds from vendor revenue, seat pricing, production volume and end-use consumption by studio type, then reconciles the two against historical CAGR and demand elasticity.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |