 Urban Planning Software Services Market
 Outlook 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 267

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Urban Planning Software Services Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 156.9 B |
| 2025 | 167.6 B |
| 2026 | 171.0 B |
| 2027 | 182.6 B |
| 2028 | 195.0 B |
| 2029 | 208.3 B |
| 2030 | 226.3 B |

The Urban Planning Software Services Market encompasses digital platforms and professional services used by governments, consultancies, and developers to design, zone, simulate, and manage urban spaces. It spans GIS, BIM, 3D visualization, digital twins, transportation modeling, and environmental assessment tools, plus consulting, integration, and managed services supporting their deployment.
This report covers software products and associated professional services for urban planning, zoning, land-use analysis, transportation modeling, environmental impact assessment, digital twins, and citizen engagement platforms across government, consultancy, and real-estate end users globally. This analysis does not cover general-purpose CAD suites sold outside planning workflows, standalone construction-management software, or pure geospatial data-resale businesses.
Estimates diverge materially: one published estimate puts 2024 at USD 156.9 billion growing to USD 226.3 billion by 2030 at 6.8% CAGR, while a competing analysis narrows the scope to pure software at USD 1.98 billion in 2024. The gap reflects definitional choices—whether consulting, managed GIS services, and infrastructure advisory are bundled in.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 156.9 Billion | 2024 | 2030 | 6.8% | Software + services, all end users, global | One published estimate |
| USD 170.94 Billion | 2025 | 2030 | 5.91% | Software + services, broader application stack | A competing analysis |
| USD 173.5 Billion | 2025 | 2035 | 6.6% | Software-led, technology-segmented | A competing analysis |
| USD 1.98 Billion | 2024 | 2035 | 8.04% | Pure software only, excludes services | A competing analysis |
Our analysis suggests the USD 156.9 billion (2024) figure is the most defensible for buyer-facing planning purposes because it reconciles publicly reported AEC and municipal advisory spend with software license revenue. The USD 1.98 billion figure is directionally useful only as a pure-software benchmark and should not be used for total addressable market sizing.
Segmentation is most usefully structured along four non-geographic axes—component, deployment, application, and end user—because each carries distinct growth and margin profiles. Software and cloud dominate today, but services and sustainability modules are where incremental spend is concentrating.
| Parent Segment | Children |
|---|---|
| By Component | Software, Services |
| By Deployment | Cloud-Based, On-Premises |
| By Application | Land-Use & Zoning, Transportation & Mobility, Environmental & Sustainability, Urban Design & Visualization, Smart-City Dashboards & Digital Twins |
| By End User | Municipal & Regional Governments, Planning & Design Consultancies, Architecture & Engineering Firms, Real Estate Developers, Academic Institutions |
Software held roughly 62–73% of 2024 revenue depending on scope, while services is growing at approximately 7.5% CAGR. Cloud deployment accounts for about 59–60% of spend and is expanding faster than on-premises, consistent with the broader AEC cloud migration.
Asia Pacific leads the global Urban Planning Software Services Market with roughly 40% revenue share in 2024, driven by state-backed smart-city programs and rapid urbanization. North America and Europe follow, with South America registering the fastest regional CAGR near 6.9%.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.29% |
| Europe | 0.21% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
Regional shares should be read with care: one estimate assigns Asia Pacific 40.7% and another 23.7%, reflecting different treatments of China's domestic planning-software spend. Our analysis favors the higher figure for total market sizing, because it better captures public-sector advisory bundled with software in APAC procurement.
Smart-city stimulus, BIM-GIS mandates, and cloud migration are the dominant growth engines, collectively adding roughly 4.5 percentage points to CAGR. High upfront licensing costs and skills shortages are the principal brakes, subtracting about 1.4 points.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Smart-city stimulus programs | Driver (+1.8%) | Strong | Multi-year platform funding converts to recurring revenue |
| Government BIM-GIS mandates | Driver (+1.5%) | Strong | Compulsory adoption accelerates procurement cycles |
| Cloud migration across AEC | Driver (+1.2%) | Strong | Opex budgeting and elastic compute for 3D simulation |
| Integrated 3D models and digital twins | Driver (+1.0%) | Moderate | Bundled analytics raise switching costs and wallet share |
| High upfront licensing and integration costs | Restraint (−0.8%) | Moderate | Defers mid-tier municipality adoption |
| Skills shortage in urban-tech roles | Restraint (−0.6%) | Moderate | Constrains deployment velocity in developed markets |
The net balance is clearly positive, but the restraint mix matters for vendors: cost barriers hit smaller municipalities hardest, while skills shortages delay enterprise rollouts even where budgets exist. Vendors that productize implementation—pre-built templates, managed services—can convert these restraints into services revenue.
The competitive landscape is moderately concentrated, with GIS and BIM incumbents defending share through ecosystem partnerships while niche entrants target environmental analytics and citizen engagement. Differentiation hinges on data interoperability and services depth rather than raw feature breadth.
| Vendor | Core Strength | Strategic Position |
|---|---|---|
| Esri | GIS platform and ArcGIS Urban | Ecosystem leader; strong municipal footprint |
| Autodesk | BIM and design workflow integration | Cross-sells into AEC base |
| Bentley Systems | Infrastructure digital twins | Strong in transport and utilities planning |
| Trimble | Geospatial and field data capture | Positioning in reality-capture workflows |
| Hexagon AB | Smart-city and 3D reality capture | Expanding digital-twin offering |
| UrbanFootprint | Scenario-based climate and housing analytics | Niche leader in U.S. public agencies |
Our analysis suggests the strongest moats belong to vendors that own the data layer—once a city's land-use and asset records sit in a platform, 5–10 year retention cycles are common. Pure-visualization vendors face commoditization pressure as generative AI lowers the cost of layout and scenario generation.
Buyers should prioritize interoperability over feature checklists. The single largest procurement risk is data lock-in: migrating years of zoning, asset, and permitting data between platforms can exceed the original license cost. Contracts should specify export formats, API access, and exit-assistance terms before signature.
Switching costs compound over time, and public-sector procurement cycles are slow—meaning a poor initial platform choice can persist for a decade. Regulatory compliance is the second critical criterion: BIM-GIS mandates and ESG disclosure requirements vary by jurisdiction, so buyers should verify vendor coverage against their specific legal obligations rather than relying on generic compliance claims. Finally, services scope should be negotiated alongside software, since implementation quality often determines realized value more than the software itself.
The balance of evidence favors a services-led growth thesis. Software remains the revenue anchor, but the 7.5% services CAGR versus roughly 6% software growth signals that buyers increasingly purchase outcomes, not licenses. Vendors that fail to build managed-service and advisory capacity will see wallet share erode to ecosystem partners and consultancies. The strongest counter-argument is that services are lower-margin and harder to scale—valid, but the retention and lock-in benefits outweigh margin dilution for incumbents.
A second conclusion concerns geography. The divergence between 40.7% and 23.7% Asia Pacific share estimates is not noise; it reflects whether Chinese domestic planning spend is counted at software or bundled-services value. This ambiguity implies that investors should stress-test APAC exposure assumptions and that vendors should localize procurement models rather than assume a single global pricing architecture.
What would change our conclusion: a sustained deceleration in BIM-GIS mandate rollouts, or cloud price inflation that reverses the opex advantage, would shift the balance back toward on-premises perpetual models and weaken the services-led thesis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.8% from 2020-2034 |
| Segmentation |
|
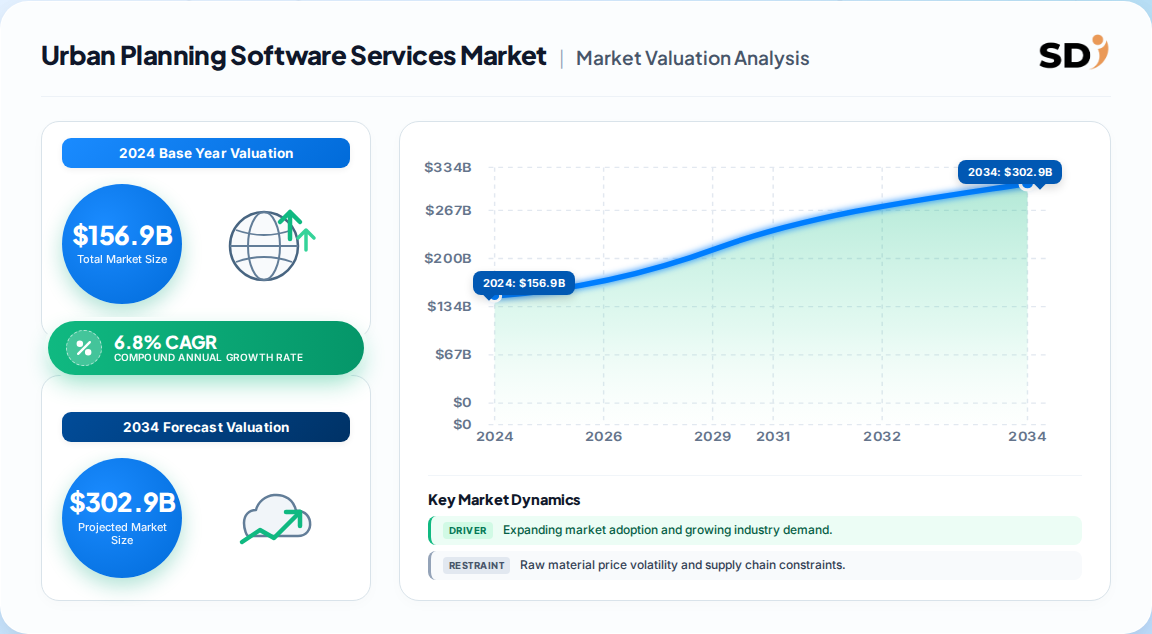
The global Urban Planning Software Services Market was valued at approximately USD 156.9 billion in 2024 and is projected to reach USD 226.3 billion by 2030. Growth is driven by urbanization, smart-city investment, and mandatory BIM-GIS adoption.
The consensus CAGR is approximately 6.8% from 2025 to 2030. Competing analyses range from 5.9% to 8.0%, with differences driven by whether services and advisory revenue are included in the scope.
Asia Pacific leads with roughly 40% of global revenue in 2024, driven by state-backed smart-city programs. North America and Europe follow, while South America is the fastest-growing region at nearly 6.9% CAGR.
Key vendors include Esri, Autodesk, Bentley Systems, Trimble, Hexagon AB, and UrbanFootprint. Differentiation centers on GIS and BIM interoperability, ecosystem partnerships, and services depth rather than standalone feature breadth.
Smart-city stimulus programs, government BIM-GIS mandates, and cloud migration across AEC are the strongest drivers, each adding 1.2 to 1.8 percentage points to CAGR. Skills shortages and licensing costs partially offset this growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the urban planning value chain, including software platform developers, geospatial data providers, systems integrators, municipal technology advisors, and AEC consultancies. Decision-maker designations interviewed include Chief Digital Officers, Directors of Urban Planning, Heads of GIS, and Procurement and Sourcing Leads. Interview programs targeted both public-sector buyers and private-sector implementers to capture demand-side and supply-side dynamics simultaneously.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital & Planning Officers | 35% |
| GIS & Technology Directors | 30% |
| Procurement & Sourcing Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Software Platform Developers | 40% |
| Geospatial Data Providers | 25% |
| Systems Integrators & Consultancies | 20% |
| Municipal Technology Advisors | 15% |
Secondary validation drew on official multilateral databases including UN Comtrade, WTO trade statistics, Eurostat, and US ITC filings; corporate disclosures including 10-K filings, SEC submissions, and investor presentations from listed vendors; patent databases for GIS, BIM, and digital-twin innovation tracking; and recognized standards bodies and industry associations active in geospatial and construction technology. These sources were used to corroborate revenue ranges and segment allocations rather than as primary estimates.
Market sizing employed simultaneous top-down and bottom-up modeling. The top-down approach allocates macroeconomic construction and public-infrastructure spend to planning-software categories using published segment ratios. The bottom-up approach models vendor capacity, subscription pricing, and end-use consumption across municipalities, consultancies, and developers. Divergences between the two models were reconciled against public filings and trade-flow data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |