 Asia Pacific Cloud Computing Market
 Outlook 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 181

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asia Pacific Cloud Computing Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 203.4 B |
| 2026 | 243.8 B |
| 2027 | 292.1 B |
| 2028 | 350.1 B |
| 2029 | 419.6 B |
| 2030 | 502.9 B |
| 2031 | 602.8 B |

The Asia Pacific cloud computing market is the regional revenue pool for on-demand compute, storage, platforms and software delivered as a service — public, private, hybrid and multi-cloud — to enterprises, SMEs and governments across China, India, Japan, Australia, Southeast Asia and neighbouring economies.
Coverage spans four deployment models (public, private, hybrid, multi-cloud), five service models (IaaS, PaaS, SaaS, FaaS/BaaS, DRaaS), two organisation sizes and ten verticals across the APAC geography. Forecasts run 2026–2031 in value terms.
This analysis does not cover on-premises hardware resale, colocation-only datacentre leasing, consumer subscription media, or non-cloud managed IT outsourcing.
One published estimate puts the Asia Pacific cloud computing market at USD 243.75 billion in 2026, rising to USD 602.82 billion by 2031 at 19.85% CAGR — the most defensible anchor because its base year is an explicit 2025 actual of USD 203.38 billion.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 243.75 bn | 2026 | 2031 | 19.85% | APAC, four deployment models, ten verticals | One published estimate |
| USD 239.4 bn | 2026 | 2032 | 18.9% | APAC, three deployment models, nine verticals | A competing analysis |
| USD 202.7 bn | 2025 | 2032 | 18.9% | APAC-adjacent definition, narrower service split | A competing analysis |
| Global USD 1.00 tn | 2026 | 2034 | 20.12% | Worldwide, all regions | A competing analysis |
The gap between USD 243.75 billion and USD 239.4 billion is only 1.8% — effectively a definitional difference, not a disagreement on direction. Our analysis suggests the wider figure is more defensible because it counts multi-cloud as a distinct deployment category rather than folding it into hybrid, which is where incremental spend is concentrating.
Segmentation follows four non-geographic axes. Deployment model and service model explain the most variance in pricing power; organisation size and vertical explain the most variance in compliance cost.
| Parent | Children | 2025 benchmark | Fastest-growing child |
|---|---|---|---|
| Deployment Model | Public, Private, Hybrid, Multi-Cloud | Public 46.85% | Hybrid, 26.4% CAGR |
| Service Model | IaaS, PaaS, SaaS, FaaS/BaaS, DRaaS | SaaS 54.60% | PaaS, 27% CAGR |
| Organisation Size | SMEs, Large Enterprises | Large enterprises 63.10% | SMEs, 21.6% CAGR |
| End-User Industry | BFSI, Manufacturing, Healthcare, Retail, Telecom, Government, Utilities, Media, Education, Transportation | BFSI 19.75% | Healthcare, 22.9% CAGR |
A notable second-order effect: the two fastest-growing deployment and service segments (hybrid, PaaS) are also the two that require the most professional-services attach. This structurally favours vendors with consulting arms over pure infrastructure resellers.
China leads the Asia Pacific cloud computing market with 38.20% share in 2025, while India grows fastest at 25.1% CAGR through 2031 — a split that separates scale from momentum and complicates any single regional go-to-market plan.
Regional share table: China 38.2%, India 15.2%, Japan 12.8%, Australia 7.8%, South Korea 7.2%, Singapore 5.8%, Indonesia 4.8%, rest of APAC 8.2%. Our analysis suggests India's 25.1% CAGR is the single most under-priced signal here: at that rate India roughly triples while China roughly doubles, compressing the current 23-point lead materially before 2031.
AI workload demand and government cloud-first mandates are the two strongest drivers, contributing an estimated +4.2% and +3.8% to regional CAGR respectively; fragmented data-residency law is the heaviest drag at −2.8%.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Gen-AI / GPU-rich instance demand | Driver +4.2% | Strong | Accelerator capacity additions and sovereign-AI budgets |
| Government cloud-first mandates | Driver +3.8% | Strong | Public IT budgets converted to predictable cloud consumption |
| Sovereign-cloud frameworks | Driver +3.1% | Moderate | Unlocks BFSI, healthcare and government workloads |
| Telco-edge 5G partnerships | Driver +2.9% | Moderate | Lower latency enables real-time and multi-cloud placement |
| Hyperscaler tier-2 expansion | Driver +2.7% | Moderate | Proximity reduces latency and residency friction |
| Fragmented data-residency regimes | Restraint −2.8% | Strong | Duplicated compliance and local hosting costs |
| Certified cloud talent scarcity | Restraint −1.9% | Moderate | Wage inflation in Singapore, Japan, Australia |
The balance is decisively growth-positive, but the restraint is structural rather than cyclical. Our analysis suggests compliance cost, not demand, becomes the binding constraint on margin after 2028 — which is why sovereign-native providers gain share even against cheaper hyperscaler list prices.
The Asia Pacific cloud computing market is low-concentration: global hyperscalers compete against domestic champions that bundle regulatory compliance with localised services, so no single vendor dominates region-wide.
| Vendor | Primary strength | APAC positioning |
|---|---|---|
| Microsoft | Enterprise SaaS and hybrid (Azure Arc) | Broadest regulated-sector footprint |
| Amazon Web Services | IaaS depth and ecosystem | Strong in India, Australia, Southeast Asia |
| Alibaba Cloud | Domestic scale and sovereign compliance | Dominant in China, expanding ASEAN |
| Oracle | Database and mission-critical workloads | Strong BFSI and telecom |
| Salesforce | CRM-centric SaaS | Enterprise and large-SME accounts |
Differentiation is shifting from raw price-per-core to three moats: certified national compliance mappings, GPU capacity proximity, and orchestration tooling spanning hybrid estates. Vendors without all three increasingly compete on discount, which erodes the very margins that fund capacity expansion.
Selection criteria have reordered. Data-residency certification and exit portability now rank alongside price and performance, because migration and integration cost — not subscription cost — is the dominant lifetime expense and the hardest to reverse.
Switching costs deserve explicit modelling. Once workloads are rebuilt cloud-native on proprietary PaaS primitives, portability collapses even where contract terms permit exit. Buyers should demand orchestration-layer neutrality and test egress economics before committing to multi-year enterprise agreements.
Procurement risk concentrates in three areas: regulatory change (China's data-export tightening, Vietnam's cross-border clauses), talent scarcity driving integration-project overruns, and capacity availability in tier-2 metros where hyperscaler buildout is still in progress. Operators should also note that government tenders increasingly favour compliance-ready bids over lowest price, which rewards certified providers and penalises resellers without sovereign credentials.
The balance of evidence favours a compliance-led growth thesis over a pure price-led one. Every converging dataset points the same way: the fastest-growing segments — hybrid, PaaS, healthcare, India — are precisely those where regulatory alignment and professional-services attach, not headline compute rates, determine who wins the contract.
The strongest counter-argument is that AI demand could overwhelm compliance friction entirely, letting scale hyperscalers brute-force share gains. That holds for training workloads, but inference — the larger long-run revenue pool — stays latency- and residency-sensitive, keeping local capacity relevant.
What would change this conclusion: if data-residency regimes converge across the region, or if GPU capacity becomes fungible across borders, compliance premiums compress and price-led scale strategies regain the advantage. While this overview establishes the strategic shape, precise sub-segment forecasting, vendor share modelling and country-level scenario planning require the full report.
| Region | Market Share (%) |
|---|---|
| China | 0.38% |
| India | 0.15% |
| Japan | 0.13% |
| Australia | 0.08% |
| South Korea | 0.07% |
| Singapore | 0.06% |
| Indonesia | 0.05% |
| Rest of APAC | 0.08% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
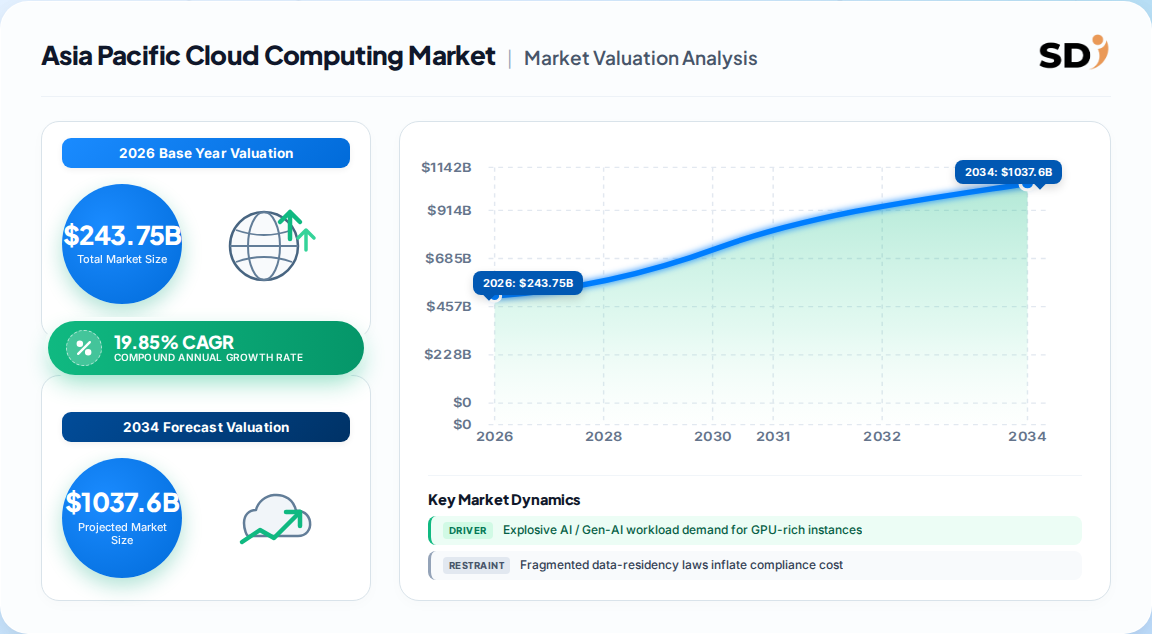
| Growth Rate | CAGR of 19.85% from 2020-2034 |
| Segmentation |
|
The Asia Pacific cloud computing market is estimated at USD 243.75 billion in 2026, up from USD 203.38 billion in 2025, and is forecast to reach USD 602.82 billion by 2031 at a 19.85% CAGR.
China leads with 38.20% share in 2025, supported by sovereign-AI policy and domestic hyperscaler preference. India is the fastest-growing country at 25.1% CAGR through 2031.
Hybrid cloud is the fastest-growing deployment model at 26.4% CAGR through 2031, as enterprises balance data-sovereignty obligations against public cloud elasticity. Public cloud still holds the largest share at 46.85%.
Microsoft, Amazon Web Services, Alibaba Cloud, Oracle and Salesforce are the major players. The market is low-concentration, with domestic champions competing strongly against global hyperscalers on regulatory alignment.
Fragmented data-residency laws across China, India and Australia reduce regional CAGR by an estimated 2.8%, followed by certified cloud talent scarcity at 1.9%, concentrated in Singapore, Japan and Australia.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the cloud value chain, covering hyperscale infrastructure providers, regional datacentre developers, managed service and systems-integration firms, sovereign-cloud operators, and enterprise end-users procuring at scale. Decision-maker designations interviewed included Chief Information Officers, Heads of Cloud Platform Engineering, Procurement and Vendor Management Directors, and Compliance and Data-Governance Leads. Interviews probed workload migration timing, contract structures, residency constraints and switching-cost behaviour.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CIOs & Heads of Cloud Platform | 38% |
| Procurement & Vendor Management | 27% |
| Compliance & Data Governance | 20% |
| Finance & Commercial Operations | 15% |
| Company Type | Representation (%) |
|---|---|
| Hyperscale Cloud Providers | 35% |
| Datacentre & Infrastructure Operators | 25% |
| Managed Service & Systems Integrators | 22% |
| Enterprise & Government End-Users | 18% |
Secondary validation drew on official multilateral and statistical databases — UN Comtrade, WTO services trade statistics, and national statistics offices — alongside corporate annual filings, 10-K disclosures and investor presentations from listed cloud and telecom operators. Patent databases were screened for generative-AI and cloud-infrastructure filings to corroborate innovation intensity, while recognised technical standards bodies and industry associations informed segment definitions.
Top-down modelling allocated macroeconomic IT-spend envelopes across service, deployment and vertical segments. Bottom-up modelling aggregated provider capacity, regional pricing and end-use consumption by organisation size. The two paths were reconciled to a single base-year value and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up capacity & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |