 Us Private 5g Network Market
US Private 5G Network Market Size, Share & Forecast 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 219

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Private 5g Network Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
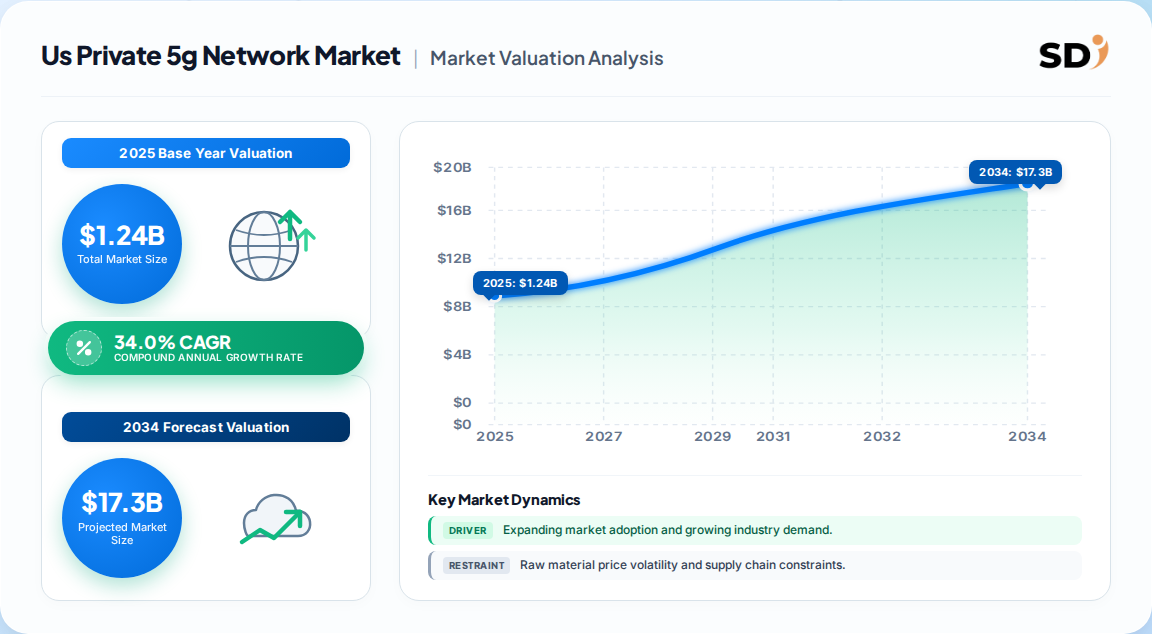
| 2025 | 1.240 B |
| 2026 | 1.670 B |
| 2027 | 2.230 B |
| 2028 | 2.990 B |
| 2029 | 4.010 B |
| 2030 | 5.370 B |
| 2031 | 7.200 B |

The US private 5G network market comprises dedicated wireless infrastructure—radio access, core, and edge compute—deployed by enterprises, ports, utilities, and campuses to achieve secure, low-latency, high-density connectivity independent of public carrier networks. It spans hardware, software, and managed services across licensed, unlicensed, and shared spectrum bands.
This analysis covers the US private 5G network market across component (hardware, software, services), operational frequency (Sub-6 GHz, mmWave), spectrum (licensed, unlicensed/shared), enterprise size, and vertical. It includes on-premise and cloud deployment models.
This analysis does not cover public 5G network operator services, consumer mobile broadband, Wi-Fi 6/7 enterprise networking, or satellite-based private networks, except where they directly compete with or complement private 5G deployments.
Published estimates for the US market diverge sharply due to differences in scope and methodology, ranging from a 6.82 Billion global figure implying roughly 2.2 Billion for the US in 2026 to a 27.94 Billion US-specific forecast by 2034. The table below compares the most credible estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 27.94 Billion | 2024 | 2034 | 34.0% | US-specific, hardware/software/services, all verticals | One published analysis |
| 50.28 Billion (North America) | 2025 | 2033 | 59.8% | North America incl. Canada/Mexico, component focus | A competing analysis |
| 25.25 Billion (Global) | 2026 | 2031 | 42.15% | Global 5G private network, hardware-led | A third published estimate |
| 120.76 Billion (Global) | 2026 | 2034 | 43.23% | Global private 5G, cloud and SME emphasis | An alternative forecast |
Our analysis suggests the 27.94 Billion by 2034 US-specific forecast is the most defensible for US buyers because it isolates the national market, incorporates the 2024 hardware dominance baseline, and aligns with the observed 1.24 Billion 2025 revenue figure. The higher global forecasts, while directionally consistent, embed emerging-market growth that does not directly translate to US procurement decisions.
The US private 5G network market is segmented by component, operational frequency, spectrum type, enterprise size, and vertical. Hardware remains the largest current revenue pool, but services and software are the fastest-growing segments as managed and as-a-service models gain traction.
| Parent Segment | Children |
|---|---|
| Component | Hardware (RAN, Core Network, Backhaul & Transport, Interconnect), Software & Services (Installation & Integration, Data Services, Support & Maintenance) |
| Operational Frequency | Sub-6 GHz, mmWave |
| Spectrum | Licensed, Unlicensed/Shared |
| Enterprise Size | Small & Medium Enterprises, Large Enterprises |
| Vertical | Manufacturing, Energy & Utilities, Transportation & Logistics, Aerospace & Defense, Government & Public Safety, Corporates/Enterprises, Mining, Healthcare, Oil & Gas, Others |
The South leads US private 5G network deployments, driven by manufacturing clusters in Texas and the Southeast, port logistics in Louisiana and Florida, and energy-sector investments. The Northeast follows closely with healthcare and defense applications, while the Midwest and West contribute through automotive, agriculture, and technology campuses.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| South | 0.34% |
| Midwest | 0.21% |
| West | 0.21% |
Our analysis indicates that the South's lead is structural, not cyclical: lower spectrum licensing friction in CBRS-heavy deployments, state-level incentives for industrial digitalization, and the concentration of 5G IIoT module suppliers in Texas create a self-reinforcing adoption ecosystem.
The primary growth driver is the liberalization of shared spectrum (CBRS) and the falling cost of 5G industrial modules, which together lower the total cost of ownership for mid-tier enterprises. The main restraint is the shortage of multi-band certified devices and a systems-integration skill gap, which inflate deployment risk and delay ROI realization.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| CBRS and local-licence liberalization | Driver | High | Lowers spectrum acquisition cost and complexity |
| Falling 5G IIoT module and small-cell prices | Driver | High | Reduces capex by double-digit percentages |
| Mature 5G SA core with SASE integration | Driver | Medium | Cuts integration time for multi-site deployments |
| Edge-native NaaS from hyperscalers | Driver | Medium | Shifts capex to opex, enables pay-per-use |
| Scarcity of multi-band certified devices | Restraint | Medium | Forces hybrid designs, raises support costs |
| Systems-integration skill gap | Restraint | Medium | Delays rollout at mid-tier partners |
| High initial infrastructure costs | Restraint | High | Limits SME adoption |
| Complex spectrum licensing | Restraint | Medium | Varies by state and band, delays implementation |
The balance of evidence favors accelerating adoption through 2028, as spectrum and hardware tailwinds outweigh integration headwinds. However, the device certification gap is the most underappreciated risk: it disproportionately affects healthcare and defense, the two verticals with the highest revenue per deployment.
The US private 5G network vendor landscape is led by network equipment providers (Ericsson, Nokia, Samsung) that supply RAN and core infrastructure, carriers (AT&T, Verizon, T-Mobile) that bundle spectrum and managed services, and hyperscalers (AWS, Microsoft Azure) that integrate edge compute with 5G cores. Specialist players like Federated Wireless and Betacom provide CBRS expertise and turnkey deployment.
| Vendor | Category | Key Differentiator |
|---|---|---|
| Ericsson | Network equipment | 5G SA core, Google Cloud partnership |
| Nokia | Network equipment | End-to-end private wireless, industrial focus |
| Samsung | Network equipment | Compact macro and small-cell portfolio |
| AT&T | Carrier | Spectrum assets, managed services |
| Verizon | Carrier | Private 5G edge, NVIDIA AI integration |
| AWS | Hyperscaler | Private 5G-as-a-service, edge compute |
| Microsoft Azure | Hyperscaler | Azure Private 5G, on-prem core |
| Federated Wireless | Specialist | CBRS SAS, shared spectrum expertise |
Differentiation is shifting from radio performance to ecosystem integration: vendors that can bundle spectrum access, edge compute, and vertical applications—rather than selling discrete hardware—are capturing disproportionate share of new deployments. The strongest competitive moats belong to carriers with licensed spectrum and hyperscalers with existing enterprise cloud relationships.
Buyers should prioritize spectrum strategy first: CBRS-based deployments offer faster time-to-value and lower cost, but licensed spectrum provides deterministic performance for mission-critical operations. Procurement risk is highest in device certification—verify that ruggedized devices, cameras, and AR headsets are certified across both Sub-6 GHz and mmWave bands before committing to a hybrid design.
Switching costs are significant once a core network and RAN are deployed, so buyers should negotiate multi-year service-level agreements that include upgrade paths to 5G-Advanced and clear data-sovereignty terms. Regulatory compliance varies by state and vertical; healthcare deployments require additional FDA and HIPAA alignment, while defense and public-safety deployments face FedRAMP and secure-supply-chain requirements. Operators should also model total cost of ownership over five years, not just capex, because integration and maintenance services typically account for 40–50% of lifetime spend.
The balance of evidence favors aggressive US market entry and expansion through 2028, driven by CBRS spectrum availability, falling hardware costs, and hyperscaler-led NaaS models. The strongest counter-argument is that device certification bottlenecks and integration skill gaps could cap growth at the low end of forecasts, particularly for SMEs and healthcare providers that lack in-house telecom expertise. We judge this risk as manageable but underappreciated by vendors that focus solely on radio performance.
Our analysis suggests the most durable competitive position belongs to vendors that combine spectrum access, edge compute, and vertical-specific applications into a single managed offering. Pure hardware vendors face margin compression as 5G IIoT modules commoditize; pure software vendors lack the network integration depth to win large deployments. The winning model is a co-opetition ecosystem: carriers provide spectrum and coverage, hyperscalers provide edge and cloud, and specialists provide CBRS and vertical customization.
Actionable Strategy:
The evidence that would change our conclusion: a sustained reversal in CBRS spectrum liberalization, or a major device-certification breakthrough by a single vendor that collapses the integration-skill barrier. Absent either, the US market remains on a 34%+ CAGR trajectory through 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 34.0% from 2020-2034 |
| Segmentation |
|
The US private 5G network market was valued at approximately 1.24 Billion in 2025 and is projected to reach 27.94 Billion by 2034, according to published estimates. This represents a 34.0% compound annual growth rate from 2026 to 2034.
Growth is driven by CBRS spectrum liberalization, falling 5G industrial IoT module prices, mature 5G standalone core availability with SASE integration, and edge-native network-as-a-service offerings from hyperscalers that lower the barrier for mid-tier enterprises.
Manufacturing leads with 32.35% of global private 5G revenue in 2025, followed by energy and utilities, transportation and logistics, and defense. Healthcare is the fastest-growing US vertical at a 49.2% CAGR through 2034.
Key vendors include Ericsson, Nokia, Samsung, AT&T, Verizon, T-Mobile, AWS, Microsoft Azure, Federated Wireless, and Betacom. Competition is shifting from radio hardware to integrated managed services combining spectrum, edge compute, and vertical applications.
US private 5G deployments use Sub-6 GHz and mmWave frequencies across licensed, unlicensed, and shared spectrum. CBRS shared spectrum held 73.63% share in 2024 due to deployment flexibility, while mmWave is growing fastest for high-bandwidth, low-latency use cases.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the private 5G value chain, including network equipment vendors, mobile network operators, hyperscaler edge-compute providers, systems integrators, and enterprise end-users in manufacturing, healthcare, and logistics. Decision-makers interviewed included VP-level Sourcing and Procurement Leads, Heads of Network Engineering, Technical Directors of Operational Technology, and Commercial Operations Leads responsible for private wireless deployment.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Network Engineering & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Operational Technology Heads | 30% |
| Company Type | Representation (%) |
|---|---|
| Network Equipment Vendors | 35% |
| Mobile Carriers & Operators | 25% |
| Hyperscalers & Edge Providers | 20% |
| Systems Integrators & Specialists | 20% |
We triangulate primary findings against official multilateral databases including US ITC trade statistics, FCC spectrum licensing records, NTIA CBRS device activation data, and corporate filings (10-K, SEC disclosures, investor presentations). Patent databases and standards bodies—including 3GPP, IEEE, and the Alliance for Telecommunications Industry Solutions (ATIS)—provided technical validation for frequency and deployment claims. Non-profit industry associations such as the CBRS Alliance and the 5G Americas trade group supplied adoption benchmarks.
We apply simultaneous top-down and bottom-up modeling. Top-down, we allocate macroeconomic enterprise connectivity spend across verticals and regions using US Census and BLS segment data. Bottom-up, we model manufacturer capacity, 5G IIoT module pricing, small-cell shipment volumes, and end-use consumption by vertical to derive revenue pools. These two approaches are reconciled through iterative triangulation to produce a consensus base-year value and forecast trajectory.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up vendor revenue and shipment triangulation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | State-level and Census-region share | FCC licensing data, trade flow analysis, consumption modeling | High |
| Competitive Landscape | Leading vendors and specialists | Annual reports, capacity mapping, commercial filings | High |