 Case Management Software Market
 2026: Size, CAGR & Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 278

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Case Management Software Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 9.100 B |
| 2026 | 10.30 B |
| 2027 | 11.70 B |
| 2028 | 13.30 B |
| 2029 | 15.00 B |
| 2030 | 17.10 B |
| 2031 | 19.30 B |

The case management software market encompasses platforms that centralize, automate, and track case-related data, documents, workflows, deadlines, and communications for legal, healthcare, government, insurance, and social-service organizations. These systems replace manual, paper-based processes with auditable digital workflows, enabling compliance, transparency, and cross-department collaboration at scale.
This analysis covers global case management software across component (solution, services), deployment (cloud, on-premise), enterprise size (SMEs, large enterprises), and end-use verticals including telecom/IT, healthcare, government, legal, insurance, and social services. Figures are revenue-based, in nominal USD, for the 2025 base year and forecast to 2033. This analysis does not cover standalone legal billing, eDiscovery, or general-purpose CRM/workflow tools except where bundled into case management suites, nor does it cover professional services revenue outside software delivery.
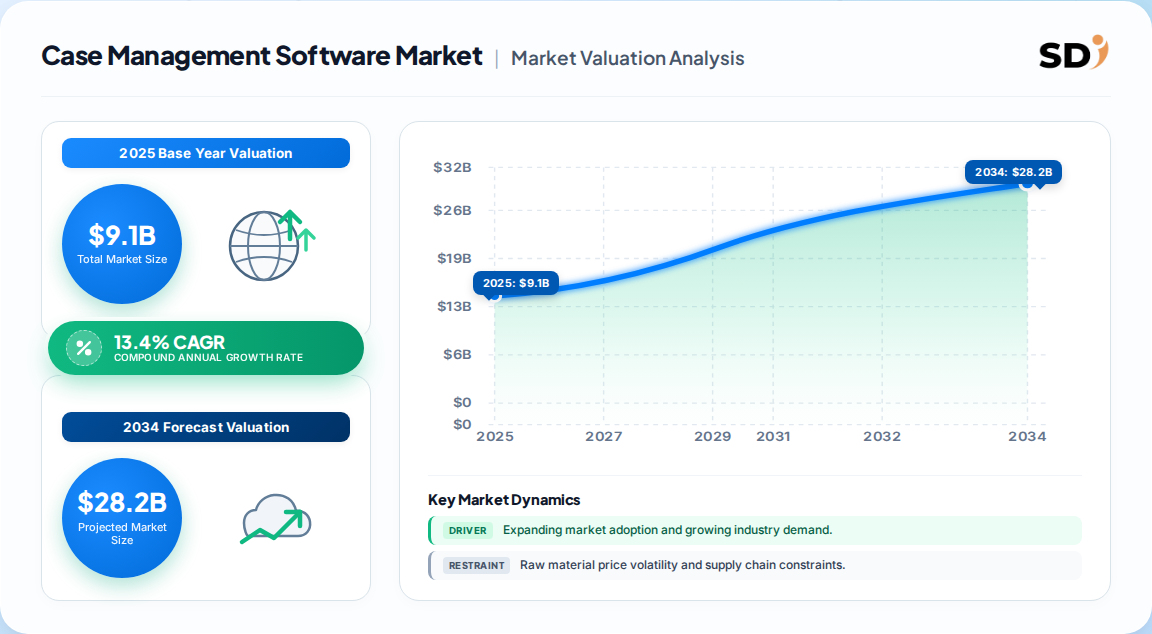
The most defensible base-year figure is USD 9.1 billion (2025), aligning with a 13.4% CAGR to USD 24.2 billion by 2033. Competing estimates diverge mainly because of scope (legal-only vs. cross-industry) and definitional treatment of services revenue.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 9.1B → 24.2B | 2025 | 2033 | 13.4% | All-industry, solution + services | Published market estimate (aggregated secondary source) |
| USD 2.37B → 4.48B | 2023 | 2030 | 9.89% | North America only | Trade-press summary of a research report |
| USD 5.9B (by 2033) | 2024 | 2033 | 13.4% | Legal case management only | Published market estimate (aggregated secondary source) |
Our analysis suggests the USD 9.1B figure is the most defensible global benchmark because it counts all-industry adoption, including government and healthcare, which now outpace legal in growth. The legal-only USD 5.9B estimate is consistent as a subset once vertical scope is adjusted. The North America figure reflects a smaller regional slice and a different horizon, not a contradiction.
Segmentation is defined primarily by component, deployment, enterprise size, and end-use vertical. Solutions dominate revenue, but services are the fastest-growing component as AI implementation and integration demand rises.
| Parent | Children |
|---|---|
| Component | Solution, Services |
| Deployment | Cloud, On-premise |
| Enterprise Size | SMEs, Large Enterprises |
| End Use | Telecom & IT, Healthcare, Government, Legal, Insurance, Social Services, BFSI, Retail, Other |
Cloud holds roughly 60% share and continues to displace on-premise. Large enterprises represent 55%+ of revenue, but SMEs are adopting faster. This matters for buyers: pricing, integration depth, and compliance certifications differ sharply across tiers.
North America leads with 40% of 2025 revenue, underpinned by advanced digital infrastructure and leading vendor concentration. The U.S. alone commands roughly 80% of the North American market, per trade-press benchmarks.
| Region | Market Share (%) |
|---|---|
| North America | 0.4% |
| Europe | 0.24% |
| Asia Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Parent | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain |
| Asia Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Our analysis suggests Asia Pacific is the strategic battleground for 2026–2033, driven by public-sector digitization and court modernization. Europe grows steadily on GDPR and regulatory compliance demand. The U.S. will remain the single largest national market, but incremental growth increasingly comes from emerging Asia and the Middle East.
The primary growth driver is digital transformation across regulated sectors—healthcare, government, banking, and insurance—combined with AI/ML integration that improves case triage and decision-making. Restraints center on data-security concerns and legacy integration complexity.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Digital transformation in regulated sectors | Driver | High | Replaces manual processes; compliance mandates |
| AI/ML integration | Driver | High | Automates triage, routing, document review |
| Public-sector modernization | Driver | High | Court and welfare case digitization |
| Cloud cost-efficiency & scalability | Driver | High | Lower TCO; remote accessibility |
| Data security & privacy concerns | Restraint | Medium | Slows cloud adoption in sensitive verticals |
| Legacy integration complexity | Restraint | Medium | Raises switching costs and deployment time |
| Change resistance in legal/professional firms | Restraint | Medium | Training and workflow disruption |
Our analysis suggests drivers outweigh restraints through 2028, but integration costs could compress vendor margins if professional services are underpriced. Buyers should scrutinize integration SLAs and total cost of ownership, not sticker price.
The market is moderately concentrated: leading players collectively hold an estimated 65–75% of revenue, with the remainder fragmented across vertical specialists. Differentiation rests on vertical depth, AI capability, and integration ecosystems.
| Vendor | Positioning | Strength |
|---|---|---|
| Salesforce | Horizontal CRM + case suite | Ecosystem & scale |
| IBM | Enterprise case management | Compliance & AI |
| ServiceNow | Workflow automation | Core business suite |
| Pegasystems | BPM + case | Process automation |
| Appian | Low-code case platform | Agility |
| Clio | Legal practice management | Legal vertical depth |
| Social Solutions | Human services | Public-sector focus |
| Rocket Matter | Legal case management | SME law firms |
| CosmoLex | Legal + billing | All-in-one legal |
Our analysis suggests horizontal platforms (ServiceNow, Salesforce, Pegasystems) will consolidate mid-market share, while vertical specialists defend ground through workflow depth and compliance features that horizontals replicate slowly. Vendors without credible AI roadmaps face margin pressure as buyers demand automation ROI.
Selection hinges on vertical fit, integration capability, security posture, and total cost of ownership. Buyers should prioritize platforms with pre-built connectors to existing EHR, ERP, and court systems, since integration complexity is the leading cause of deployment delays and budget overruns. Regulatory compliance—HIPAA, GDPR, CJIS, and sector-specific rules—must be contractually supported, not assumed. Switching costs are high: data migration, staff retraining, and workflow reconfiguration can consume 6–18 months. Procurement should therefore negotiate exit clauses and data portability upfront. SMEs should favor cloud SaaS with modular pricing to avoid shelfware; large enterprises should demand configurable workflow engines and audit trails. Finally, AI features should be validated on real case data before contract signature—proof-of-concept performance rarely matches production scale.
The balance of evidence favors accelerated cloud and AI adoption as the dominant strategic imperative through 2033. The market's 13.4% CAGR is not uniform: services and Asia Pacific grow fastest, while North America and solutions anchor revenue. The strongest counter-argument is that data-security concerns and integration fatigue could suppress adoption in healthcare and government, slowing the forecast. We judge this a timing risk, not a structural one, because compliance-certified cloud offerings increasingly neutralize the security objection.
Actionable strategy for operators and investors:
What would change our conclusion: a sustained regulatory crackdown on cross-border data flows, or evidence that AI case triage fails audit standards at scale, would materially lower the forecast and shift value toward on-premise and regional vendors.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.4% from 2020-2034 |
| Segmentation |
|
The global case management software market was valued at USD 9.1 billion in 2025 and is projected to reach USD 24.2 billion by 2033, growing at a 13.4% CAGR during the forecast period.
North America leads with roughly 40% of global revenue in 2025, supported by advanced digital infrastructure and vendor concentration. Asia Pacific is the fastest-growing region through 2033.
Services is the fastest-growing component segment, driven by AI implementation, integration, and consulting demand. Cloud deployment already dominates with about 60% revenue share.
Leading vendors include Salesforce, IBM, ServiceNow, Pegasystems, Appian, Clio, Social Solutions, Rocket Matter, and CosmoLex. Together they hold an estimated 65–75% of market revenue.
Key drivers are digital transformation in healthcare, government, and financial services, rising compliance requirements, and AI/ML integration that automates case triage, routing, and document review.
Data security and privacy concerns, legacy system integration complexity, cost of migration, and change resistance among legal and professional staff are the primary restraints on faster adoption.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the case management software value chain, including independent software vendors, systems integrators, cloud infrastructure providers, vertical-specialist consultancies, and enterprise IT procurement teams. Decision-makers interviewed included VP-level Sourcing and Procurement leads, Heads of Digital Transformation, Chief Information Officers, and Commercial Operations Directors across healthcare, government, legal, and financial-services end users.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CIOs & Digital Transformation Heads | 38% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Directors | 20% |
| Compliance & Risk Managers | 12% |
| Company Type | Representation (%) |
|---|---|
| Independent Software Vendors | 40% |
| Systems Integrators & Consultancies | 30% |
| Cloud Infrastructure Providers | 18% |
| Enterprise End-User IT Teams | 12% |
Secondary validation draws on official multilateral and regulatory databases—including UN Comtrade, WTO trade statistics, US ITC filings, and Eurostat—alongside corporate annual reports (10-K and investor presentations), patent databases, and recognized standards bodies such as ISO and HL7 for healthcare data exchange. Public-sector procurement records and court modernization program disclosures were used to validate government vertical demand.
We triangulate a Top-Down allocation (macroeconomic IT-spend and vertical segment shares) with a Bottom-Up model (vendor revenue, seat pricing, and end-use consumption by vertical). Discrepancies are reconciled through weighted averaging and sensitivity testing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |