 Cloud Based Applications Market
 Size, CAGR & Outlook 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 192

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cloud Based Applications Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 389.3 B |
| 2025 | 458.9 B |
| 2026 | 541.0 B |
| 2027 | 637.8 B |
| 2028 | 751.9 B |
| 2029 | 886.4 B |
| 2030 | 1.045 M |

The Cloud Based Applications Market covers software and platform services delivered over public, private or hybrid cloud infrastructure and consumed by subscription, usage or outcome-based pricing. It spans SaaS business applications, PaaS development environments and supporting IaaS capacity, sold to enterprises and SMEs across regulated and unregulated verticals.
This analysis covers cloud-delivered application software and platform services segmented by deployment model, application type, industry vertical, organization size and region. It tracks subscription and consumption revenue only. This analysis does not cover on-premises perpetual-license software, physical data-center hardware, colocation real estate, or consumer mobile-app store economics.
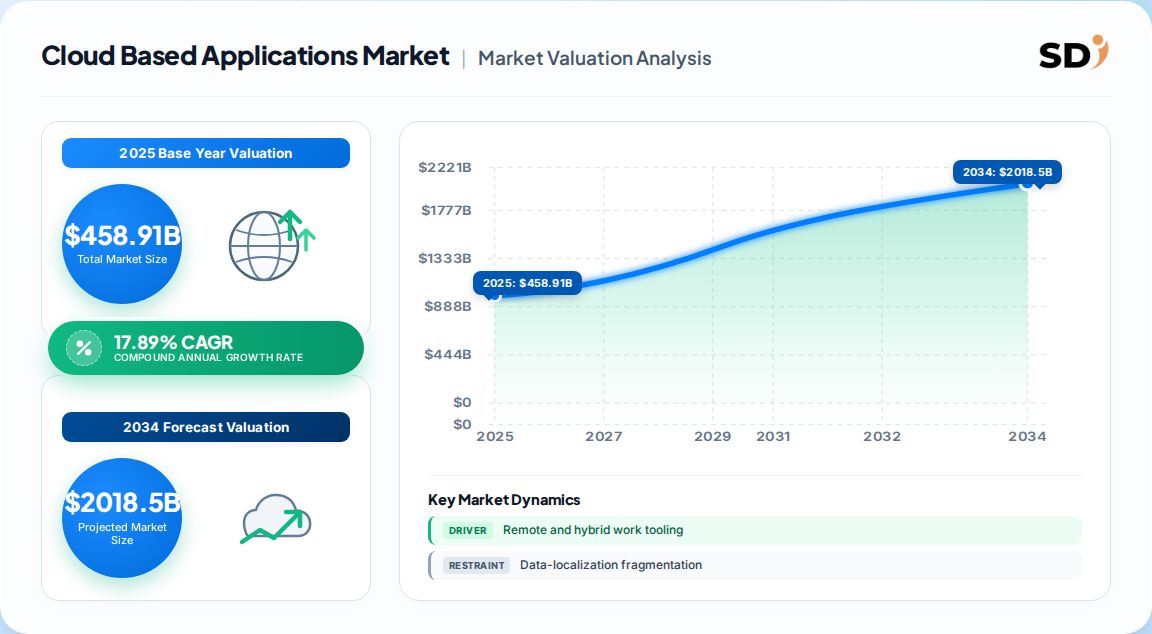
The most defensible figure is 458.91 Billion for 2025, anchored to a stated 389.26 Billion for 2024 and a 17.89% CAGR toward 2,379.98 Billion by 2035. Adjacent cloud-infrastructure estimates run higher because they count raw compute, storage and networking that application buyers do not purchase directly.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 389.26 Billion | 2024 | 2035 | 17.89% | Cloud-based application software and platforms | One published market estimate |
| 458.91 Billion | 2025 | 2035 | 17.89% | Same scope, forward base year | Same published estimate |
| 2,379.98 Billion | 2035 | 2035 | 17.89% | Terminal forecast value | Same published estimate |
| 0.83 Trillion | 2025 | 2034 | 20.12% | Full cloud computing incl. IaaS infrastructure | A competing analysis (broader scope) |
| 1.04 Trillion | 2026 | 2032 | 20.35% | Cloud service models incl. infrastructure | A separate competing analysis |
Our analysis suggests the 17.89% figure is the more conservative and therefore more usable planning number for application-layer buyers, since the trillion-dollar readings bundle infrastructure spend that procurement teams budget separately. The gap implies application-layer pricing power is being partly absorbed by hyperscaler infrastructure growth.
Segmentation runs along four commercial axes: how the software is hosted, what layer of the stack is sold, which vertical buys it, and how large the buying organization is. Deployment and application type drive pricing mechanics; vertical and size drive procurement cycles.
| Parent | Children |
|---|---|
| By Deployment Model | Public Cloud, Private Cloud, Hybrid Cloud |
| By Application Type | SaaS, PaaS, IaaS |
| By Industry Vertical | Healthcare, Retail, Manufacturing, Financial Services |
| By Organization Size | SMEs, Large Enterprises |
Public cloud holds the largest deployment share, but hybrid is the fastest-growing because regulated buyers keep sensitive workloads on dedicated infrastructure. SaaS dominates application type at roughly half of cloud-service revenue in comparable estimates, while PaaS grows fastest as low-code tooling spreads.
North America leads global cloud application spend on the strength of mature SaaS penetration and enterprise-scale hybrid estates. Asia-Pacific is the fastest-growing region, driven by hybrid adoption and public-sector cloud-first procurement across developing economies.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| South America | 0.05% |
| Middle East & Africa | 0.08% |
| Region | Share of global revenue |
|---|---|
| North America | 36% |
| Europe | 24% |
| Asia-Pacific | 27% |
| South America | 5% |
| Middle East & Africa | 8% |
This divergence implies buyers should treat North America as a pricing benchmark and Asia-Pacific as a sourcing and localization market, not a single global contract.
Growth is driven by remote-work tooling, scalability demand, compliance-ready platforms and AI/ML embedded in applications. Restraints center on data-localization rules, migration and integration cost, and security concerns in regulated sectors, which slow but rarely reverse adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Remote and hybrid work tooling | Driver | High | Sustained seats for collaboration and project software |
| Scalability and flexibility priority | Driver | High | Elastic capacity replaces fixed infrastructure capex |
| Compliance and data-privacy mandates | Driver | Medium | Vendors with certified controls win regulated deals |
| AI and ML embedded in applications | Driver | High | Usage-based consumption adds revenue per account |
| Data-localization laws | Restraint | Medium | Fragments global footprints and raises delivery cost |
| Migration and integration cost | Restraint | High | Extends sales cycles, especially for SMEs |
| Security and breach exposure | Restraint | Medium | Delays sensitive-workload migration in BFSI and health |
The balance favors growth: drivers are structural and demand-led, while restraints are mostly cost and compliance frictions that vendors mitigate through sovereign and industry-specific offerings.
The vendor field is led by hyperscalers that bundle infrastructure with applications, challenged by pure-play SaaS and workflow specialists. Differentiation now hinges on AI capability, compliance posture and integration depth rather than feature count.
| Vendor | Positioning | Primary strength |
|---|---|---|
| Microsoft | Hyperscaler plus productivity suite | Enterprise distribution and AI bundling |
| Amazon | Infrastructure-led with application services | Scale, pricing and developer ecosystem |
| Data and AI-centric cloud | Analytics and AI tooling | |
| IBM | Hybrid cloud and regulated industries | Enterprise integration and governance |
| Salesforce | CRM and platform SaaS | Customer data and ecosystem apps |
| Oracle | Enterprise applications and database | Mission-critical workloads |
| SAP | ERP and business process suite | Complex enterprise process depth |
| Adobe, ServiceNow, Atlassian | Workflow and creative SaaS | Category-specialist lock-in |
Our analysis suggests moats have shifted from switching costs alone to compliance certification and AI model access, which favors hyperscalers in large deals while specialists retain advantage in narrow workflows.
Buyers should evaluate total cost of ownership over a five-year horizon, not headline subscription price, because egress, integration and premium AI consumption frequently exceed license savings. Contract structures that cap consumption growth and guarantee data-portability are now table stakes.
Switching costs are highest where workflow customization and identity integration run deep; buyers should negotiate exit assistance clauses early. Regulatory compliance, particularly data residency and sector-specific controls, should be scored as a pass/fail criterion rather than a weighted preference. Operators should also test sovereign-cloud eligibility before shortlisting vendors in EU and GCC markets.
The balance of evidence favors sustained double-digit growth through 2035, with the 17.89% application-layer CAGR a credible midpoint. The strongest counter-argument is that AI consumption revenue inflates near-term growth while displacing traditional seat-based software, meaning headline expansion may mask per-seat contraction.
Our judgment is that the market is entering a consumption-pricing transition. Vendors that certify compliance early and expose AI capability through metered APIs will capture disproportionate share in regulated verticals, while seat-only pricing models face renewal pressure.
Evidence that would change this conclusion: a sustained deceleration in hybrid cloud adoption, or regulatory harmonization that removes localization friction, would shift value back toward pure public-cloud scale players.
Full methodology details, including primary interview distribution, triangulation logic and validation matrices, are provided in the methodology section of this report. Figures combine published benchmarks with bottom-up revenue triangulation and are validated against vendor filings and trade data.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.89% from 2020-2034 |
| Segmentation |
|
The market was estimated at 458.91 Billion in 2025, up from 389.26 Billion in 2024. That trajectory reflects steady enterprise migration plus rapid AI workload consumption across SaaS and PaaS layers.
One published estimate puts the 2025–2035 CAGR at 17.89%, projecting 2,379.98 Billion by 2035. Broader cloud computing estimates run near 20%, largely because they include infrastructure spend.
Asia-Pacific is the fastest-growing region, supported by hybrid cloud adoption and public-sector cloud-first procurement. North America remains the largest market, with roughly 36% of global application-layer revenue.
SaaS is the largest application type, while PaaS grows fastest as low-code and no-code platforms lower development barriers. Hybrid cloud is the quickest-growing deployment model among regulated buyers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, with 70% of analytical weight resting on direct industry engagement. In-depth interviews were conducted across the value chain with enterprise software vendors, managed service providers, systems integrators, cloud resellers and independent software vendors. Decision-maker designations interviewed included VP-level Sourcing and Procurement leads, Heads of Platform Engineering, Technical Directors and Commercial Operations Leads responsible for subscription and consumption revenue.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Platform & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Compliance & Security Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud Software Vendors | 40% |
| Systems Integrators | 25% |
| Managed Service Providers | 20% |
| Resellers & Distributors | 15% |
Secondary validation draws on official multilateral databases (Eurostat, UN Comtrade, WTO), corporate annual filings and investor presentations (10-K and equivalent disclosures), patent and trademark databases, and recognized industry standards bodies. Competitor research publications are used only as directional cross-checks and are never treated as primary evidence.
We run simultaneous Top-Down allocation (macroeconomic ICT spend and vertical segment apportionment) and Bottom-Up modeling (vendor revenue, seat and consumption pricing, end-user adoption). Both paths are reconciled to a single base-year value before forecasting.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue and consumption triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis and regional consumption modeling | High |
| Competitive Landscape | Leading market players | Annual filings, capacity mapping and commercial disclosures | High |