 Dental Practice Management Software Market
 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 216

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dental Practice Management Software Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 3.100 B |
| 2026 | 3.400 B |
| 2027 | 3.800 B |
| 2028 | 4.200 B |
| 2029 | 4.700 B |
| 2030 | 5.200 B |
| 2031 | 5.700 B |

Dental practice management software is a specialized platform that manages clinical charting, scheduling, patient communication, billing, insurance claims, and operational reporting for dental practices. It is evolving from an administrative system of record into an integrated workflow layer connecting clinical documentation, revenue-cycle activity, and AI-assisted decision support.
This analysis covers software platforms deployed in dental clinics, hospitals, and dental service organizations across on-premise, web-based, and cloud-based delivery models. It includes patient communication, invoicing and billing, payment processing, insurance management, and analytics modules. This analysis does not cover dental imaging hardware, CAD/CAM milling equipment, general-purpose EHR systems, or teledentistry point solutions sold independently of a practice management platform.
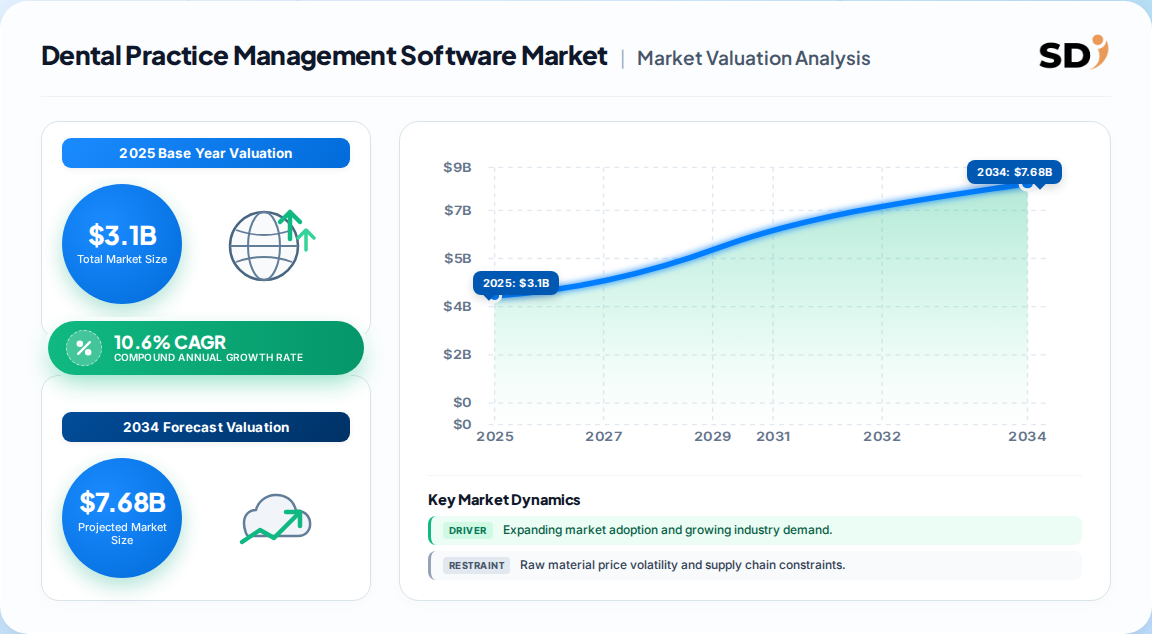
The most defensible base case is USD 3.1 billion in 2025, growing to USD 6.8 billion by 2033 at roughly 10.6% CAGR — a figure corroborated by independent estimates clustering between USD 2.6 billion and USD 3.4 billion for the 2025–2026 base period.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 3.1B → USD 6.8B | 2025 | 2033 | 10.6% | Global DPM software, all deployment modes | One published estimate |
| USD 2.63B → USD 6.94B | 2025 | 2035 | 10.3% | Global DPM software, bottom-up revenue modeling | A competing analysis |
| USD 2.62B → USD 4.44B | 2026 | 2031 | 11.1% | Global DPM software, segmented by delivery and practice size | A competing analysis |
| USD 3.4B (2026 base) | 2026 | 2033 | 10.9% (inline figure) | Global DPM software, application and end-use segmentation | One published estimate |
The divergence between estimates is primarily definitional: narrower scopes excluding analytics or insurance modules report lower base values, while broader scopes that bundle patient engagement and revenue-cycle tools report higher figures. Our analysis suggests the USD 3.1 billion base and 10.6% CAGR represent the most robust mid-point, aligning with the consensus trajectory for cloud migration and AI feature adoption across dental software.
The market segments primarily by deployment mode, application, end use, and practice size — with deployment mode being the most consequential axis for buyers because it dictates total cost of ownership, upgrade cadence, and security posture.
| Parent Segment | Children |
|---|---|
| Deployment Mode | On-premise, Web-based, Cloud-based |
| Application | Patient Communication, Invoice/Billing, Payment Processing, Insurance Management, Analytics |
| End Use | Dental Clinics, Hospitals, DSOs / Group Practices |
| Practice Size | Solo Practices, Small Groups, Multi-site DSOs |
| Subscription Model | Perpetual License, Subscription / SaaS |
On-premise installations held roughly 45.6% share in 2025, but cloud-based deployments are forecast to expand at 14.3% CAGR through 2031. SaaS already captures about 60.5% of subscription revenue, signaling that the commercial model has decisively shifted even where the technical deployment has not. Practices still holding perpetual licenses face a narrowing support window as vendors prioritize cloud feature velocity.
North America leads the global dental practice management software market with roughly 38% revenue share in 2025, supported by high dental-visit frequency, mature insurance infrastructure, and the HITEC Act's push for health IT adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
Asia Pacific is the fastest-growing region, driven by new clinic formation, low legacy-system penetration, and government digitization mandates such as India's district-hospital digital charting requirement. Europe's growth is more measured but is being reshaped by GDPR-driven data residency requirements, which favor certified cloud providers over fragmented local vendors.
Growth is being driven by the expanding global oral disease burden (3.5 billion affected), low cloud penetration (~23% of practices), and AI-assisted workflow automation — while cybersecurity compliance costs and market fragmentation cap adoption velocity, especially among solo practices.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising oral disease burden | Driver | High | Larger patient volumes increase scheduling, charting, and billing requirements |
| Cloud migration / low penetration | Driver | High | SaaS lowers CapEx; only 23% of practices on cloud |
| AI-assisted automation | Driver | Medium-High | Reduces front-office effort and raises switching costs |
| Interoperability mandates | Driver | High | Penalties up to USD 1M for blocking data exchange |
| Cybersecurity compliance costs | Restraint | High | 663 breach reports (500+ individuals) in 2024 in the U.S. |
| Fragmented practice base | Restraint | Medium | 135,665 U.S. establishments cap average contract value |
| Vendor lock-in risk | Restraint | Medium | Consolidated ecosystems raise switching costs |
The balance favors growth. The driver stack — cloud, AI, and interoperability — compounds over time, while the restraint stack is largely transitional: cybersecurity costs stabilize once a vendor's compliance posture matures, and fragmentation is being structurally addressed by DSO consolidation. Our analysis suggests the more underappreciated risk is implementation friction, not feature gaps; practices that underestimate data-migration effort frequently delay go-live and erode the ROI case that justified the purchase.
Henry Schein (HS One) leads with roughly 19.8% share, and the top five vendors together hold about 46.4% of the market, indicating a moderately concentrated landscape where scale, distribution, and installed-base loyalty create durable moats.
| Vendor | Positioning | Core Strength | Watch-point |
|---|---|---|---|
| Henry Schein (HS One) | Market leader | Distribution reach and integrated supply chain | Platform modernization pace |
| Patterson Companies | Strong #2 | Broad dental channel and EagleSoft ecosystem | Cloud transition execution |
| Carestream Dental | Imaging-integrated | Sensor and imaging integration depth | Breadth of practice-management suite |
| NextGen Healthcare | Enterprise/DSO | Multi-site and revenue-cycle strength | Dental-specific workflow depth |
| Epic Systems | Enterprise health systems | Hospital-side integration | Dental-native feature fit |
| Emerging AI-first vendors | Challengers | AI workflow automation, cloud-native UX | Scale and channel credibility |
Differentiation is shifting from feature breadth to workflow intelligence and interoperability. Vendors that publish practical API connections to imaging, CAD/CAM, and claims infrastructure are converting interoperability from a compliance burden into a lock-in mechanism. Our analysis suggests the strategic risk for incumbents is not losing existing practices but failing to win new DSO contracts, where standardization mandates favor API-first platforms over legacy suites.
Platform selection should be anchored on five criteria: interoperability breadth, security and compliance maturity, total cost of ownership over a five-year horizon, implementation and migration support, and AI roadmap credibility. Buyers should demand documented API connections to their imaging and claims infrastructure rather than roadmap promises, since information-blocking penalties now carry meaningful financial exposure.
Switching costs are the most under-modeled line item. A fully integrated practice typically carries 3–7 years of accumulated configuration, staff training, and historical patient data — meaning migration disruption, not license pricing, is the dominant economic factor. Our analysis suggests operators should negotiate data-export clauses and interoperability guarantees into contracts at signing, not at renewal. Multi-site DSOs should prioritize platforms with centralized reporting and role-based access, as consolidation economics depend on standardized workflows across acquired practices.
The balance of evidence favors a cloud-first, interoperability-anchored platform strategy for both buyers and vendors. The market's 10.6% CAGR is not evenly distributed: cloud-based deployment, insurance management, analytics, and DSO end-use are all growing well above the market average, meaning revenue pools are migrating away from the legacy on-premise, solo-practice core. Vendors that defend perpetual-license revenue too long risk ceding the fastest-growing segments to AI-native challengers.
The strongest counter-argument is that fragmentation insulates incumbents longer than forecast — with 135,665 U.S. practice establishments, many solo practices will defer migration due to cost sensitivity and implementation risk. That is a real brake, but it slows timing rather than changing direction: DSO consolidation and interoperability mandates progressively shrink the addressable base for legacy platforms.
Actionable strategy:
What would change our conclusion: a sustained deceleration in cloud adoption among solo practices, or regulatory rollback of interoperability penalties that reduces migration urgency. Conversely, Medicare Advantage acceptance of SNODENT-coded claims from 2027 would accelerate demand and reinforce our base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.6% from 2020-2034 |
| Segmentation |
|
The market was estimated at USD 3.1 billion in 2025 and is projected to reach USD 6.8 billion by 2033. Broader estimates range from USD 2.6 billion to USD 3.4 billion for the 2025–2026 base period, depending on module scope.
The market is forecast to grow at a 10.6% CAGR from 2026 to 2033. Competing analyses cluster between 10.3% and 11.1%, with differences driven mainly by base-year definitions and horizon length.
North America leads with roughly 38% revenue share in 2025, supported by high dental-visit frequency and mature insurance infrastructure. Asia Pacific is the fastest-growing region, driven by new clinic formation and digitization mandates.
Henry Schein (HS One) leads with about 19.8% share, followed by Patterson Companies, Carestream Dental, NextGen Healthcare, and Epic Systems. The top five vendors collectively hold roughly 46.4% of the market.
Key drivers include the expanding global oral disease burden affecting 3.5 billion people, low cloud penetration at roughly 23% of practices, AI-assisted workflow automation, and interoperability mandates that penalize information blocking.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the dental technology value chain, including practice management software vendors, dental service organization operators, imaging and CAD/CAM hardware integrators, cloud infrastructure providers, and authorized dental distributors. Decision-maker designations interviewed include Chief Technology Officers, VP of Product Management, Director of Clinical Operations, and Dental Practice Owners/Administrators.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology & Product Officers | 35% |
| Clinical Operations Directors | 30% |
| Practice Owners & Administrators | 22% |
| Security & Compliance Leads | 13% |
| Company Type | Representation (%) |
|---|---|
| Practice Management Software Vendors | 40% |
| DSOs & Multi-site Operators | 30% |
| Imaging & CAD/CAM Integrators | 18% |
| Cloud Infrastructure Providers | 12% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit standards and industry associations including the American Dental Association (ADA), HHS Office for Civil Rights, and ISO technical committees on health informatics.
Simultaneous Top-Down (macroeconomic allocation, healthcare IT spend ratios, dental practice establishment counts) and Bottom-Up (vendor revenue disclosure, subscription pricing, seat counts, and end-use consumption modeling) triangulation is applied to reconcile market size and forecast figures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
