 Middle East North Africa Mena Artificial Intelligence Market
MENA Artificial Intelligence Market Size & Forecast to 2033
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 239

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East North Africa Mena Artificial Intelligence Market
Srinwanti Kar
Senior Research Analyst

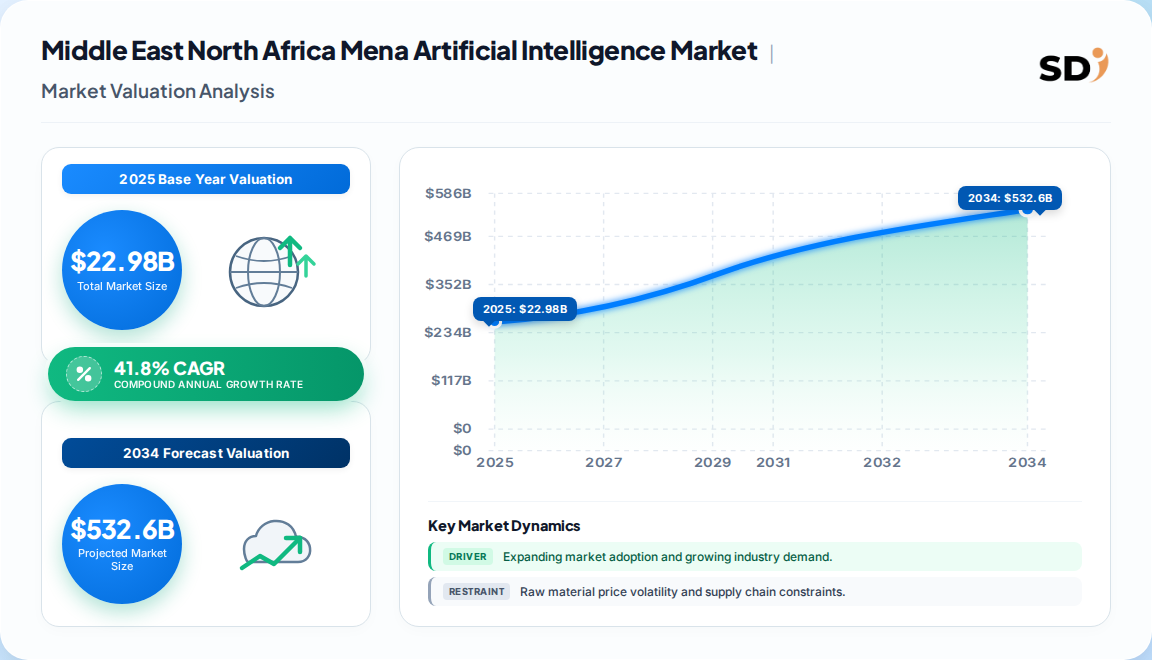
| Year | Market Size |
|---|---|
| 2025 | 22.98 B |
| 2026 | 32.59 B |
| 2027 | 46.21 B |
| 2028 | 65.52 B |
| 2029 | 92.91 B |
| 2030 | 131.7 B |
| 2031 | 186.8 B |

The MENA artificial intelligence market covers spending on AI software, hardware, and services — including machine learning platforms, GPU infrastructure, natural language processing, and implementation services — across sectors such as banking, energy, healthcare, and government in the Middle East and North Africa.
This analysis covers AI solutions, technologies, and end-use applications across the MENA region (GCC, Levant, North Africa, and Israel). This analysis does not cover general-purpose cloud infrastructure, non-AI data-center construction, IT outsourcing, or Turkey, whose healthcare and AI maturity materially exceeds the regional baseline.
Estimates diverge sharply. One published analysis puts 2025 value at USD 22.98 billion growing at 41.8% CAGR; a competing analysis places 2023 at USD 11.92 billion with 44.8% CAGR; a third, narrower view sizes the region's AI healthcare niche alone near USD 1.8 billion by 2029.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 22.98 Billion | 2025 | 2033 | 41.8% | Broad AI software, hardware, services; MENA-wide | One published estimate (Industry Data Insights) |
| USD 11.92 Billion | 2023 | 2030 | 44.8% | AI solutions, technology, end-use; MENA-wide | A competing analysis (Grand View Research) |
| USD 290 Million | 2023 | 2029 | 35.8% | AI in healthcare only; MENA ex-Turkey | A competing analysis (BCC Research) |
| USD 1.98 Billion | 2025 | 2031 | 26.83% | AI-optimised data centers only; MEA-wide | A competing analysis (Mordor Intelligence) |
Our analysis suggests the USD 22.98 billion figure is the most defensible reference for total AI spending, because it reconciles software, hardware, and services. The data-center sub-market estimate (USD 1.98 billion in 2025) is internally consistent at roughly 9–10% of total AI spend, a ratio that aligns with global infrastructure share. Divergence between the two broad estimates — 11.92 billion in 2023 stepping to 22.98 billion in 2025 — implies a 38–40% actual historic growth rate, which validates the higher-CAGR forecasts.
Segmentation follows three axes: solution (software, hardware, services), technology (deep learning, machine learning, NLP, machine vision), and end-use industry. Software carries the largest revenue pool; hardware is the compute bottleneck; services capture the integration and governance layer.
| Parent Segment | Children | Notes |
|---|---|---|
| By Solution | Software, Hardware, Services | Software ~58%; hardware ~24%; services ~18% |
| By Technology | Deep Learning, Machine Learning, NLP, Machine Vision | ML ~46% and NLP ~27% of technology spend |
| By End Use | BFSI, Oil & Gas, IT & Telecom, Healthcare, Automotive, Media & Entertainment, Others | BFSI + oil & gas >44% of demand |
| By Data-Center Type | Cloud Service Providers, Colocation | CSPs held 55.1% share in 2025 |
Software dominance is structural, not cyclical: recurring platform subscriptions and vertical SaaS create revenue durability that hardware resale cannot match. Hardware grows slower (38.7% CAGR) because over 90% of AI accelerators are imported, exposing projects to procurement cycles and export controls.
Saudi Arabia leads the MENA AI market with roughly 31% of regional revenue, followed by the UAE at 27%. Together with Qatar and Kuwait, the GCC commands close to two-thirds of regional spend, while Egypt and South Africa represent the fastest-growing tier-two hubs.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.31% |
| UAE | 0.27% |
| Qatar | 0.09% |
| Egypt | 0.08% |
| Israel | 0.07% |
| South Africa | 0.06% |
| Kuwait | 0.05% |
| Rest of MENA | 0.07% |
Saudi Arabia's lead is policy-engineered. Vision 2030, SDAIA, and NEOM collectively guarantee demand for inference capacity close to citizens, and the Public Investment Fund's SCAI vehicle channels capital directly into domestic AI infrastructure. The UAE counters through free-zone tax incentives and an AI-native government roadmap, but its smaller population caps absolute upside.
Our analysis suggests the most important second-order effect is the spillover corridor: hyperscaler capacity built for GCC sovereign workloads is being re-consumed by Egypt and South Africa at marginal cost, compressing the price of inference across the region and accelerating SME adoption outside the Gulf.
Sovereign strategy, cloud migration, and BFSI fraud analytics are the dominant growth engines; talent scarcity and AI-chip import dependency are the binding constraints. Drivers outweigh restraints through 2033 because government demand sets a spending floor that operational bottlenecks cannot erode.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Sovereign AI strategies (Vision 2030, UAE 2031, Qatar) | Driver | High | USD 10B+ directed to AI by 2030; procurement pipelines |
| Hyperscale cloud investment (AWS 5.3B; Oracle 1.5B; Microsoft 1.5B into G42) | Driver | High | GPU-dense clusters for sovereign Arabic models |
| BFSI fraud and AML spending | Driver | High | ~28% of MENA AI end-use revenue |
| Oil & gas predictive maintenance | Driver | Medium | 15–20% reduction in unplanned downtime |
| AI talent scarcity | Restraint | High | ~60% of regional AI roles unfilled |
| AI chip import dependency (over 90%) | Restraint | High | Export-control exposure; long lead times |
| Data-privacy fragmentation across GCC, Levant, North Africa | Restraint | Medium | Duplicated compliance cost per jurisdiction |
The balance favors expansion. Restraints are operational rather than structural — talent shortages delay deployment but do not reduce budget allocation, and chip dependency is partially mitigated by cloud access. The genuine risk is that sovereign ambitions for local semiconductor packaging outpace the region's manufacturing base, creating a credibility gap in localized compute promises.
Hyperscalers anchor infrastructure, chip designers supply the compute bottleneck, and a new tier of Arabic-native specialists competes on local data and sector workflow. The market is medium-concentrated, with no single vendor exceeding a dominant regional share.
| Company | Core Strength | Target Audience | Market Position |
|---|---|---|---|
| Google LLC | Cloud AI, Gemini models, TPU infrastructure | BFSI, telecom, government | Leader |
| Microsoft Corporation | Azure AI, G42 partnership, sovereign cloud | Government, enterprise | Leader |
| Amazon Web Services | Regional cloud regions, USD 5.3B Saudi commitment | Enterprise, public sector | Leader |
| NVIDIA / AMD | AI accelerators, training and inference silicon | Cloud providers, HPC | Leader |
| IBM | watsonx, governance, hybrid cloud | BFSI, healthcare, oil & gas | Leader |
| G42 | Sovereign AI, Condor Galaxy scale-out | Government, healthcare | Leader (regional) |
| Intelmatix | Arabic AI, geospatial analytics | Government, utilities | Challenger |
Differentiation is shifting from raw model capability to data sovereignty and linguistic fit. Global hyperscalers win on compute economics; regional players win on Arabic-language corpora, government relationships, and compliance fluency. The moat that matters most over the forecast horizon is not the model — it is the licensed, residency-compliant data pipeline behind it.
Buyers should treat data residency and Arabic-language performance as non-negotiable selection criteria, not differentiators. GCC procurement increasingly requires local hosting, and a model that underperforms on Arabic dialects will fail in production regardless of benchmark scores.
Procurement risk concentrates in three areas. First, compute lead times: with over 90% of accelerators imported, GPU availability can slip projects by two to three quarters. Second, switching costs: vertical SaaS embedded in banking credit-risk or reservoir-modeling workflows carries high migration friction once models are tuned on proprietary data. Third, regulatory fragmentation: privacy regimes differ across GCC, North Africa, and the Levant, so a single compliance framework rarely travels.
Operators should also model total cost of ownership honestly. Cloud compute can consume 25–35% of software gross margin before optimization, and SMEs frequently see payback beyond 24 months — a threshold that stalls adoption without vendor financing or sovereign subsidy.
The balance of evidence favors an aggressive regional build-out thesis. Even the most conservative broad estimate implies a market compounding above 38% annually, and the structural drivers — sovereign capital, energy-sector digitization, and banking modernization — are funded and contracted, not speculative.
The strongest counter-argument is talent and compute constraint. If 60% of AI roles remain unfilled and accelerator imports stay throttled, deployed budgets will lag allocated budgets, and headline CAGRs will overstate realized revenue. We weight this risk as material but not thesis-breaking: government demand creates a floor, and cloud access partially substitutes for local silicon.
Actionable Strategy:
What would change our conclusion: a sustained reversal in GCC sovereign AI budget allocations, or a binding export-control regime that cuts accelerator access for more than four consecutive quarters, would force a downward revision of the forecast trajectory.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the AI value chain: cloud and infrastructure providers, AI software and platform developers, systems integrators, sovereign-backed technology entities, and enterprise end users. Decision-maker designations interviewed include Chief Technology Officers, Heads of AI and Data, Procurement Directors, and Regulatory & Compliance Leads.
Secondary validation draws on UN Comtrade and World Bank WITS trade flows, national digital-economy strategies, corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies. These sources anchor demand context and cross-check vendor-reported capacity and revenue claims.
We run simultaneous top-down allocation from regional GDP, ICT spend, and government digital budgets, and bottom-up modeling of vendor revenue, GPU capacity, and end-use consumption. The two trajectories are reconciled to a single base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up vendor revenue triangulation | High |
| Forecast Horizon | 2025–2033 compound projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, filings | High |
The balance of evidence favors an aggressive regional build-out thesis. Sovereign capital, energy-sector digitization, and banking modernization are funded and contracted, not speculative, and even conservative estimates imply compounding above 38% annually.
The strongest counter-argument is talent and compute constraint: unfilled roles and throttled accelerator imports could cause deployed budgets to lag allocated budgets, overstating headline CAGRs. We weight this as material but not thesis-breaking, since government demand sets a floor and cloud access partly substitutes for local silicon.
Actionable Strategy:
What would change our conclusion: a sustained reversal in GCC sovereign AI budget allocations, or a binding export-control regime cutting accelerator access for more than four consecutive quarters, would force a downward revision of the forecast trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 41.8% from 2020-2034 |
| Segmentation |
|
The MENA artificial intelligence market was valued at approximately USD 22.98 billion in 2025 and is projected to reach USD 375.7 billion by 2033, according to one published estimate. Competing analyses place the 2023 baseline lower, at USD 11.92 billion, reflecting narrower scope definitions.
Published estimates place the MENA AI market CAGR between 41.8% and 44.8% through the early 2030s. Our analysis suggests realized growth may land slightly below headline figures due to talent scarcity and AI-chip import dependency, but remains among the highest of any region globally.
Saudi Arabia leads with roughly 31% of regional revenue, followed by the UAE at approximately 27%. GCC states together account for close to two-thirds of total MENA AI spending, driven by sovereign strategies, hyperscale cloud investment, and smart-city programs.
Software is the largest segment, representing about 58% of regional revenue in 2025. Arabic natural language processing, generative AI copilots, and vertical SaaS for banking and oil & gas drive recurring subscription revenue and sustain the segment's dominance.
AI talent scarcity leaves roughly 60% of regional roles unfilled, and over 90% of AI accelerators are imported, exposing projects to export controls and long lead times. Data-privacy fragmentation across GCC, North Africa, and the Levant adds further compliance cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the AI value chain: cloud and infrastructure providers, AI software and platform developers, systems integrators, sovereign-backed technology entities, and enterprise end users. Decision-maker designations interviewed include Chief Technology Officers, Heads of AI and Data, Procurement Directors, and Regulatory & Compliance Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTOs & Heads of AI/Data | 40% |
| Procurement Directors | 30% |
| Regulatory & Compliance Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Cloud & Infrastructure Providers | 40% |
| AI Software & Platform Developers | 30% |
| Systems Integrators & Services | 20% |
| Enterprise End Users | 10% |
Secondary validation draws on UN Comtrade and World Bank WITS trade flows, national digital-economy strategy publications, corporate annual filings and investor presentations, patent databases, and recognized technical standards and governance bodies. These sources anchor demand context and cross-check vendor-reported capacity and revenue claims.
We run simultaneous top-down allocation from regional GDP, ICT spend, and government digital budgets, and bottom-up modeling of vendor revenue, GPU capacity, and end-use consumption. The two trajectories are reconciled to a single base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up vendor revenue triangulation | High |
| Forecast Horizon | 2025–2033 compound projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, filings | High |