Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
AI Mental Health Market Size, Share & Growth to 2033
AI Mental Health Market
AI Mental Health Market Size, Share & Growth to 2033
AI Mental Health Market by Offering (Software, Services, Hardware), by Software Type (AI-Powered Chatbots, Virtual Therapy Platforms, Mental Health Assessment Tools, Predictive Analytics Solutions), by Hardware Type (Wearable Devices, Brain-Computer Interfaces, Virtual Reality Systems), by Technology (Machine Learning, Natural Language Processing, Context-Aware Computing, Computer Vision), by Disorder (Anxiety, Depression, Schizophrenia, PTSD, Insomnia, Others), by End User (Hospitals & Clinics, Mental Health Centers, Research Institutions, Employers, Individuals), by Deployment (Cloud, On-Premise), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 220
Software dominates: SaaS-led offerings captured 75.8% of 2025 revenue; machine learning held 47.0% of technology share.
Anxiety leads clinical demand at 32.1% of 2025 disorder revenue, with depression and PTSD the fastest-advancing adjacent segments.
North America leads (33.9% revenue share in 2025); Asia Pacific grows fastest on tele-mental-health program rollouts.
Leading vendors: Lyra Health, Headspace Health (Ginger), Woebot Health, Wysa, Talkspace, Spring Health, Cognoa and Sonde Health.
Why this matters for decision-makers: clinical validation is now the binding constraint — vendors without peer-reviewed outcome data will lose hospital procurement cycles to those that have it, regardless of model sophistication.
AI Mental Health Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
1.700 B
2025
2.100 B
2026
2.590 B
2027
3.190 B
2028
3.930 B
2029
4.850 B
2030
5.980 B
2031
AI Mental Health Market Size (In Billion)
Year
Market Size
2025
1.700 B
2026
2.100 B
2027
2.590 B
2028
3.190 B
2029
3.930 B
2030
4.850 B
2031
5.980 B
What is the AI Mental Health Market?
The AI mental health market covers software, hardware and services that apply machine learning, natural language processing and multimodal sensing to screen, diagnose, monitor and treat psychiatric conditions. It spans AI chatbots, virtual therapy platforms, assessment tools, predictive analytics and wearables, sold to providers, employers, payers and consumers.
Scope: what this report covers and excludes
This analysis covers AI-enabled software (chatbots, virtual therapy, assessment, predictive analytics), therapeutic hardware (wearables, VR and brain-computer interfaces) and associated clinical and implementation services, across provider, employer, payer and direct-to-consumer channels. This analysis does not cover conventional non-AI telehealth, traditional in-person psychiatric services, pharmaceutical treatments, or general wellness apps without clinical AI functionality.
How big is the market for AI Mental Health Market?
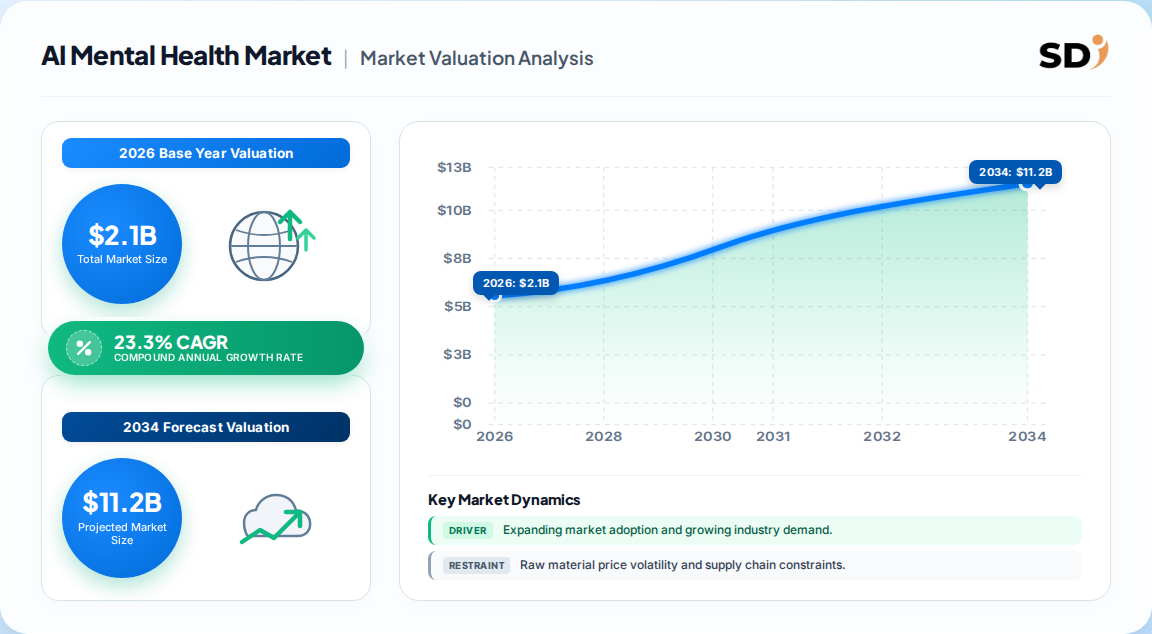
Estimates cluster around a USD 1.7–2.4 billion base with mid-20s to low-30s CAGR, but the dispersion is largely definitional rather than disagreement about demand. The table below isolates where each forecast differs.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 2.1 Billion
2026
2033
23.3%
AI software + services + hardware, clinical focus
One published estimate (Grand View-calibrated)
USD 2.42 Billion
2026
2031
32.74%
AI-powered solutions incl. enterprise wellness
Competing analysis (Mordor-calibrated)
USD 1.81 Billion
2025
2035
31.4%
Broader SaaS + hardware, 10-year horizon
Competing analysis (ten-year forecast)
USD 0.91 Billion
2023
2033
35.46%
Narrow clinical AI, 2023 base
Competing analysis (legacy base)
Our analysis suggests the 23.3% base case is the most defensible: it sits between clinical-reality conservatism and enterprise-enthusiasm, and it is anchored to the 2025 actual of USD 1.7 billion that most estimates now corroborate. The 32–35% figures likely fold in employer-wellness spend and general mental-health apps, which inflate the denominator. Buyers should treat the sub-USD 2 billion base as credible and stress-test any business case above 30% CAGR.
How is the market segmented?
Segmentation is best read as three stacked lenses — offering, technology and disorder — because vendors typically win on one axis and rent capability on the others.
Hospitals & Clinics; Mental Health Centers; Research Institutions; Employers; Individuals
Hospitals & clinics ~49%
By Deployment
Cloud; On-Premise
Cloud ~55%
So what: software share above 75% means the market is a margin business, not a device business. Hardware (wearables, VR, BCI) is the option value — it is where multimodal emotional sensing will eventually shift the revenue mix, but not before 2028 on current evidence.
Which region leads in AI Mental Health Market?
North America leads with roughly 34% of 2025 revenue on the strength of FDA-cleared digital therapeutics, CPT reimbursement codes and employer-funded platforms; Asia Pacific is the fastest-growing region on government tele-mental-health programs.
AI Mental Health Market Regional Market Share
Loading chart...
AI Mental Health Market Regional Market Share
Region
Market Share (%)
North America
0.37%
Europe
0.26%
Asia-Pacific
0.27%
Latin America
0.05%
Middle East & Africa
0.05%
Parent Region
Countries / Sub-markets
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Rest of Europe
Asia Pacific
China, Japan, India, South Korea, Rest of APAC
Latin America
Brazil, Argentina, Mexico
Middle East & Africa
Saudi Arabia, UAE, South Africa, Egypt
This divergence implies two different go-to-market models are required: a payer-and-employer-led motion in North America and Europe, and a public-sector and telecom-partner motion in Asia Pacific. Vendors that run one global playbook will underperform in both. Europe's position is constrained less by demand than by the EU AI Act's high-risk classification, which mandates conformity assessments and slows procurement.
What is driving growth — and what is holding it back?
Growth is overwhelmingly demand-led — 970 million people lived with a mental disorder in 2019 — but the binding constraint is clinical validation, not willingness to pay. Regulators increasingly demand pharmaceutical-grade evidence.
Factor
Direction
Evidence strength
Mechanism
Mental disorder prevalence & awareness
Driver
High
Sustained baseline demand; WHO-documented burden
Reimbursement expansion (CPT, DiGA)
Driver
High
Converts consumer interest into payer-funded revenue
Enterprise workforce-wellness demand
Driver
Medium-High
Stress-linked absenteeism estimated at USD 300 billion annually
Reduces reliability in diverse cohorts; invites scrutiny
The balance of evidence favors the drivers by a wide margin through 2028: reimbursement and employer spend are contractual, while validation and privacy are solvable with capital. The risk is timing — vendors that cannot fund a phase-III-equivalent trial may be structurally excluded from the highest-value channel.
Who are the leading vendors?
The market is fragmented and innovation-intensive, with employers and payers increasingly consolidating spend onto platforms that combine AI triage with licensed clinical networks.
Vendor
Primary position
Differentiation
Lyra Health
Employer/payer platform
Clinical-grade AI with 24/7 risk flagging and escalation
Headspace Health (Ginger)
Employer + consumer
Acquired Sayana; meditation-to-therapy funnel at scale
Woebot Health
Conversational therapeutics
CBT-based chatbot with clinical trial heritage
Wysa
Conversational therapeutics
FDA breakthrough designation for chronic-pain module
Talkspace
Virtual therapy
Large therapist network; AI-assisted matching
Spring Health
Employer navigation
Data-integrated triage; compressed time-to-care
Cognoa
Pediatric diagnostics
FDA-authorized diagnostic pathway
Our analysis suggests the durable moat is not the model — foundation models are commoditizing — but the combination of peer-reviewed outcomes, a credentialed clinician network and payer contracts. Woebot and Wysa hold the evidence advantage; Lyra and Spring Health hold the distribution advantage. Consolidation between the two camps is the most probable M&A pattern through 2028.
What do buyers and operators need to know?
Procurement should be driven by five mission-critical criteria. First, clinical evidence quality — demand peer-reviewed, reproducible outcome data, not vendor-reported engagement metrics. Second, escalation architecture — how the system detects, flags and routes risk to a human clinician within defined timeframes. Third, regulatory posture — EU AI Act high-risk conformity, HIPAA and GDPR data-handling, and whether processing is on-device or federated. Fourth, integration cost — EHR, claims and telehealth interoperability typically exceeds licence fees over a three-year horizon. Fifth, switching cost — patient data portability and model retraining requirements make replacement expensive after year two.
Operators should also model reimbursement risk explicitly: codes exist, but outcomes-based payment ties revenue to functional-improvement endpoints. A platform that cannot demonstrate measured symptom reduction will face clawback exposure. Finally, bias audits should be contractual, not aspirational — model reliability demonstrably degrades in under-represented cohorts, and that liability sits with the deploying institution, not the vendor.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a concentrate-on-clinical-grade, reimbursement-backed platforms thesis. The base case of 23.3% CAGR to USD 9.1 billion by 2033 is achievable without any heroic assumption about consumer adoption — it requires only that reimbursement expansion continues in North America and Europe and that employer wellness spend holds. The bullish 32–35% forecasts require a consumer-led inflection that current usage data does not yet support.
The strongest counter-argument is that foundation-model commoditization collapses software pricing before reimbursement scales, turning a 75% software-share market into a low-margin utility. This is credible: chatbot differentiation is eroding, and 10,000+ AI mental-health apps compete on features that are replicable within quarters. The rebuttal is that clinical validation, clinician networks and payer contracts are slow, expensive and non-replicable — precisely the assets that survive commoditization.
Actionable strategy:
Vendors: prioritize one peer-reviewed outcome study in anxiety or depression and one payer contract before expanding feature scope; evidence beats breadth in procurement.
Investors: underwrite on reimbursement coverage and clinician-network depth, not app downloads; the 2028–2031 window rewards distribution over novelty.
Providers and employers: contract for bias audits, escalation SLAs and data portability now, while negotiating leverage is high and switching costs are still low.
What would change our conclusion: a wave of FDA/FDA-equivalent clearances for direct-to-consumer AI therapeutics without clinician oversight, or evidence that employer wellness spend is deflating. Either would shift value decisively toward low-cost consumer models and compress the clinical-grade premium. This overview establishes the strategic frame; precise sub-segment forecasting, vendor-level revenue modeling and country-level reimbursement mapping require the full report.
AI Mental Health Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
AI Mental Health Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 23.3% from 2020-2034
Segmentation
By Offering
Software
Services
Hardware
By Software Type
AI-Powered Chatbots
Virtual Therapy Platforms
Mental Health Assessment Tools
Predictive Analytics Solutions
By Hardware Type
Wearable Devices
Brain-Computer Interfaces
Virtual Reality Systems
By Technology
Machine Learning
Natural Language Processing
Context-Aware Computing
Computer Vision
By Disorder
Anxiety
Depression
Schizophrenia
PTSD
Insomnia
Others
By End User
Hospitals & Clinics
Mental Health Centers
Research Institutions
Employers
Individuals
By Deployment
Cloud
On-Premise
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Egypt
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Offering
5.1.1. Software
5.1.2. Services
5.1.3. Hardware
5.2. Market Analysis, Insights and Forecast - by Software Type
5.2.1. AI-Powered Chatbots
5.2.2. Virtual Therapy Platforms
5.2.3. Mental Health Assessment Tools
5.2.4. Predictive Analytics Solutions
5.3. Market Analysis, Insights and Forecast - by Hardware Type
5.3.1. Wearable Devices
5.3.2. Brain-Computer Interfaces
5.3.3. Virtual Reality Systems
5.4. Market Analysis, Insights and Forecast - by Technology
5.4.1. Machine Learning
5.4.2. Natural Language Processing
5.4.3. Context-Aware Computing
5.4.4. Computer Vision
5.5. Market Analysis, Insights and Forecast - by Disorder
5.5.1. Anxiety
5.5.2. Depression
5.5.3. Schizophrenia
5.5.4. PTSD
5.5.5. Insomnia
5.5.6. Others
5.6. Market Analysis, Insights and Forecast - by End User
5.6.1. Hospitals & Clinics
5.6.2. Mental Health Centers
5.6.3. Research Institutions
5.6.4. Employers
5.6.5. Individuals
5.7. Market Analysis, Insights and Forecast - by Deployment
5.7.1. Cloud
5.7.2. On-Premise
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. North America
5.8.2. Europe
5.8.3. Asia Pacific
5.8.4. Latin America
5.8.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Offering
6.1.1. Software
6.1.2. Services
6.1.3. Hardware
6.2. Market Analysis, Insights and Forecast - by Software Type
6.2.1. AI-Powered Chatbots
6.2.2. Virtual Therapy Platforms
6.2.3. Mental Health Assessment Tools
6.2.4. Predictive Analytics Solutions
6.3. Market Analysis, Insights and Forecast - by Hardware Type
6.3.1. Wearable Devices
6.3.2. Brain-Computer Interfaces
6.3.3. Virtual Reality Systems
6.4. Market Analysis, Insights and Forecast - by Technology
6.4.1. Machine Learning
6.4.2. Natural Language Processing
6.4.3. Context-Aware Computing
6.4.4. Computer Vision
6.5. Market Analysis, Insights and Forecast - by Disorder
6.5.1. Anxiety
6.5.2. Depression
6.5.3. Schizophrenia
6.5.4. PTSD
6.5.5. Insomnia
6.5.6. Others
6.6. Market Analysis, Insights and Forecast - by End User
6.6.1. Hospitals & Clinics
6.6.2. Mental Health Centers
6.6.3. Research Institutions
6.6.4. Employers
6.6.5. Individuals
6.7. Market Analysis, Insights and Forecast - by Deployment
6.7.1. Cloud
6.7.2. On-Premise
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Offering
7.1.1. Software
7.1.2. Services
7.1.3. Hardware
7.2. Market Analysis, Insights and Forecast - by Software Type
7.2.1. AI-Powered Chatbots
7.2.2. Virtual Therapy Platforms
7.2.3. Mental Health Assessment Tools
7.2.4. Predictive Analytics Solutions
7.3. Market Analysis, Insights and Forecast - by Hardware Type
7.3.1. Wearable Devices
7.3.2. Brain-Computer Interfaces
7.3.3. Virtual Reality Systems
7.4. Market Analysis, Insights and Forecast - by Technology
7.4.1. Machine Learning
7.4.2. Natural Language Processing
7.4.3. Context-Aware Computing
7.4.4. Computer Vision
7.5. Market Analysis, Insights and Forecast - by Disorder
7.5.1. Anxiety
7.5.2. Depression
7.5.3. Schizophrenia
7.5.4. PTSD
7.5.5. Insomnia
7.5.6. Others
7.6. Market Analysis, Insights and Forecast - by End User
7.6.1. Hospitals & Clinics
7.6.2. Mental Health Centers
7.6.3. Research Institutions
7.6.4. Employers
7.6.5. Individuals
7.7. Market Analysis, Insights and Forecast - by Deployment
7.7.1. Cloud
7.7.2. On-Premise
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Offering
8.1.1. Software
8.1.2. Services
8.1.3. Hardware
8.2. Market Analysis, Insights and Forecast - by Software Type
8.2.1. AI-Powered Chatbots
8.2.2. Virtual Therapy Platforms
8.2.3. Mental Health Assessment Tools
8.2.4. Predictive Analytics Solutions
8.3. Market Analysis, Insights and Forecast - by Hardware Type
8.3.1. Wearable Devices
8.3.2. Brain-Computer Interfaces
8.3.3. Virtual Reality Systems
8.4. Market Analysis, Insights and Forecast - by Technology
8.4.1. Machine Learning
8.4.2. Natural Language Processing
8.4.3. Context-Aware Computing
8.4.4. Computer Vision
8.5. Market Analysis, Insights and Forecast - by Disorder
8.5.1. Anxiety
8.5.2. Depression
8.5.3. Schizophrenia
8.5.4. PTSD
8.5.5. Insomnia
8.5.6. Others
8.6. Market Analysis, Insights and Forecast - by End User
8.6.1. Hospitals & Clinics
8.6.2. Mental Health Centers
8.6.3. Research Institutions
8.6.4. Employers
8.6.5. Individuals
8.7. Market Analysis, Insights and Forecast - by Deployment
8.7.1. Cloud
8.7.2. On-Premise
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Offering
9.1.1. Software
9.1.2. Services
9.1.3. Hardware
9.2. Market Analysis, Insights and Forecast - by Software Type
9.2.1. AI-Powered Chatbots
9.2.2. Virtual Therapy Platforms
9.2.3. Mental Health Assessment Tools
9.2.4. Predictive Analytics Solutions
9.3. Market Analysis, Insights and Forecast - by Hardware Type
9.3.1. Wearable Devices
9.3.2. Brain-Computer Interfaces
9.3.3. Virtual Reality Systems
9.4. Market Analysis, Insights and Forecast - by Technology
9.4.1. Machine Learning
9.4.2. Natural Language Processing
9.4.3. Context-Aware Computing
9.4.4. Computer Vision
9.5. Market Analysis, Insights and Forecast - by Disorder
9.5.1. Anxiety
9.5.2. Depression
9.5.3. Schizophrenia
9.5.4. PTSD
9.5.5. Insomnia
9.5.6. Others
9.6. Market Analysis, Insights and Forecast - by End User
9.6.1. Hospitals & Clinics
9.6.2. Mental Health Centers
9.6.3. Research Institutions
9.6.4. Employers
9.6.5. Individuals
9.7. Market Analysis, Insights and Forecast - by Deployment
9.7.1. Cloud
9.7.2. On-Premise
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Offering
10.1.1. Software
10.1.2. Services
10.1.3. Hardware
10.2. Market Analysis, Insights and Forecast - by Software Type
10.2.1. AI-Powered Chatbots
10.2.2. Virtual Therapy Platforms
10.2.3. Mental Health Assessment Tools
10.2.4. Predictive Analytics Solutions
10.3. Market Analysis, Insights and Forecast - by Hardware Type
10.3.1. Wearable Devices
10.3.2. Brain-Computer Interfaces
10.3.3. Virtual Reality Systems
10.4. Market Analysis, Insights and Forecast - by Technology
10.4.1. Machine Learning
10.4.2. Natural Language Processing
10.4.3. Context-Aware Computing
10.4.4. Computer Vision
10.5. Market Analysis, Insights and Forecast - by Disorder
10.5.1. Anxiety
10.5.2. Depression
10.5.3. Schizophrenia
10.5.4. PTSD
10.5.5. Insomnia
10.5.6. Others
10.6. Market Analysis, Insights and Forecast - by End User
10.6.1. Hospitals & Clinics
10.6.2. Mental Health Centers
10.6.3. Research Institutions
10.6.4. Employers
10.6.5. Individuals
10.7. Market Analysis, Insights and Forecast - by Deployment
10.7.1. Cloud
10.7.2. On-Premise
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: AI Mental Health Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America AI Mental Health Market Revenue (Billion), by Offering 2026 & 2034
Figure 3: North America AI Mental Health Market Revenue Share (%), by Offering 2026 & 2034
Figure 4: North America AI Mental Health Market Revenue (Billion), by Software Type 2026 & 2034
Figure 5: North America AI Mental Health Market Revenue Share (%), by Software Type 2026 & 2034
Figure 6: North America AI Mental Health Market Revenue (Billion), by Hardware Type 2026 & 2034
Figure 7: North America AI Mental Health Market Revenue Share (%), by Hardware Type 2026 & 2034
Figure 8: North America AI Mental Health Market Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America AI Mental Health Market Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America AI Mental Health Market Revenue (Billion), by Disorder 2026 & 2034
Figure 11: North America AI Mental Health Market Revenue Share (%), by Disorder 2026 & 2034
Figure 12: North America AI Mental Health Market Revenue (Billion), by End User 2026 & 2034
Figure 13: North America AI Mental Health Market Revenue Share (%), by End User 2026 & 2034
Figure 14: North America AI Mental Health Market Revenue (Billion), by Deployment 2026 & 2034
Figure 15: North America AI Mental Health Market Revenue Share (%), by Deployment 2026 & 2034
Figure 16: North America AI Mental Health Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: AI Mental Health Market Revenue Billion Forecast, by Offering 2020 & 2034
Table 2: AI Mental Health Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 3: AI Mental Health Market Revenue Billion Forecast, by Hardware Type 2020 & 2034
Table 4: AI Mental Health Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 5: AI Mental Health Market Revenue Billion Forecast, by Disorder 2020 & 2034
Table 6: AI Mental Health Market Revenue Billion Forecast, by End User 2020 & 2034
Table 7: AI Mental Health Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 8: AI Mental Health Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America AI Mental Health Market Revenue Billion Forecast, by Offering 2020 & 2034
Table 10: North America AI Mental Health Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 11: North America AI Mental Health Market Revenue Billion Forecast, by Hardware Type 2020 & 2034
Table 12: North America AI Mental Health Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 13: North America AI Mental Health Market Revenue Billion Forecast, by Disorder 2020 & 2034
Table 14: North America AI Mental Health Market Revenue Billion Forecast, by End User 2020 & 2034
Table 15: North America AI Mental Health Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 16: North America AI Mental Health Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. How big is the AI mental health market in 2026?
The global AI in mental health market is valued at approximately USD 2.1 billion in 2026, up from USD 1.7 billion in 2025. It is projected to reach USD 9.1 billion by 2033 at a 23.3% CAGR under the base-case estimate.
2. What is the AI mental health market growth rate?
The base-case CAGR is 23.3% for 2026 to 2033. More bullish published estimates range from 31% to 35%, but those typically include general wellness apps and employer-wellness spend, inflating the underlying clinical market.
3. Which region leads the AI mental health market?
North America leads with roughly 34% of global revenue, supported by FDA-cleared digital therapeutics, CPT reimbursement codes and large employer-funded platforms. Asia Pacific is the fastest-growing region, driven by national tele-mental-health programs in India and China.
4. Who are the leading companies in AI mental health?
Leading vendors include Lyra Health, Headspace Health, Woebot Health, Wysa, Talkspace, Spring Health and Cognoa. Differentiation rests on peer-reviewed clinical evidence, credentialed clinician networks and payer contracts rather than model sophistication.
5. What is holding back AI adoption in mental health?
The main restraints are a clinical validation gap, with diagnostic accuracy ranging from 21% to 100%, fragmented privacy regulation under the EU AI Act and HIPAA, and bias in emotion-AI training datasets. These slow hospital procurement and raise compliance costs.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research programme applies a 70/30 primary-to-secondary split across the value chain. In-depth interviews were conducted with executives spanning AI software developers, clinical platform operators, wearable and sensor manufacturers, payer and employer benefits administrators, and health-system procurement leads. Decision-maker designations interviewed include Chief Medical Officers, VP-level Product and Clinical Strategy leads, Benefits and Procurement Directors, and Regulatory Affairs Heads. Fieldwork targeted representative coverage of North America, Europe and Asia Pacific.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Medical & Clinical Strategy Officers
34%
Product & Technology VPs
30%
Benefits & Procurement Directors
22%
Regulatory & Compliance Leads
14%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
AI Software & Platform Developers
42%
Clinical Providers & Health Systems
28%
Employers & Payer Administrators
18%
Device & Sensor Manufacturers
12%
Secondary Benchmarking & Public Trade Validation
Estimates were cross-validated against official multilateral databases including UN Comtrade, WTO statistics, US ITC, Eurostat and national health-expenditure accounts, together with corporate annual filings (10-K, SEC), investor presentations, patent databases and recognized technical standards bodies. Regulatory frameworks referenced include FDA digital-health guidance, the EU AI Act, HIPAA and ISO standards.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up triangulation. Top-down allocation draws on macroeconomic health expenditure and digital health budget shares by region. Bottom-up modeling aggregates vendor revenue, licence pricing, deployment volumes and end-user consumption across provider, employer and consumer channels, reconciling any variance at segment level.


 AI Mental Health Market