 Self Service Analytics Market
: Global Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 271

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Self Service Analytics Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 5.500 B |
| 2026 | 6.100 B |
| 2027 | 6.700 B |
| 2028 | 7.300 B |
| 2029 | 7.900 B |
| 2030 | 8.600 B |
| 2031 | 9.400 B |

The self service analytics market is the software platform segment that enables business users to access, query, visualize, and act on enterprise data through graphical interfaces, automated data preparation, and governed access controls — without continuous reliance on IT or data-science teams. It spans dashboards, no-code reporting, and embedded analytics.
This analysis covers global and regional market sizing for self service analytics software platforms and accompanying professional services, segmented by component, deployment mode, organization size, vertical, and region, with a forecast horizon of 2026–2036. Market sizing draws on enterprise software adoption rates, license deployments, and usage intensity across business functions.
This analysis does not cover custom-built analytics software developed internally, advanced data-science platforms requiring specialized coding, data storage infrastructure, database management systems, ERP software, consulting and systems integration projects, training programs, or data governance advisory services.
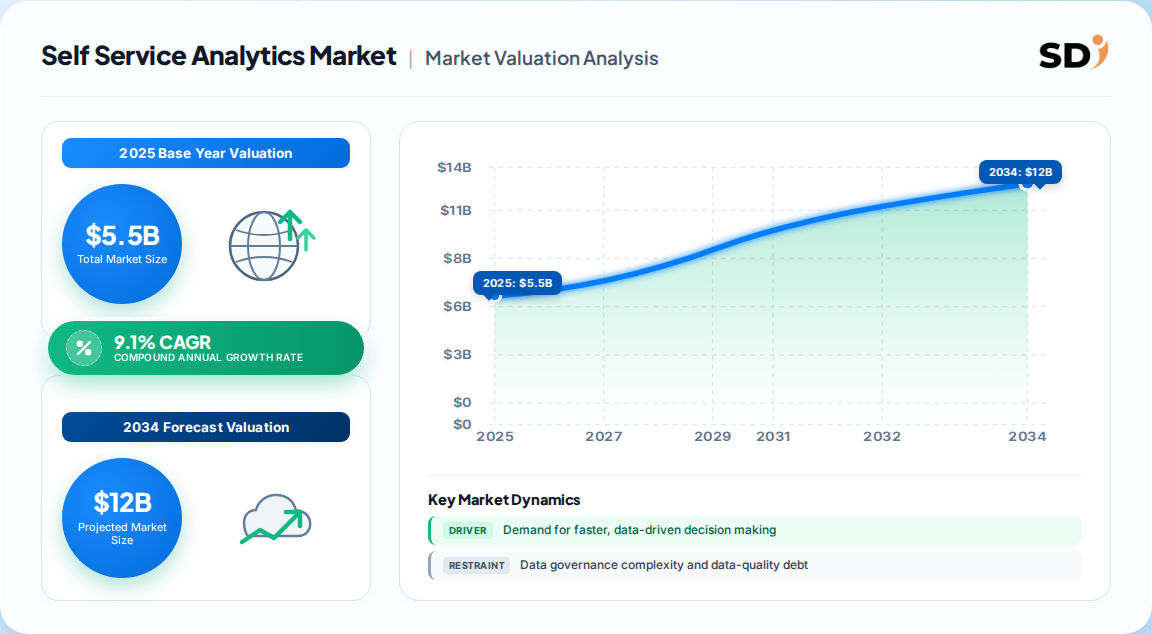
The most defensible reading is USD 5.5 billion for 2025, growing to roughly USD 6.1 billion in 2026 at a 9.1% CAGR through 2036. This base sits between more aggressive country-level and platform-level estimates, which we reconcile below.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 5.5 Billion base; USD 6.1 Billion (2026) → USD 14.5 Billion (2036) | 2025 | 2036 | 9.1% | Global software platforms + professional services; excludes custom builds and data-science platforms | One published estimate (Fact.MR-equivalent) |
| USD 4.8 Billion base; USD 6.0 Billion (2026) → USD 17.5 Billion (2033) | 2024 | 2033 | 15.9% | Global; software (61.7%) + services; broader application scope including embedded analytics | Competing analysis (Grand View-equivalent) |
| USD 1.20 Billion (2025) → USD 5.69 Billion (2035), US only | 2024 | 2035 | 16.86% | United States only; Tableau, Qlik, SAS, Logi, cloud + on-premise | Competing analysis (MRFR-equivalent) |
The spread between 9.1% and 15.9% is largely definitional: the higher CAGR tracks a narrower 2025–2033 window that captures the steepest portion of the cloud migration curve. Our analysis suggests the 9.1% track is the more defensible planning basis because it deliberately excludes custom builds and adjacent data-science spend, and because it reconciles to the ~37% North America share and 65% software share implied by the component split. For operators building long-range plans, we recommend anchoring on 9–11% and stress-testing against 15%.
Segmentation follows component, deployment, organization size, vertical, and application — with software platforms carrying roughly two-thirds of total value and cloud deployment setting the pace of adoption.
| Parent segment | Children |
|---|---|
| By Component | Software platforms, Professional services (consulting, implementation, training) |
| By Deployment Mode | Cloud-based, On-premises |
| By Organization Size | Large enterprises, Small & medium businesses |
| By Vertical | BFSI, Healthcare, Retail, IT & Telecommunications, Manufacturing, Others |
| By Application | Data visualization & reporting, Business intelligence & reporting, Predictive & advanced analytics, Embedded analytics |
Two structural asymmetries matter. First, software holds ~65% of component value, but the services segment is forecast to grow fastest because governance-heavy deployments require implementation and enablement. Second, on-premises retains the largest installed base in the US legacy estate while cloud is the fastest-growing deployment — a distinction buyers should not conflate when scoping migrations.
North America leads with roughly 37% of global revenue, driven by mature enterprise cloud estates and analytics-native operating models. The US alone grows at 10.1% CAGR, Germany follows at 9.4%, Japan at 9.2%, China at 8.7%, and South Korea at 8.3%.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
North America
Europe
Asia Pacific
Latin America
Middle East & Africa
Saudi Arabia
UAE
South Africa
North America: ~37% share; US growth 10.1% CAGR reflects enterprise cloud maturity.
Asia Pacific: fastest-growing region; SME cloud adoption in China (8.7%) and Japan (9.2%) drives volume.
Europe: Germany's 9.4% CAGR tied to industrial digitization and manufacturing analytics.
Latin America & MEA: smaller absolute bases, but subscription pricing lowers the entry barrier.
Our analysis suggests the North America share will compress modestly by 2036 as Asia Pacific absorbs incremental cloud-native spend — a reallocation that matters for vendors pricing per-seat in mature markets versus per-usage in emerging ones.
Demand is premised on time-to-insight compression — business units are pushing back on IT-led reporting cycles — and is enabled by cloud scalability and subscription licensing that lowers upfront capital requirements.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Demand for faster, data-driven decisions | Driver | High | Business units require real-time dashboards; reduces IT dependency |
| Cloud migration & scalable storage | Driver | High | Lowers upfront hardware cost; supports distributed teams |
| AI/ML and NLP-assisted query | Driver | High | Extends adoption to non-technical users via natural-language interfaces |
| Governance & security requirements | Driver | Medium | Compliance frameworks standardize platform selection and raise switching costs |
| Data source proliferation | Driver | High | Structured, unstructured, and IoT data demand versatile tools |
| Governance complexity and data-quality debt | Restraint | Medium | Poorly governed catalogs erode trust and stall adoption |
| Security and privacy exposure | Restraint | Medium | Sensitive-data access widens the attack surface |
| Legacy on-premises estates | Restraint | Medium | Migration cost and skill gaps delay cloud transitions |
| Vendor lock-in and tool sprawl | Restraint | Medium | Multiple overlapping BI licenses dilute ROI |
The balance of evidence favors demand: two independent estimates converge on double-digit growth, and the driver set is structural rather than cyclical. The strongest counter-argument is that governance complexity is not a side issue — it is the rate-limiting constraint on the entire category. Every dollar of broader user access multiplies the compliance surface, and organizations that under-invest in catalogs and access controls will see adoption plateau. This divergence implies vendors that sell governed access as the product, rather than as an add-on, will capture disproportionate share.
The field is consolidated at the top and fragmenting at the edges — hyperscalers and legacy BI incumbents hold the enterprise estate, while AI-native and embedded specialists compete on speed to insight.
| Vendor | Positioning | Primary moat |
|---|---|---|
| Tableau (Salesforce) | Visual analytics leader | Installed base, visualization UX, community |
| Microsoft (Power BI) | Volume leader | Bundling with Azure/M365, price-to-value |
| Qlik | Associative engine | Data integration heritage, governed self-service |
| SAP | ERP-embedded analytics | Enterprise process integration |
| IBM | Cognos / planning analytics | Governance, regulated-industry trust |
| Oracle | Cloud analytics | Database and application adjacency |
| Sisense | Embedded analytics | OEM/ISV embedding |
| Domo | Business cloud | Workflow and executive dashboards |
| Looker (Google) | Semantic modeling | LookML governance, GCP integration |
Differentiation is shifting from visualization to governance and natural-language access. Microsoft's moat is distribution, not feature leadership; Tableau's is UX and installed base; Looker's is semantic modeling. Our analysis suggests the durable moat in 2026–2036 is the governed semantic layer — the asset that makes AI-assisted query trustworthy at scale.
Selection criteria are converging on three mission-critical axes: governance depth, semantic-layer portability, and total cost of ownership at scale. Buyers should weight semantic modeling and row-level access controls above dashboard aesthetics, because the latter is commoditizing while the former determines whether non-technical adoption is safe.
Procurement risk is concentrated in two areas. First, switching costs: once business users build workflows on a platform's semantic layer, migration costs are organizational, not just technical — plan for 18–24 months of dual-running. Second, seat-based pricing traps: as adoption expands from analysts to operational staff, per-seat licensing can invert the ROI case that justified the purchase. Negotiate usage-based or embedded pricing tiers early.
Regulatory compliance is now a selection criterion, not a checklist item. Data governance, privacy, and digital system use are guided by frameworks from bodies such as NIST and public data-protection authorities; buyers in BFSI and healthcare should require demonstrable alignment before piloting. The gap: while this overview maps the competitive and demand landscape, precise sub-segment forecasting — by vertical, organization size, and country — requires the full report's model.
The balance of evidence favors a governance-led growth thesis over a pure visualization thesis. Two independent estimates converge on double-digit expansion, the driver set is structural, and the fastest-growing component is services — which means the value is migrating from dashboards to enablement and control. The strongest counter-argument is that AI-native interfaces could commoditize the platform layer faster than governance complexity slows adoption; if that happens, pricing power shifts decisively to the model providers and the incumbents' seat-based revenue compresses.
Our judgment: the commoditization risk is real but time-bounded to the query interface, not the semantic layer. Buyers who treat natural-language query as the product will overpay; buyers who treat it as the front door to a governed model will compound advantage. Vendors should price governance and semantic modeling as premium tiers, because that is where switching costs — and defensibility — actually reside.
What would change our conclusion: evidence of AI-native platforms achieving enterprise-grade governance at half the implementation cost, or a sustained deceleration in cloud migration among SMEs. Either would shift the balance from governance-led to interface-led value capture.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.1% from 2020-2034 |
| Segmentation |
|
The global self service analytics market was valued at approximately USD 5.5 billion in 2025 and is estimated at USD 6.1 billion in 2026. Forecasts project expansion to nearly USD 14.5 billion by 2036 at a 9.1% CAGR.
Consensus growth sits at 9.1% CAGR for 2026–2036 on a conservative, services-inclusive basis. More aggressive narrower-window estimates reach 15.9%, driven by the steepest portion of the cloud migration curve.
North America leads with roughly 37% of global revenue, supported by enterprise cloud maturity and analytics-native operating models. Asia Pacific is the fastest-growing region, led by China at 8.7% and Japan at 9.2% CAGR.
Leading vendors include Tableau (Salesforce), Microsoft Power BI, Qlik, SAP, IBM, Oracle, Sisense, Domo, and Looker (Google). Competition is shifting from visualization features to governed semantic layers and AI-assisted query.
Cloud platforms remove upfront hardware investment, scale with usage, and support distributed and hybrid teams. This lowers the entry barrier for small and medium enterprises, which are the fastest-growing adopter segment in the category.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the analytics value chain with enterprise software vendors, cloud platform providers, systems integrators, embedded-analytics ISVs, and enterprise end users. Decision-maker designations interviewed include Chief Data Officers, VP-level Analytics and BI leaders, Heads of Data Governance, and Commercial Operations Leads responsible for tool procurement and adoption.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Data & Analytics Officers | 40% |
| Data Governance & Compliance Leads | 30% |
| IT Procurement & Commercial Operations | 30% |
| Company Type | Representation (%) |
|---|---|
| Enterprise Software Vendors & Platforms | 40% |
| Cloud & Embedded Analytics ISVs | 30% |
| Systems Integrators & Services | 30% |
Secondary validation draws on official multilateral and standards databases, including UN Comtrade, WTO statistics, US ITC data, and Eurostat, alongside corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized non-profit technical standards bodies and industry associations. No third-party market-research publisher data is cited as primary evidence.
Market sizing applies simultaneous top-down and bottom-up triangulation. Top-down allocation begins with macroeconomic software spending and industry segment distribution; bottom-up modeling uses license deployment volumes, seat and usage pricing, and end-use consumption intensity across business functions. Divergence between the two tracks is reconciled at the segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up license and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |