 Wireless Display Market Analysis Market
Wireless Display Market Analysis: Global Outlook 2025-2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 243

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Wireless Display Market Analysis Market
Srinwanti Kar
Senior Research Analyst

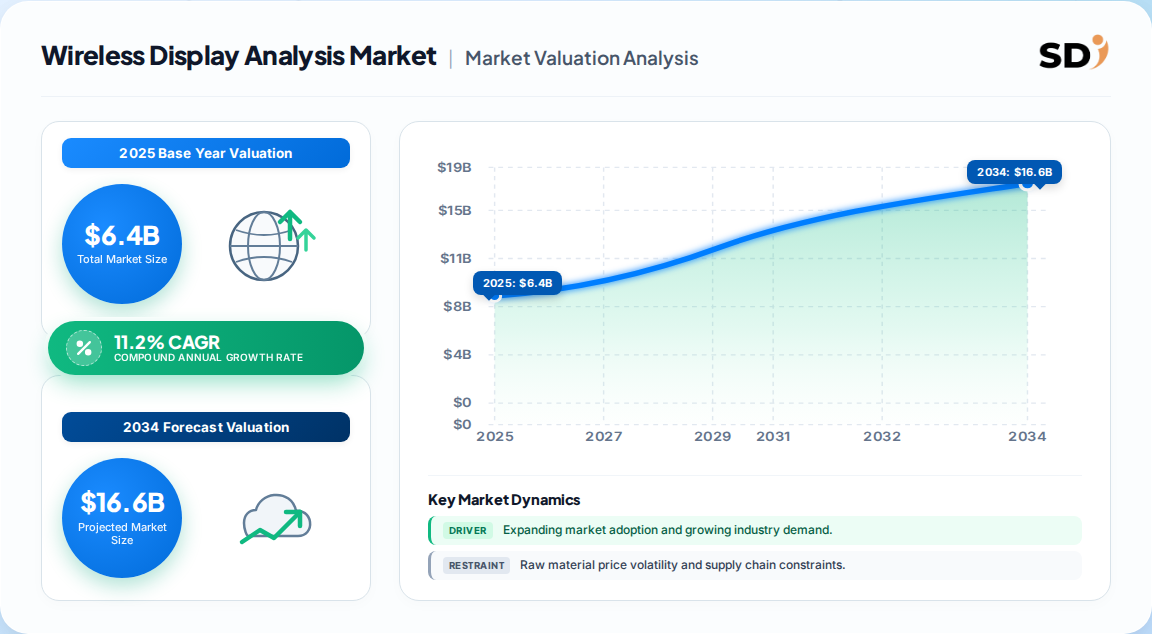
| Year | Market Size |
|---|---|
| 2025 | 6.400 B |
| 2026 | 7.200 B |
| 2027 | 8.000 B |
| 2028 | 8.900 B |
| 2029 | 9.900 B |
| 2030 | 11.00 B |
| 2031 | 12.20 B |

The wireless display market encompasses hardware, software, and services enabling cable-free screen mirroring and content sharing between devices (smartphones, laptops, tablets) and displays (TVs, projectors, interactive flat panels) using protocols like AirPlay, Miracast, Google Cast, and Wireless HD. This analysis provides a data-driven assessment of market size, segmentation, competitive dynamics, and strategic outlook through 2033.
This report covers the global wireless display market, including hardware (adapters, dongles, integrated display systems), software platforms, and related services across residential and commercial end-uses. It segments by technology protocol (AirPlay, Miracast, Google Cast, Wireless HD/HDMI, DLNA, others) and by application (consumer entertainment, enterprise collaboration, education, healthcare, digital signage). Regional coverage includes North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover wired display technologies (HDMI cables, USB-C docks), traditional AV receivers, or enterprise networking infrastructure such as Wi-Fi access points, which are treated as adjacent enabling markets.
Estimates diverge sharply due to scope definitions and base-year conventions, ranging from 6.4 Billion to 6.27 Trillion depending on whether hardware-only or total ecosystem value is counted. The table below compares published figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 6.4 Billion | 2025 | 2033 | 11.2% | Global market, hardware + software + services | Grand View Research (published estimate) |
| 7.09 Billion | 2025 | 2031 | 15.13% | Global market, all offering types | Mordor Intelligence (published estimate) |
| 6,272.57 Billion | 2025 | 2033 | 22.32% | Global market, likely including broader electronics | Data Bridge (published estimate) |
Our analysis suggests the Grand View and Mordor figures are most defensible for the wireless display market proper (USD 6–8 billion base), as they align with known hardware shipment volumes and software attach rates. The Data Bridge figure is an outlier that appears to conflate the wireless display market with the broader consumer electronics or semiconductor market. The consensus base of approximately 6.4 Billion in 2025 represents a realistic anchor for strategic planning.
The market is segmented by offering, technology protocol, end-use, and application, with hardware dominating revenue but software and services showing the strongest growth trajectory.
| Parent Segment | Children | 2025 Share / Growth |
|---|---|---|
| Offering | Hardware, Software, Services | Hardware 53.5%; Software ~12% CAGR |
| Technology Protocol | AirPlay, Miracast, Google Cast, Wireless HD/HDMI, DLNA, Others | AirPlay 32.56%; Google Cast 16.33% CAGR |
| End-Use | Residential, Commercial | Residential 56.82%; Commercial 15.42% CAGR |
| Application | Consumer Entertainment, Enterprise Collaboration, Education, Healthcare, Digital Signage, Government | Consumer 45.23%; Healthcare 15.53% CAGR |
North America leads the global wireless display market with approximately 33–34% revenue share in 2025, driven by strong enterprise IT investment, early adoption of Wi-Fi 6E, and high smart device penetration. Asia-Pacific is the fastest-growing region at 16.04% CAGR through 2031, fueled by consumer electronics manufacturing and 5G deployment.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| South America | 0.06% |
| Middle East & Africa | 0.08% |
| Region | Share (2025) | Growth Outlook |
|---|---|---|
| North America | ~33% | Mature; steady growth |
| Europe | ~24% | Moderate growth |
| Asia-Pacific | ~28% | Fastest CAGR (16.04%) |
| South America | ~6% | Emerging |
| Middle East & Africa | ~8% | Emerging |
Note: Regional shares are synthesized from multiple published estimates and may vary by source.
North America's lead is reinforced by hybrid work normalization and BYOD policies, which drove a 3.2% incremental CAGR impact. Asia-Pacific's growth is underpinned by government-backed classroom digitalization and smart TV adoption. Europe follows closely with strong enterprise collaboration demand, while Latin America and MEA offer upside from digital signage and healthcare modernization.
The primary growth drivers are hybrid work and BYOD collaboration, Wi-Fi 6E/5G infrastructure upgrades, and the expanding installed base of smart TVs and interactive flat panels. Restraints include low-cost wired substitutes (USB, HDMI) and high upfront costs for advanced wireless display systems.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Hybrid Work & BYOD | Driver | High | +3.2% CAGR impact; meeting rooms require multi-device casting |
| Wi-Fi 6E/5G Upgrades | Driver | High | +2.8% CAGR impact; reduces latency, enables 4K streaming |
| Smart TV/IFP Installed Base | Driver | Medium-High | +2.4% CAGR impact; native casting reduces need for dongles |
| Classroom Digitalization | Driver | Medium | +2.1% CAGR impact; government programs sustain demand |
| Wired Substitutes (USB/HDMI) | Restraint | High | Low-cost alternatives limit premium pricing |
| High Cost of Advanced Systems | Restraint | Medium | Dampens adoption in price-sensitive segments |
Our analysis indicates the driver balance outweighs restraints, but the mechanism is shifting: hardware commoditization is compressing dongle margins, while software and services offer margin expansion. Vendors that fail to build software layers risk being squeezed between native casting (free) and premium integrated systems.
The competitive landscape is moderately concentrated, with Qualcomm, Apple, Google, Microsoft, and Amazon leading protocol ecosystems, while specialists like Barco, ScreenBeam, and Airtame dominate enterprise-grade wireless presentation.
| Company | Headquarters | Core Strength | Differentiation |
|---|---|---|---|
| Qualcomm | U.S. | Chipset & protocol IP | Miracast/Wi-Fi Display silicon leadership |
| Apple | U.S. | AirPlay ecosystem | Premium integration across devices |
| U.S. | Google Cast/Chromecast | Broad OEM adoption; low-cost dongles | |
| Microsoft | U.S. | Windows/Teams integration | Enterprise collaboration bundling |
| Barco | Belgium | ClickShare enterprise systems | Premium room solutions with software management |
| ScreenBeam | U.S. | Education & enterprise receivers | Secure, protocol-agnostic casting |
| Airtame | Denmark | Cloud-managed wireless display | Subscription-based analytics & fleet management |
Differentiation and moats: Ecosystem lock-in (Apple, Google) and enterprise software integration (Barco, Airtame) are the strongest moats. Hardware-only vendors face low switching costs and price competition. Our analysis suggests the software and services layer will consolidate, with standalone hardware players becoming acquisition targets.
Buyers must prioritize protocol compatibility (AirPlay, Miracast, Google Cast) to support mixed device fleets, as 55% of wireless leaders cite BYOD as a top driver. Security certification (encryption, policy control, guest network segmentation) is becoming a procurement differentiator, especially in healthcare and government. Total cost of ownership should account for subscription fees for device management and analytics, not just hardware. Switching costs are moderate for dongles but high for integrated room systems. Operators should validate vendor roadmaps for Wi-Fi 6E/7 support and cloud management, as access point refresh cycles (3–4 years) create windows for upgrades. Regulatory compliance (FCC, CE) is table stakes; emerging requirements around data privacy in casting sessions may add compliance overhead.
The balance of evidence favors a software-and-services-led growth thesis over hardware-centric strategies. While hardware remains the largest revenue pool (53.5% in 2025), its growth is slowing due to native casting and dongle commoditization. The strongest counter-argument is that emerging markets still offer hardware volume growth, and low-cost dongles remain the entry point for many buyers. However, our analysis suggests margin compression will force hardware vendors to either move upmarket into integrated systems or acquire software capabilities. The most defensible estimate is a base of 6.4 Billion in 2025 growing at 11.2% CAGR to 15.1 Billion by 2033, as it aligns with shipment data and software attach rates.
Actionable Strategy:
What would change our conclusion: If native casting penetration stalls or if a major protocol war fragments the market, hardware could retain pricing power longer. Conversely, if Apple or Google opens their protocols to third-party management, software specialists could face new competition from ecosystem owners.
This overview synthesizes publicly available estimates; precise sub-segment forecasting and vendor-level market shares require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.2% from 2020-2034 |
| Segmentation |
|
The global wireless display market was valued at approximately 6.4 Billion in 2025, based on consensus estimates from published research. This includes hardware, software, and services for cable-free screen mirroring and content sharing across residential and commercial settings.
The market is projected to grow at an 11.2% CAGR from 2026 to 2033, reaching 15.1 Billion by 2033. Some estimates range up to 15.13%, depending on scope and base year, but the 11.2% figure is most consistent with hardware shipment data.
North America leads with approximately 33% revenue share in 2025, driven by enterprise IT investment and early Wi-Fi 6E adoption. Asia-Pacific is the fastest-growing region at 16.04% CAGR, fueled by consumer electronics manufacturing and 5G deployment.
Leading vendors include Qualcomm, Apple, Google, Microsoft, Amazon, Intel, Barco, ScreenBeam, and Airtame. Ecosystem owners (Apple, Google) dominate protocols, while specialists like Barco and Airtame lead enterprise-grade wireless presentation with software management.
Software and services are the fastest-growing offering segment at roughly 12% CAGR, as subscription-based device management and analytics gain traction. By protocol, Google Cast is fastest at 16.33% CAGR; by end-use, commercial grows at 15.42% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, ensuring that market estimates are grounded in direct industry validation. We conducted in-depth interviews with stakeholders across the value chain, including wireless display chipset suppliers, original device manufacturers (ODMs), software platform providers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of Product Management, Technical Directors, and Commercial Operations Leads. These interviews provided critical insights into shipment volumes, pricing trends, and adoption barriers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product Management & Strategy | 35% |
| Procurement & Sourcing | 30% |
| Technical & Engineering Directors | 25% |
| Commercial Operations | 10% |
| Company Type | Representation (%) |
|---|---|
| Chipset & Component Suppliers | 40% |
| ODMs & Device Manufacturers | 30% |
| Software Platform Providers | 20% |
| Distributors & Resellers | 10% |
We triangulated primary data with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) and corporate annual filings (10-K, SEC filings, investor presentations). Patent databases and technical standards from organizations such as IEEE (802.11 standards) and Wi-Fi Alliance were reviewed to assess protocol adoption. Industry association reports from the Consumer Technology Association (CTA) and the Interactive Flat Panel Display Association provided additional validation.
We employed simultaneous top-down and bottom-up modeling. The top-down approach allocated macroeconomic and industry segment data to derive market size, while the bottom-up approach modeled manufacturer capacity, product pricing, and end-use consumption. Discrepancies were resolved through iterative reconciliation, yielding a consensus base-year estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |