Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
AI Dentistry Market Size, Share & Growth Forecast 2026
AI Dentistry Market
AI Dentistry Market Size, Share & Growth Forecast 2026
AI Dentistry Market by Solution Type (AI-Powered Diagnostic Software, Patient Communication & Engagement Software, Practice Management Software, Treatment Planning Software), by Technology (Computer Vision, Machine Learning, Natural Language Processing, Generative AI), by Clinical Application (General Dentistry, Orthodontics, Implant Dentistry, Restorative Dentistry, Prosthodontics, Endodontics), by End User (Dental Clinics, Dental Service Organizations, Dental Laboratories, Academic & Research Institutions), by Distribution Channel (Direct Sales, Online Platforms, Distributors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 259
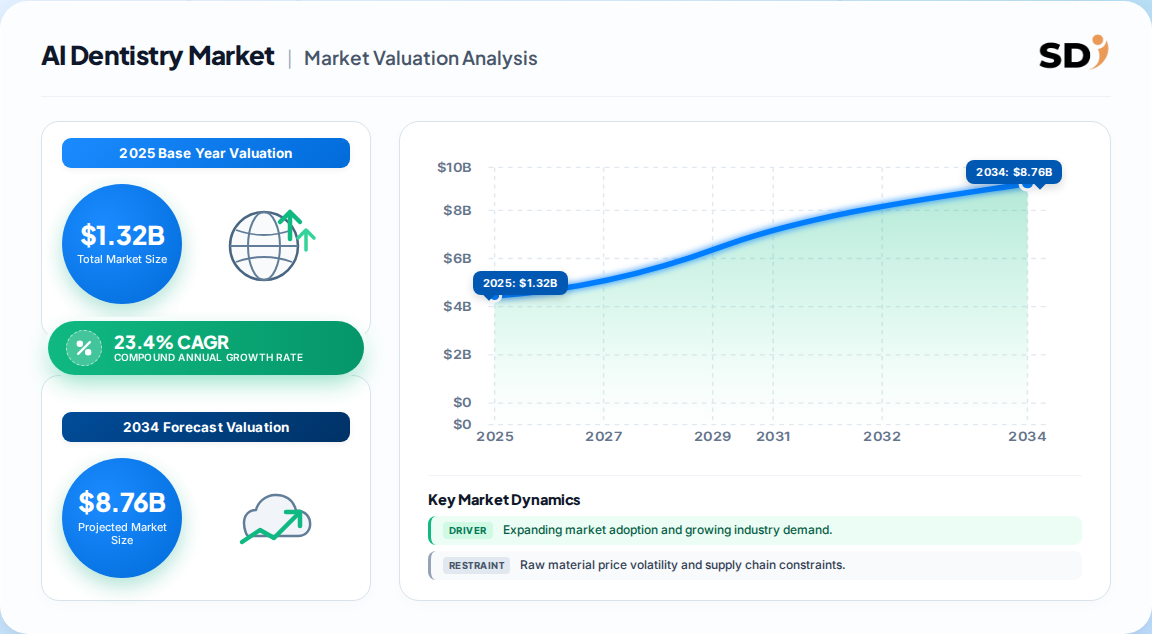
USD 1.32 Billion was the global AI Dentistry Market valuation in 2025, with projections reaching USD 10.81 Billion by 2035 at a 23.4% CAGR.
North America leads with approximately 38% regional share, driven by early FDA clearances and DSO consolidation; Asia Pacific is the fastest-growing region at ~26.5% CAGR.
AI-powered diagnostic software dominates solution segments with roughly 41.5% share, while patient communication software grows fastest at ~28.2% CAGR.
Dental clinics represent the largest end-user base (~67.8%), but Dental Service Organizations (DSOs) are expanding fastest at ~25.4% CAGR.
Leading vendors include Pearl AI, Overjet, VideaHealth, Diagnocat, Align Technology, Dentsply Sirona, and 3Shape, with regulatory clearances becoming a key competitive moat.
Why this matters for decision-makers: Buyers must prioritize vendors with multi-modality FDA clearances (2D and 3D) and interoperability with existing imaging hardware; the shift toward DSO-standardized procurement means solo-practice-focused vendors face margin compression unless they bundle diagnostic capabilities into hardware refresh cycles.
AI Dentistry Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
1.320 B
2025
1.630 B
2026
2.010 B
2027
2.480 B
2028
3.060 B
2029
3.780 B
2030
4.660 B
2031
AI Dentistry Market Size (In Billion)
Year
Market Size
2025
1.320 B
2026
1.630 B
2027
2.010 B
2028
2.480 B
2029
3.060 B
2030
3.780 B
2031
4.660 B
What is the AI Dentistry Market?
The AI Dentistry Market encompasses artificial intelligence technologies integrated into dental diagnostics, treatment planning, imaging analysis, practice management, and patient communication. These solutions apply computer vision, machine learning, and generative AI to radiographs, intraoral scans, and clinical data to improve diagnostic accuracy, streamline workflows, and support evidence-based care delivery.
Scope: what this report covers and excludes
This report analyzes the global AI Dentistry Market across solution types (diagnostic software, patient engagement, practice management), deployment modes (cloud, on-premise), clinical applications (general dentistry, orthodontics, implantology, restorative), dental specialties, and distribution channels. It covers vendor landscapes, regulatory developments, and regional dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. This analysis does not cover conventional dental equipment manufacturing (chairs, handpieces, sterilization units), dental implant hardware, or general healthcare IT systems that lack dental-specific AI functionality.
How big is the market for AI Dentistry Market?
The global AI Dentistry Market was valued between USD 516 Million and USD 1.32 Billion in 2025, depending on scope definition, with a consensus CAGR of approximately 22.5% to 23.4% through 2035. The divergence reflects whether practice management software and teledentistry platforms are included alongside core diagnostic AI.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 559.2 Million
2025
2034
21.78%
AI in dental: diagnostics, imaging, orthodontics software
Published industry estimate
USD 1.32 Billion
2025
2035
23.40%
AI in dentistry: diagnostic software, patient engagement, practice management
Published industry estimate
USD 516.46 Million
2025
2035
22.50%
AI in dentistry: ML, NLP applications across imaging, treatment planning
Published industry estimate
USD 5.48 Billion
2024
2032
12.31%
AI in digital dentistry: equipment + software including scanners, CAD/CAM
Published industry estimate
Our analysis suggests the USD 1.32 Billion figure is most defensible for the pure-play AI Dentistry Market because it captures the full software and platform ecosystem while excluding hardware revenue that inflates the digital dentistry estimate. The lower USD 516–559 Million figures likely reflect narrower definitions focused exclusively on diagnostic imaging software, missing the rapidly growing patient engagement and practice management AI layers that are now material revenue contributors.
How is the market segmented?
The AI Dentistry Market segments across solution type, technology, clinical application, end user, and distribution channel, with diagnostic software and computer vision technology representing the most mature and commercially validated categories.
Parent Segment
Children
By Solution Type
AI-Powered Diagnostic Software, Patient Communication & Engagement Software, Practice Management Software, Treatment Planning Software
By Technology
Computer Vision, Machine Learning, Natural Language Processing, Generative AI
By Clinical Application
General Dentistry, Orthodontics, Implant Dentistry, Restorative Dentistry, Prosthodontics, Endodontics
By End User
Dental Clinics, Dental Service Organizations (DSOs), Dental Laboratories, Academic & Research Institutions
By Distribution Channel
Direct Sales, Online Platforms, Distributors
Which region leads in AI Dentistry Market?
North America leads the AI Dentistry Market with approximately 38% revenue share in 2025, driven by early FDA clearances, high DSO penetration, and strong venture funding for dental AI startups. Asia Pacific is the fastest-growing region at ~26.5% CAGR, fueled by rapid clinic digitization and government healthcare investment.
AI Dentistry Market Regional Market Share
Loading chart...
AI Dentistry Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.31%
Asia-Pacific
0.24%
Latin America
0.04%
Middle East & Africa
0.03%
Region
2025 Share
Growth Outlook
North America
38%
Mature; DSO-driven standardization
Europe
31%
Strong CAD/CAM integration; regulatory clarity
Asia Pacific
24%
Fastest growth; China, India, Japan leading
Latin America
4%
Emerging; teledentistry expansion
Middle East & Africa
3%
Nascent; flagship AI clinic launches
Geography Tree:
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Spain)
Asia Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Argentina, Colombia)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
What is driving growth — and what is holding it back?
Drivers include expanding radiograph volume, insurer adoption of AI-flagged findings for claims processing, DSO standardization demands, and hardware-bundled diagnostic software reducing adoption barriers. Restraints center on regulatory classification burden, fragmented clinic ownership slowing decision cycles, interoperability gaps with legacy systems, and high implementation costs for small practices.
Factor
Direction
Evidence Strength
Mechanism
Insurer adoption of AI claims review
Driver
High
Financial incentive for practices to run all radiographs through AI
Expands addressable clinical use cases beyond 2D radiographs
Regulatory classification uncertainty
Restraint
Medium
Slows vendor go-to-market; limits which products practices adopt
Fragmented solo-practice ownership
Restraint
High
Delays purchasing decisions; waits for equipment refresh cycles
Interoperability with legacy PACS
Restraint
Medium
Integration complexity raises switching costs
Our analysis suggests the balance favors growth substantially, with insurer-driven financial incentives creating a pull-through effect that overrides typical small-practice adoption inertia. The second-order effect: vendors that integrate directly with claims processing workflows will capture disproportionate share as reimbursement alignment becomes the primary purchase trigger rather than diagnostic accuracy alone.
Who are the leading vendors?
The competitive landscape features a mix of pure-play AI diagnostic firms (Pearl, Overjet, VideaHealth, Diagnocat) and incumbent imaging/practice management vendors (Align Technology, Dentsply Sirona, 3Shape, Carestream Dental, Planmeca) embedding AI into existing hardware and software ecosystems.
Company
Primary AI Focus
Regulatory Status
Key Differentiator
Pearl AI
2D/3D radiograph analysis
FDA-cleared for 2D and 3D (May 2025)
First broad multi-modality clearance; ADA strategic investment
Overjet
CBCT, radiograph analysis, claims network
10 FDA clearances (through Dec 2025)
Dental Clarity Network linking diagnostics to insurer workflows
VideaHealth
Caries detection, RCM
FDA-cleared; Caries 3.0 model (Jan 2025)
Deep DSO penetration (8 of 10 largest DSOs)
Diagnocat
AI imaging diagnostics
FDA-cleared
Strong European presence
Align Technology
Orthodontic treatment planning AI
Integrated into ClinCheck platform
1.8M+ active Invisalign users; massive proprietary dataset
Dentsply Sirona
Integrated digital workflows
FDA-cleared components
Full hardware-software ecosystem lock-in
3Shape
Intraoral scanning AI
FDA-cleared components
Scanner hardware dominance; software bundling
Differentiation is increasingly defined by regulatory breadth (number of cleared indications and imaging modalities) and workflow integration depth (claims processing, practice management, hardware bundling). Vendors relying solely on diagnostic accuracy without claims or hardware integration face commoditization risk as incumbents embed equivalent capabilities into existing purchase cycles.
What do buyers and operators need to know?
Procurement decisions in the AI Dentistry Market hinge on four mission-critical criteria: regulatory clearance breadth (multi-modality FDA clearances reduce compliance risk), interoperability with existing imaging hardware and practice management systems (integration complexity is the leading cause of failed deployments), reimbursement alignment (does the vendor connect to insurer claims workflows?), and total cost of ownership including training and workflow disruption. Switching costs are substantial once a practice embeds AI into its diagnostic and documentation workflow, making initial vendor selection a multi-year commitment. Buyers should prioritize vendors with established DSO references and verified integration case studies over diagnostic accuracy claims alone. Regulatory compliance extends beyond FDA clearance to state-level teledentistry regulations and data privacy requirements (HIPAA in the US, GDPR in Europe), particularly for cloud-deployed solutions.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors accelerated adoption through 2030, with the AI Dentistry Market tracking toward USD 3–4 Billion by 2030 before reaching USD 10+ Billion by 2035. The strongest counter-argument is that regulatory fragmentation across geographies and the persistence of small-practice ownership could slow adoption below consensus forecasts, particularly in Europe and Latin America where dental practice consolidation lags North America. However, the insurer-driven pull-through mechanism and DSO standardization trends create structural demand that overrides typical healthcare technology adoption inertia.
Our analysis suggests the most important second-order effect is the convergence of diagnostic AI with revenue cycle management. Vendors that connect radiographic findings directly to claims submission and reimbursement workflows will capture disproportionate value because they align clinical and financial incentives for the first time. Pure diagnostic accuracy vendors without claims integration face commoditization as incumbents (Carestream, Dentsply Sirona, 3Shape) embed equivalent capabilities into hardware refresh cycles. The generative AI layer — currently the fastest-growing technology segment at ~30% CAGR — will further differentiate vendors offering automated clinical notes and patient communication alongside diagnostic tools.
Actionable Strategy:
Investors should prioritize pure-play AI diagnostic vendors with multi-modality FDA clearances and demonstrated DSO penetration, as these represent the most defensible acquisition targets for incumbent imaging manufacturers seeking to embed AI capabilities.
Operators and DSO procurement leads should negotiate multi-year enterprise licensing agreements that bundle diagnostic, patient engagement, and RCM capabilities from a single vendor to minimize integration risk and maximize reimbursement workflow alignment.
Vendors should invest in claims processing integration and generative AI patient communication features to avoid margin compression from diagnostic-only commoditization, and target Asia Pacific DSO chains for early market capture before incumbents establish dominant positions.
Evidence that would change our conclusion: sustained FDA delays for 3D/CBCT AI clearances beyond 2026, or insurer retrenchment from AI-flagged claims review, would materially slow adoption and shift the forecast toward the lower-bound USD 516–559 Million base case trajectory.
AI Dentistry Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
AI Dentistry Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 23.4% from 2020-2034
Segmentation
By Solution Type
AI-Powered Diagnostic Software
Patient Communication & Engagement Software
Practice Management Software
Treatment Planning Software
By Technology
Computer Vision
Machine Learning
Natural Language Processing
Generative AI
By Clinical Application
General Dentistry
Orthodontics
Implant Dentistry
Restorative Dentistry
Prosthodontics
Endodontics
By End User
Dental Clinics
Dental Service Organizations
Dental Laboratories
Academic & Research Institutions
By Distribution Channel
Direct Sales
Online Platforms
Distributors
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Solution Type
5.1.1. AI-Powered Diagnostic Software
5.1.2. Patient Communication & Engagement Software
5.1.3. Practice Management Software
5.1.4. Treatment Planning Software
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Computer Vision
5.2.2. Machine Learning
5.2.3. Natural Language Processing
5.2.4. Generative AI
5.3. Market Analysis, Insights and Forecast - by Clinical Application
5.3.1. General Dentistry
5.3.2. Orthodontics
5.3.3. Implant Dentistry
5.3.4. Restorative Dentistry
5.3.5. Prosthodontics
5.3.6. Endodontics
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Dental Clinics
5.4.2. Dental Service Organizations
5.4.3. Dental Laboratories
5.4.4. Academic & Research Institutions
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Direct Sales
5.5.2. Online Platforms
5.5.3. Distributors
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Solution Type
6.1.1. AI-Powered Diagnostic Software
6.1.2. Patient Communication & Engagement Software
6.1.3. Practice Management Software
6.1.4. Treatment Planning Software
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Computer Vision
6.2.2. Machine Learning
6.2.3. Natural Language Processing
6.2.4. Generative AI
6.3. Market Analysis, Insights and Forecast - by Clinical Application
6.3.1. General Dentistry
6.3.2. Orthodontics
6.3.3. Implant Dentistry
6.3.4. Restorative Dentistry
6.3.5. Prosthodontics
6.3.6. Endodontics
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Dental Clinics
6.4.2. Dental Service Organizations
6.4.3. Dental Laboratories
6.4.4. Academic & Research Institutions
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Direct Sales
6.5.2. Online Platforms
6.5.3. Distributors
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Solution Type
7.1.1. AI-Powered Diagnostic Software
7.1.2. Patient Communication & Engagement Software
7.1.3. Practice Management Software
7.1.4. Treatment Planning Software
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Computer Vision
7.2.2. Machine Learning
7.2.3. Natural Language Processing
7.2.4. Generative AI
7.3. Market Analysis, Insights and Forecast - by Clinical Application
7.3.1. General Dentistry
7.3.2. Orthodontics
7.3.3. Implant Dentistry
7.3.4. Restorative Dentistry
7.3.5. Prosthodontics
7.3.6. Endodontics
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Dental Clinics
7.4.2. Dental Service Organizations
7.4.3. Dental Laboratories
7.4.4. Academic & Research Institutions
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Direct Sales
7.5.2. Online Platforms
7.5.3. Distributors
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Solution Type
8.1.1. AI-Powered Diagnostic Software
8.1.2. Patient Communication & Engagement Software
8.1.3. Practice Management Software
8.1.4. Treatment Planning Software
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Computer Vision
8.2.2. Machine Learning
8.2.3. Natural Language Processing
8.2.4. Generative AI
8.3. Market Analysis, Insights and Forecast - by Clinical Application
8.3.1. General Dentistry
8.3.2. Orthodontics
8.3.3. Implant Dentistry
8.3.4. Restorative Dentistry
8.3.5. Prosthodontics
8.3.6. Endodontics
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Dental Clinics
8.4.2. Dental Service Organizations
8.4.3. Dental Laboratories
8.4.4. Academic & Research Institutions
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Direct Sales
8.5.2. Online Platforms
8.5.3. Distributors
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Solution Type
9.1.1. AI-Powered Diagnostic Software
9.1.2. Patient Communication & Engagement Software
9.1.3. Practice Management Software
9.1.4. Treatment Planning Software
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Computer Vision
9.2.2. Machine Learning
9.2.3. Natural Language Processing
9.2.4. Generative AI
9.3. Market Analysis, Insights and Forecast - by Clinical Application
9.3.1. General Dentistry
9.3.2. Orthodontics
9.3.3. Implant Dentistry
9.3.4. Restorative Dentistry
9.3.5. Prosthodontics
9.3.6. Endodontics
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Dental Clinics
9.4.2. Dental Service Organizations
9.4.3. Dental Laboratories
9.4.4. Academic & Research Institutions
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Direct Sales
9.5.2. Online Platforms
9.5.3. Distributors
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Solution Type
10.1.1. AI-Powered Diagnostic Software
10.1.2. Patient Communication & Engagement Software
10.1.3. Practice Management Software
10.1.4. Treatment Planning Software
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Computer Vision
10.2.2. Machine Learning
10.2.3. Natural Language Processing
10.2.4. Generative AI
10.3. Market Analysis, Insights and Forecast - by Clinical Application
10.3.1. General Dentistry
10.3.2. Orthodontics
10.3.3. Implant Dentistry
10.3.4. Restorative Dentistry
10.3.5. Prosthodontics
10.3.6. Endodontics
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Dental Clinics
10.4.2. Dental Service Organizations
10.4.3. Dental Laboratories
10.4.4. Academic & Research Institutions
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Direct Sales
10.5.2. Online Platforms
10.5.3. Distributors
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: AI Dentistry Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America AI Dentistry Market Revenue (Billion), by Solution Type 2026 & 2034
Figure 3: North America AI Dentistry Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 4: North America AI Dentistry Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America AI Dentistry Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America AI Dentistry Market Revenue (Billion), by Clinical Application 2026 & 2034
Figure 7: North America AI Dentistry Market Revenue Share (%), by Clinical Application 2026 & 2034
Figure 8: North America AI Dentistry Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America AI Dentistry Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America AI Dentistry Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America AI Dentistry Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America AI Dentistry Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America AI Dentistry Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe AI Dentistry Market Revenue (Billion), by Solution Type 2026 & 2034
Figure 15: Europe AI Dentistry Market Revenue Share (%), by Solution Type 2026 & 2034
Figure 16: Europe AI Dentistry Market Revenue (Billion), by Technology 2026 & 2034
List of Tables
Table 1: AI Dentistry Market Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 2: AI Dentistry Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: AI Dentistry Market Revenue Billion Forecast, by Clinical Application 2020 & 2034
Table 4: AI Dentistry Market Revenue Billion Forecast, by End User 2020 & 2034
Table 5: AI Dentistry Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: AI Dentistry Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America AI Dentistry Market Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 8: North America AI Dentistry Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America AI Dentistry Market Revenue Billion Forecast, by Clinical Application 2020 & 2034
Table 10: North America AI Dentistry Market Revenue Billion Forecast, by End User 2020 & 2034
Table 11: North America AI Dentistry Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America AI Dentistry Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA AI Dentistry Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada AI Dentistry Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico AI Dentistry Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe AI Dentistry Market Revenue Billion Forecast, by Solution Type 2020 & 2034
Frequently Asked Questions
1. What is the AI Dentistry Market size in 2025?
The global AI Dentistry Market was valued at approximately USD 1.32 Billion in 2025, with diagnostic software representing the largest solution segment at ~41.5% share. Narrower definitions focused solely on imaging diagnostics estimate USD 516–559 Million.
2. What is the AI Dentistry Market growth rate?
The market is growing at approximately 23.4% CAGR from 2025 to 2035, with Asia Pacific expanding fastest at ~26.5% CAGR and North America maintaining the largest absolute revenue base.
3. Which region leads the AI Dentistry Market?
North America leads with approximately 38% share, driven by early FDA clearances, high DSO penetration, and strong venture funding. Europe follows at ~31%, while Asia Pacific is the fastest-growing region.
4. Who are the leading AI Dentistry Market vendors?
Key vendors include Pearl AI, Overjet, VideaHealth, Diagnocat, Align Technology, Dentsply Sirona, 3Shape, Carestream Dental, and Planmeca. Regulatory clearance breadth and claims workflow integration are the primary competitive differentiators.
5. What is the fastest-growing segment in the AI Dentistry Market?
Patient communication and engagement software is growing fastest at ~28.2% CAGR, while generative AI technology expands at ~30.1% CAGR. Implant dentistry is the fastest-growing clinical application at ~27.3% CAGR.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This report is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the AI dentistry value chain, including imaging hardware manufacturers, AI diagnostic software developers, dental service organization procurement teams, and global distributors of dental technology. Decision-maker designations interviewed included Chief Dental Officers, VP-level procurement leads at DSOs, Heads of Clinical Informatics, and Commercial Operations Directors at AI software vendors. These interviews validated market sizing, adoption timelines, and pricing dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Clinical & Dental Officers
35%
Procurement & Sourcing Leads
30%
Regulatory & Compliance Managers
20%
Commercial Operations Directors
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
AI Diagnostic Software Developers
40%
Imaging Hardware Manufacturers
25%
Dental Service Organizations (DSOs)
20%
Distributors & Practice Management Vendors
15%
Secondary Benchmarking & Public Trade Validation
We cross-referenced official multilateral trade databases (UN Comtrade, WTO), corporate annual filings (SEC 10-K, investor presentations from Align Technology, Dentsply Sirona, and Envista), patent databases (USPTO, EPO), and recognized industry associations including the American Dental Association (ADA), FDI World Dental Federation, and ISO technical committees for dental standards. Regulatory databases including the FDA 510(k) clearance registry were analyzed to track AI product approvals.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous top-down (macroeconomic dental expenditure allocation, digital dentistry penetration rates) and bottom-up (vendor revenue aggregation, procedure volume modeling, per-practice software licensing estimates) triangulation methodologies. Cross-validation against publicly disclosed vendor revenue and DSO adoption metrics ensured internal consistency across segment and regional estimates.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for 2025
Bottom-up vendor revenue and DSO licensing triangulation


 AI Dentistry Market