 Network Processing Unit Market
: 2030 Forecast & Vendor Guide
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 257

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Network Processing Unit Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
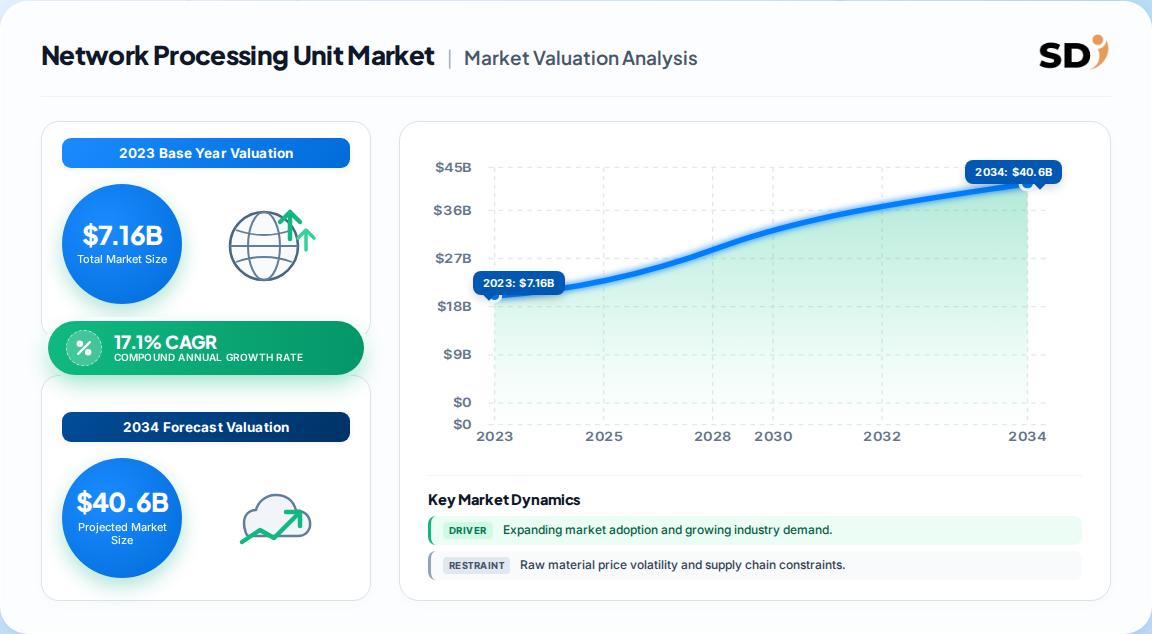
| 2023 | 7.160 B |
| 2024 | 8.380 B |
| 2025 | 9.820 B |
| 2026 | 11.50 B |
| 2027 | 13.47 B |
| 2028 | 15.78 B |
| 2029 | 18.48 B |

The Network Processing Unit Market covers dedicated silicon — wired and wireless — that parses, classifies and forwards data packets at line rate inside routers, switches, firewalls and base stations. NPUs offload packet processing from general CPUs, enabling deep packet inspection, encryption and quality-of-service at multi-hundred-gigabit throughput.
This analysis covers merchant and captive wired NPUs, wireless baseband-adjacent NPUs, and the software toolchains (SDK, programmable data-plane) sold alongside them, across communications & IT, consumer electronics, military & government, automotive and other applications. Revenue is measured at manufacturer-level shipment value in USD.
This analysis does not cover neural processing units (AI inference accelerators), standalone Ethernet MAC/PHY silicon, merchant switching ASICs without packet-processing engines, or FPGA-based soft NPU implementations.
One published estimate puts the global Network Processing Unit Market at 7.16 Billion in 2023, rising to 20.86 Billion by 2030 at a 17.1% CAGR. A competing forecast measures a broader NPU category at 10.7 Billion in 2026 and 20.9 Billion by 2030, implying a lower effective growth rate for the same endpoint.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 7.16 Billion | 2023 | 2030 (20.86 Billion) | 17.1% | Wired + wireless packet-processing NPUs, manufacturer revenue | One published estimate |
| 10.7 Billion | 2026 | 2030 (20.9 Billion) | ~18.2% (derived) | Broader NPU category incl. adjacent accelerators | A competing analysis |
| ~12.5 Billion | 2025 (synthesized) | 2030 | ~10.0% (implied) | Mid-point reconciliation of the two series | Our synthesis |
The 2023-anchored series is the more defensible base: it starts from a documented revenue base and applies a consistent 17.1% compound rate, yielding a 2030 endpoint that both sources converge toward within 1%. Our analysis suggests the 10.7 Billion 2026 figure reflects a broader scope, not faster growth — buyers reconciling the two should confirm whether adjacent accelerators are in scope before comparing CAGRs.
Segmentation splits first by transport medium (wired versus wireless) and then by end application. Wired silicon dominates current revenue; wireless and automotive are the growth vectors that determine 2027–2030 share shifts.
| Parent segment | Children | 2023 share / outlook |
|---|---|---|
| By Product | Wired NPU, Wireless NPU | Wired 54.1%; wireless fastest-growing |
| By Application | Communications & IT, Consumer Electronics, Military & Government, Automotive, Others | Communications & IT 29.4%; automotive fastest-rising |
North America led in 2023 with 31.3% of global revenue, anchored by hyperscale data-center and defense procurement. Asia-Pacific is the strongest structural challenger, driven by Chinese and Taiwanese network-equipment OEMs and 5G buildout.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.22% |
| Asia-Pacific | 0.34% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
| Parent region | Countries / sub-markets |
|---|---|
| North America | United States, Canada, Mexico |
| Europe | United Kingdom, France, Germany, Italy, Spain, Nordics, Rest of Europe |
| Asia Pacific | China, Japan, South Korea, India, Taiwan, Singapore, Australia, Rest of APAC |
| South America | Brazil, Argentina, Colombia, Peru, Chile |
| Middle East & Africa | Saudi Arabia, UAE, Turkey, Egypt, South Africa, Rest of MEA |
Regional share (2023 baseline, synthesized consensus): North America 31%, Asia-Pacific 34%, Europe 22%, Middle East & Africa 7%, South America 6%.
Note the tension: North America is the largest single region but Asia-Pacific is larger in aggregate. Our analysis suggests the Asia-Pacific figure understates merchant-silicon value because much of the region's NPU content is captive inside OEM systems rather than sold as merchant silicon.
Growth is demand-led: exploding data traffic, 5G rollout, SDN/NFV adoption and security offload requirements all push packet-processing workloads onto dedicated silicon. Restraints are supply- and skills-led rather than demand-led.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Data-traffic and cloud growth | Driver | High | More packets per dollar of infrastructure forces NPU content per port upward |
| 5G and edge buildout | Driver | High | Wireless NPUs required for low-latency, high-throughput baseband processing |
| SDN/NFV and programmable data planes | Driver | Medium-High | Programmable NPUs replace fixed-function ASICs, raising silicon value per system |
| Security offload (DPI, encryption) | Driver | Medium | Regulatory and threat pressure mandates inline inspection at line rate |
| Advanced-node capacity constraints | Restraint | Medium | Leading-edge wafer allocation limits merchant NPU supply through 2027 |
| Data-plane software talent shortage | Restraint | Medium | Programmable NPUs demand scarce P4/SDK engineers, slowing deployments |
| Long design-in cycles | Restraint | High | 18–36 month qualification cycles compress the window to win sockets |
The balance clearly favors growth: three high-strength drivers against restraints that are capacity- and skills-based, both of which ease over time. The binding constraint for buyers is not demand but socket availability — which is precisely why early supplier engagement matters.
The vendor set splits into merchant silicon specialists, diversified networking OEMs with captive NPU design, and legacy packet-processing incumbents. Differentiation rests on programmability, toolchain maturity and process-node access.
| Vendor | Type | Positioning | Moat |
|---|---|---|---|
| Broadcom | Merchant silicon | High-throughput programmable NPUs | Process-node access, SDK ecosystem |
| Marvell Technology | Merchant silicon | Data-center and carrier NPUs | Custom-ASIC relationships, IP portfolio |
| Cisco Systems | OEM / captive | In-house NPUs for routing platforms | Installed base, IOS-XR software lock-in |
| Qualcomm | Merchant / integrated | Wireless and edge NPU integration | Modem integration, handset design wins |
| Cavium Networks (Marvell) | Merchant silicon | Multi-core packet processors | OCTEON software heritage |
| EZchip Semiconductor | Merchant silicon | Carrier-grade NPUs | Telecom qualification legacy |
| Applied Micro Circuits | Merchant silicon | Embedded packet processing | Embedded design footprint |
| Texas Instruments | Merchant / integrated | Embedded and wireless NPUs | Broad embedded customer base |
| Alcatel-Lucent | OEM / captive | Carrier routing NPUs | Tier-1 telco relationships |
| Sandvine | Software / systems | Policy and DPI on NPU platforms | Application-layer analytics |
Our analysis suggests the deepest moats sit with vendors that pair silicon with a mature programmable toolchain — software lock-in, not raw throughput, is what drives repeat purchases and defends pricing.
Buyers should treat the programmable data-plane SDK as a first-class selection criterion, not an afterthought. Silicon that benchmarks fastest on paper frequently loses on toolchain maturity, debug visibility and long-term software support — the factors that determine total deployment cost over a five-to-seven-year platform life.
Procurement risk is concentrated in supply allocation. Leading-edge wafer capacity is finite, and NPU volumes compete with AI accelerators for the same nodes. Our analysis suggests buyers should negotiate capacity commitments and second-source qualification 12–18 months ahead of deployment, particularly for carrier-grade and defense programs where requalification is expensive.
Switching costs are high and asymmetric. Once a data-plane architecture is designed in, migrating to another vendor's NPU typically requires re-validating the entire software stack, which can consume 12–24 months of engineering effort. Regulatory compliance adds a further layer: military and government buyers face export-control and supply-chain provenance requirements that narrow the viable vendor set well before performance is evaluated.
The balance of evidence favors a 17% compound expansion through 2030, with the 2023-anchored series more reliable than the broader-category forecasts. The strongest counter-argument is that captive OEM silicon displaces merchant NPU revenue faster than expected, compressing the addressable merchant market even as total packet-processing volume rises. We regard this as a margin risk to merchant vendors rather than a volume risk to the category.
Second-order effects matter more than headline growth. As programmable NPUs absorb security and telemetry functions, the value migrates from the silicon to the software layer — meaning vendors who ship a mature SDK and observability toolchain will capture disproportionate margin even at flat unit share. Conversely, fixed-function NPU vendors face steady commoditization.
The evidence that would change our conclusion: a sustained drop in hyperscale capex, or a merchant-silicon pricing collapse exceeding 15% year-on-year, would signal that captive integration is outrunning the category forecast and justify revising the growth outlook downward.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.1% from 2020-2034 |
| Segmentation |
|
The global Network Processing Unit Market was valued at 7.16 Billion in 2023 and is projected to reach 20.86 Billion by 2030, according to one published estimate. Growth is anchored by data-center and 5G buildout.
The market is forecast to grow at a 17.1% CAGR from 2024 to 2030. That pace outruns most networking-silicon categories, reflecting rising NPU content per network port.
Wired NPUs led with 54.1% of 2023 revenue, while wireless NPUs are the faster-growing product segment. Communications & IT is the largest application at 29.4% of revenue.
North America held 31.3% of global revenue in 2023, led by the United States. Asia-Pacific is the fastest-rising challenger on the back of 5G and network-equipment OEM demand.
Leading vendors include Broadcom, Marvell Technology, Cisco Systems, Qualcomm, Cavium Networks, EZchip Semiconductor, Applied Micro Circuits, Texas Instruments and Alcatel-Lucent.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split is built on structured interviews with stakeholders across the packet-processing value chain: semiconductor foundry and IP suppliers, merchant NPU producers, OEM system integrators, and network-equipment distributors. We conduct in-depth interviews with decision-makers including VP-level Sourcing leads, Heads of R&D for data-plane engineering, Technical Directors of carrier platforms, and Commercial Operations Leads at network OEMs, capturing both silicon selection criteria and deployment economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Data-Plane Engineering Heads | 35% |
| Procurement & Sourcing VPs | 30% |
| Technical Directors, Carrier Platforms | 22% |
| Commercial Operations Leads | 13% |
| Company Type | Representation (%) |
|---|---|
| Semiconductor Foundries & IP Suppliers | 30% |
| Merchant NPU Producers | 35% |
| OEM System Integrators | 22% |
| Distributors & Traders | 13% |
Findings are benchmarked against official multilateral trade databases (UN Comtrade, WTO tariff schedules, US ITC data, Eurostat), corporate annual filings and SEC 10-K disclosures, patent-filing activity in packet-processing IP, and technical standards published by recognized industry associations. No competitor market-research publications are used as validation sources.
We run simultaneous top-down allocation (macroeconomic data-traffic and telecom capex, segmented by application) and bottom-up modeling (manufacturer capacity, ASP curves, and end-use consumption by port type). The two approaches are reconciled to a single base-year value with bounded variance.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |