 Global Telecom Network Market
 Outlook 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 249

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Global Telecom Network Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.096 M |
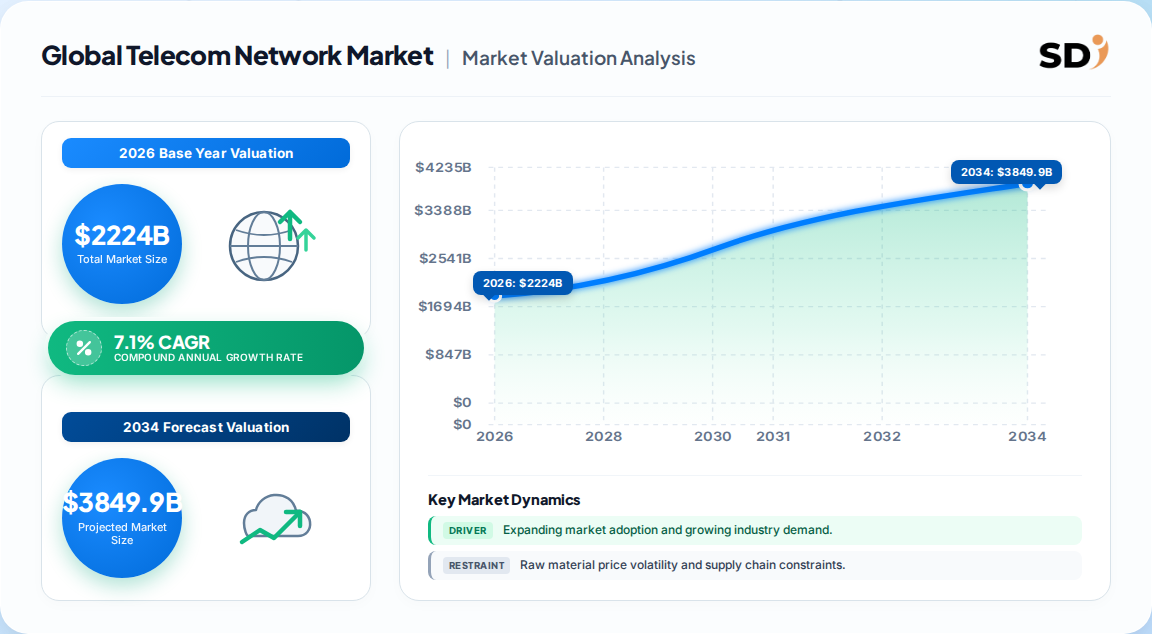
| 2026 | 2.224 M |
| 2027 | 2.383 M |
| 2028 | 2.552 M |
| 2029 | 2.734 M |
| 2030 | 2.928 M |
| 2031 | 3.136 M |

The global telecom network market encompasses the infrastructure, services, and connectivity solutions that enable voice, data, and video transmission across wireless and wireline networks. It includes mobile and fixed data services, network equipment, and managed services delivered by operators and vendors to consumers and enterprises worldwide.
This report covers telecom services and network infrastructure across mobile, fixed, and converged networks, segmented by service type, transmission technology, end-use, and region. It includes revenue from connectivity, value-added services, and associated hardware. This analysis does not cover adjacent markets such as data center infrastructure, cloud computing platforms, or consumer electronics manufacturing.
Estimates for the global telecom network market vary due to differences in scope and methodology, but the most defensible figure places the 2026 market at approximately 2224 Billion, with a 7.1% CAGR through 2033.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2095.7 Billion | 2025 | 2033 | 7.1% | Telecom services revenue only | One published estimate |
| 1900 Billion | 2025 | 2030 | 5.23% | Telecom services, broader definition | A competing analysis |
| 95.2 Billion | 2022 | 2032 | 5.8% | Network infrastructure equipment only | Another published estimate |
Our analysis favors the 7.1% CAGR figure for the services-led market, as it aligns with observed 5G rollout momentum and enterprise digitization trends. The infrastructure-only estimate is narrower in scope and excludes the larger services revenue pool. The divergence between 7.1% and 5.23% reflects differing assumptions on ARPU recovery and enterprise adoption rates, with the higher figure more consistent with current operator capex guidance.
The market segments primarily by service type, transmission technology, and end-use, with mobile data and wireless transmission dominating current revenue.
| Parent Segment | Children |
|---|---|
| Service Type | Mobile Data Service, Fixed Internet Access Service, Voice Services, Pay TV & OTT Services |
| Transmission | Wireline, Wireless |
| End-use | Consumer/Residential, Business |
Mobile data services account for 34.5% of revenue, driven by smartphone penetration and 5G adoption. Wireless transmission holds 78.6% share, reflecting the global shift away from fixed-line infrastructure. The business segment, while smaller, is growing at 8.23% CAGR as enterprises adopt private 5G and IoT connectivity.
Asia-Pacific leads the global telecom network market with 34–40% revenue share, driven by aggressive 5G rollouts in China, India, and Southeast Asia. China alone represents the largest country market, supported by state-backed infrastructure investment and rapid smartphone adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.26% |
| Europe | 0.22% |
| Asia-Pacific | 0.4% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Parent Region | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain |
| Asia-Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Nigeria |
Asia-Pacific's dominance is underpinned by 2.1 billion unique mobile subscribers projected by 2030 and mobile technologies adding USD 880 billion to regional GDP. North America and Europe follow, with growth focused on 5G standalone upgrades and fiber expansion. Emerging markets in Africa and Latin America offer long-term upside but face infrastructure funding constraints.
Growth is primarily driven by 5G rollout, enterprise digitization, and rising mobile data consumption, while price competition and spectrum costs constrain margins.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Mobile internet and smartphone penetration | Driver | High | Expands subscriber base and data usage |
| Rapid 5G/FWA rollouts | Driver | High | Lifts ARPU and monetizes idle spectrum |
| Enterprise digitization and IoT demand | Driver | High | Creates new revenue streams in private 5G |
| Industrial-campus private 5G uptake | Driver | Medium | Enables ultra-reliable low-latency applications |
| Intense price wars and SIM-only churn | Restraint | High | Erodes margins and slows upgrade cycles |
| Rising spectrum auction costs | Restraint | Medium | Diverts capital from network innovation |
Our analysis suggests the balance favors growth, with drivers adding an estimated 5.4 percentage points to CAGR versus 2.2 points from restraints. However, the net positive is unevenly distributed: operators in mature markets face sharper price competition, while those in Asia-Pacific and Africa benefit from subscriber growth. The key uncertainty is how quickly enterprise private 5G scales beyond early adopters like BMW and Tesla.
The competitive landscape includes telecom operators and network infrastructure vendors, with consolidation and convergence shaping market dynamics.
| Company | Type | Key Strengths |
|---|---|---|
| AT&T | Operator | Extensive fiber and 5G footprint in North America |
| Verizon | Operator | FWA leadership and enterprise solutions |
| Vodafone | Operator | European and African market presence |
| Reliance Jio | Operator | Low-cost data and rapid Indian market penetration |
| Bharti Airtel | Operator | Strong emerging market position |
| Ericsson | Infrastructure | 5G RAN and network slicing technology |
| Nokia | Infrastructure | End-to-end network solutions |
| Huawei | Infrastructure | Cost-competitive equipment, strong in Asia |
| Cisco | Infrastructure | Cloud and edge networking |
Operators differentiate through network quality, spectrum holdings, and bundling strategies, while infrastructure vendors compete on technology leadership and cost. The Vodafone–Three UK merger signals consolidation pressure, and operators increasingly partner with cloud providers to offer edge services. Our analysis indicates that vendors with strong private 5G portfolios and AI-driven network optimization capabilities will capture disproportionate share of enterprise growth.
Buyers and operators must prioritize vendors with proven 5G standalone capabilities, strong security credentials, and flexible commercial models to mitigate procurement risks. Mission-critical selection criteria include network reliability, latency performance, and interoperability with existing infrastructure. Switching costs are high due to long-term contracts and integration complexity, so buyers should negotiate exit clauses and performance guarantees. Regulatory compliance varies by region: spectrum licensing and data sovereignty requirements demand careful legal review. Operators should also assess total cost of ownership over a 5–7 year horizon, factoring in spectrum renewal costs that exceeded USD 80 billion globally in 2024.
The balance of evidence favors a positive outlook for the global telecom network market, with the 7.1% CAGR scenario more defensible than conservative estimates. The strongest counter-argument is that price wars and spectrum costs could compress margins faster than expected, particularly in mature markets. However, enterprise digitization and private 5G offer a credible offset, and operators that pivot to value-added services will outperform connectivity-only peers.
Our analysis suggests three actionable strategies: First, investors should focus on operators with clear private 5G roadmaps and enterprise partnerships. Second, vendors should prioritize AI-optimized network slicing to capture incremental revenue valued at USD 200 billion by Ericsson. Third, operators should pursue convergence strategies—bundling fiber and mobile—to reduce churn and stabilize ARPU.
The evidence that would change our conclusion: a sustained decline in enterprise 5G adoption or a sharp increase in spectrum costs beyond current forecasts. Until then, the market offers attractive opportunities for those positioned at the intersection of connectivity and enterprise digital transformation.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.1% from 2020-2034 |
| Segmentation |
|
The global telecom network market was valued at approximately 2224 Billion in 2026 and is projected to reach 3584 Billion by 2033, growing at a 7.1% CAGR.
Asia-Pacific leads with a 34–40% revenue share, driven by aggressive 5G rollouts and high mobile penetration in China and India.
Growth is driven by 5G deployment, rising smartphone adoption, enterprise digitization, and demand for private 5G networks.
Major operators include AT&T, Verizon, Vodafone, Reliance Jio, and Bharti Airtel, alongside infrastructure vendors like Ericsson, Nokia, and Huawei.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring robust validation through direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including network equipment manufacturers, telecom operators, enterprise end-users, and managed service providers. Decision-maker interviews included VP of Network Strategy, Heads of Procurement, Technical Directors, and Commercial Operations Leads, capturing perspectives from both supply and demand sides.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Network Strategy | 30% |
| Procurement Directors | 30% |
| Technical Directors | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Telecom Operators | 40% |
| Network Equipment Vendors | 35% |
| Enterprise End-Users | 15% |
| Managed Service Providers | 10% |
We validated findings against official multilateral trade databases (UN Comtrade, WTO), corporate annual filings (10-K, SEC), patent databases, and recognized industry associations such as GSMA and IEEE. These sources provided critical cross-checks for market sizing, technology adoption rates, and competitive intelligence.
Our approach triangulates data through simultaneous top-down (macroeconomic and segment allocation) and bottom-up (operator revenue, equipment shipments, and pricing) modeling. This dual methodology ensures consistency and reduces estimation bias.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis | High |
| Competitive Landscape | Leading market players | Annual reports and capacity mapping | High |