 Dataops Platform Market
DataOps Platform Market Size, Share & Forecast 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 215

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dataops Platform Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2023 | 4.200 B |
| 2024 | 4.970 B |
| 2025 | 5.800 B |
| 2026 | 7.110 B |
| 2027 | 8.710 B |
| 2028 | 10.67 B |
| 2029 | 13.07 B |

The DataOps platform market covers software and services that operationalize data delivery — automating pipeline orchestration, testing, observability, lineage and governance across cloud, on-premises and hybrid environments. It applies DevOps principles (CI/CD, versioning, monitoring) to data workflows, shortening the path from raw data to governed, AI-ready analytical products.
This global analysis covers DataOps platforms and associated implementation, managed and professional services across all deployment models (cloud, on-premises, hybrid) and enterprise sizes. It segments by component, deployment, type and end-user vertical. This analysis does not cover standalone ETL tools, pure data-catalog software, BI/analytics platforms, MLOps-only platforms, or general cloud infrastructure spending except where bundled into DataOps offerings.
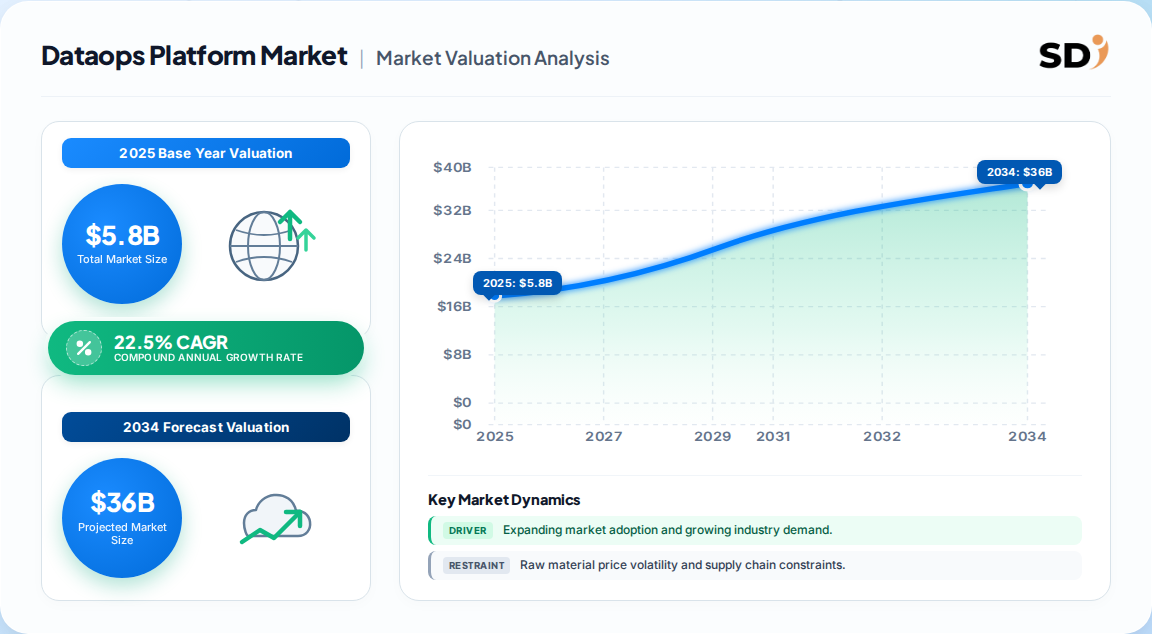
Published 2025 valuations cluster tightly around USD 4.9–5.97 billion, but forward projections diverge sharply because analysts use different base years and scopes — some count platforms only, others include services and managed offerings. The table below reconciles the competing views.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 4.2B | 2023 | 2030 (USD 17.1B) | 22.5% | Platforms + services, all deployments | One published estimate |
| USD 5.8B | 2025 | 2035 (USD 36.1B) | 19.25% | Platforms + services, hybrid-weighted | A competing analysis |
| USD 7.72B | 2026 | 2031 (USD 27.91B) | 29.31% | DataOps software incl. managed services | A competing analysis |
| USD 4.9B | 2025 | 2032 (USD 20.7B) | 22.7% | Platform + services, 8 verticals | A competing analysis |
Our judgment: the ~22–23% CAGR cluster is the most defensible near-term anchor. The 29% figure likely reflects a narrower 2026 base and aggressive managed-services attach. The 19% view under-weights greenfield AI workloads. Buyers should plan against a 22.5% central case with a 19–29% sensitivity band.
Segmentation is remarkably consistent across sources: platforms dominate revenue while services grow faster, cloud leads deployment while on-premises persists in regulated verticals, and BFSI anchors demand.
| Parent Segment | Children | Leading Share / Growth |
|---|---|---|
| Component | Platform, Services | Platform ~58–65%; Services fastest CAGR (~30%) |
| Deployment | Cloud, On-Premises, Hybrid | Cloud ~62%; Hybrid fastest-growing |
| Type | Agile Development, DevOps, Lean Manufacturing | Agile leads; DevOps fastest CAGR |
| Enterprise Size | Large Enterprises, SMEs | Large ~60–72%; SMEs fastest CAGR (~32%) |
| Vertical | BFSI, IT & Telecom, Healthcare, Retail, Manufacturing, Government, Transport & Logistics | BFSI ~28%; Healthcare fastest (~35%) |
| Application | Data Integration & ETL, Observability, Governance & Lineage, Orchestration | Integration & ETL largest block |
Implication: the platform/services split matters most for buyers — platform licenses are sticky but services spend is where implementation risk and cost overruns concentrate.
North America leads with 40–46% of global revenue in 2025, anchored by early cloud adoption, mature data-governance regimes and hyperscaler concentration. Asia-Pacific is the fastest-growing region at a 34% CAGR, powered by greenfield cloud deployments and sovereign-data mandates.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.26% |
| Asia-Pacific | 0.22% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | 2025 Revenue Share | Growth Outlook |
|---|---|---|
| North America | ~42% | Mature; steady ~20% CAGR |
| Europe | ~26% | GDPR-driven governance demand |
| Asia-Pacific | ~22% | Fastest at ~34% CAGR |
| Latin America | ~5% | Emerging; SME-led |
| Middle East & Africa | ~5% | Fastest-growing per one source |
Regional tree (parent → children):
The U.S. alone was valued near USD 1.4 billion in 2025; China is projected to grow at 21.4% CAGR to ~USD 3.5 billion by 2032, making it the single largest incremental-revenue opportunity outside North America.
Growth is being pulled by AI/ML productionization and hybrid-cloud sprawl, while being restrained by skills scarcity and compliance cost. Net effect: demand is durable but adoption velocity is uneven across enterprise sizes.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI/ML workload adoption | Driver | High | Production pipelines demand governed, observable data flows |
| Real-time analytics demand | Driver | High | Decision loops compress from days to minutes |
| Cloud-native stack migration | Driver | High | Hyperscaler capex >USD 330B in 2024 |
| Hybrid/multi-cloud complexity | Driver | Medium-High | Centralized orchestration becomes mandatory |
| Data-privacy regulation (GDPR/HIPAA) | Mixed | High | Drives governance spend but raises cost-to-value |
| Skilled DataOps talent shortage | Restraint | High | 30–50% salary premiums; SME adoption lags |
| Legacy ETL switching costs | Restraint | Medium | Technical debt extends migration cycles |
| High implementation/tooling cost | Restraint | Medium | Full transformations exceed USD 1M |
Balance view: drivers are structural and compounding; restraints are cyclical and addressable through managed services and low-code orchestration. That asymmetry supports the higher end of the CAGR band through 2030.
The market is moderately concentrated: the top five players hold ≈52% share, with Microsoft Azure leading at ~14.5% in 2025. Differentiation now hinges on hybrid interoperability and governance depth rather than pipeline features alone.
| Vendor | Positioning | Notable Strength |
|---|---|---|
| Microsoft Azure | Market leader, ~14.5% share | Native integration with Fabric, Purview governance |
| IBM | Enterprise incumbent | Hybrid orchestration + watsonx AI pipelines |
| AWS | Hyperscale challenger | Serverless DataOps, Glue/Lake Formation ecosystem |
| SAP | ERP-adjacent | Embedded DataOps in BTP data fabric |
| Oracle | Database-anchored | Autonomous data warehouse integration |
| Informatica | Pure-play specialist | MDM + lineage depth |
| Databricks | Lakehouse disruptor | Unified analytics + AI on one platform |
| Talend / StreamSets | Pipeline specialists | CI/CD-native data integration |
| Collibra / Atlan | Governance-first | Catalog + lineage adjacent to DataOps |
| DataKitchen / DataOps.live | Niche pure-plays | Agile DataOps orchestration |
Moats: hyperscalers benefit from bundling and data gravity; specialists win on governance depth and multi-cloud neutrality. Our analysis suggests pure-play pipeline vendors face the sharpest consolidation pressure through 2028.
Buyers should weight governance and lineage depth, hybrid interoperability, and total cost predictability above raw pipeline throughput. Implementation scope creep — not license cost — is the dominant budget risk; industry evidence shows cloud invoice overruns of up to 300% in early phases. Switching costs are material: legacy ETL, on-prem warehouses and proprietary middleware create 12–24 month migration tails.
Compliance is now a selection criterion, not an afterthought. GDPR enforcement has reached USD 8.4 billion in cumulative fines, with authorities explicitly targeting data lineage and AI processing — capabilities DataOps platforms must evidence, not just claim. Regulated verticals (BFSI, healthcare, government) should require vendor-demonstrated lineage-to-policy traceability in the RFP.
SME adoption remains structurally constrained: only ~28% of 2025 revenue came from SMEs versus ~72% from large enterprises with specialist teams. Managed services and low-code orchestration are the practical bridge — buyers without deep engineering bench should prioritize these commercial models. Procurement should also validate vendor roadmap alignment with lakehouse standards (Iceberg, Delta) to avoid lock-in.
The balance of evidence favors the 22.5% central CAGR case, with a credible upside scenario toward 29% if AI-driven pipeline demand accelerates faster than enterprise skills can absorb. The strongest counter-argument — that talent scarcity and compliance cost will cap adoption near 19% — is real but self-limiting: managed services and low-code tooling are already converting the talent-constrained segment into addressable demand, a mechanism most bearish models underweight.
Our view is that DataOps is transitioning from a departmental tooling purchase to an enterprise operating-layer decision. That shift explains why the top five vendors now control roughly half the market and why single-function pipeline vendors face margin compression. Buyers who treat DataOps as software procurement will underinvest in governance and pay later in compliance remediation; buyers who treat it as infrastructure will consolidate earlier and capture compounding efficiency.
Actionable strategy:
What would change our conclusion: a sustained deceleration in AI pilot-to-production conversion, or regulatory safe-harbors that reduce lineage obligations, would pull the market toward the 19% floor. Conversely, evidence of SME adoption crossing 35% of revenue would justify the 29% ceiling. Precise sub-segment forecasting across these scenarios — by vertical, deployment mode and region — is where the full report adds execution-grade value beyond this overview.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.5% from 2020-2034 |
| Segmentation |
|
Published 2025 valuations range from USD 4.9 billion to USD 5.97 billion, with a consensus near USD 5.8 billion. The spread reflects differing treatment of managed services and platform-only scopes, so buyers should anchor on a composite rather than any single figure.
Forecasts cluster around a 22.5% CAGR through 2030, with a range of 19.25% to 29.31% depending on base year and scope. Our central case uses 22.5%, reflecting balanced treatment of AI demand and talent constraints.
North America leads with roughly 40–46% of global revenue in 2025, driven by mature cloud adoption and hyperscaler concentration. Asia-Pacific is the fastest-growing region, expanding at approximately 34% CAGR.
Microsoft Azure leads with about 14.5% share, followed by IBM, AWS, SAP and Oracle. Together the top five hold approximately 52% of the market, indicating moderate concentration and accelerating consolidation pressure on niche specialists.
Only about 28% of 2025 revenue came from SMEs, versus 72% from large enterprises. Technical implementation complexity and a shortage of DataOps engineers concentrate adoption among organizations with dedicated engineering teams, though managed services are narrowing the gap.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the DataOps value chain, including cloud infrastructure providers, pure-play DataOps software vendors, systems integrators, managed service providers and enterprise data-platform buyers. Decision-maker designations interviewed included Chief Data Officers, VP-level Data Engineering leads, Heads of Analytics & AI, and Procurement Directors responsible for platform consolidation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Data Officers & Heads of Analytics | 35% |
| VP-Level Data Engineering Leads | 30% |
| Procurement & Vendor Management Directors | 20% |
| Governance & Compliance Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud Infrastructure & Hyperscaler Providers | 35% |
| Pure-Play DataOps Software Vendors | 30% |
| Systems Integrators & Managed Service Providers | 20% |
| Enterprise End-User Buyers | 15% |
We validated findings against official multilateral and regulatory databases, including Eurostat ICT enterprise surveys, U.S. Bureau of Labor Statistics occupational projections, SEC 10-K filings and annual investor presentations from listed data-platform vendors, patent databases tracking pipeline-orchestration and lineage innovations, and recognized standards bodies. All third-party market forecasts were anonymized and cross-referenced for scope alignment.
We applied simultaneous top-down (macroeconomic IT spend allocation and vertical segment share) and bottom-up (vendor revenue, seat pricing, cloud consumption, and end-use deployment modeling) triangulation. Divergent estimates were reconciled by normalizing base years and scope definitions, then weighting toward the most defensible mid-band CAGR.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue & consumption triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & AI demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border cloud spend & regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, platform revenue mapping & commercial filings | High |