 Us Accounting Software Market
US Accounting Software Market Size, Trends & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 255

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Accounting Software Market
Srinwanti Kar
Senior Research Analyst

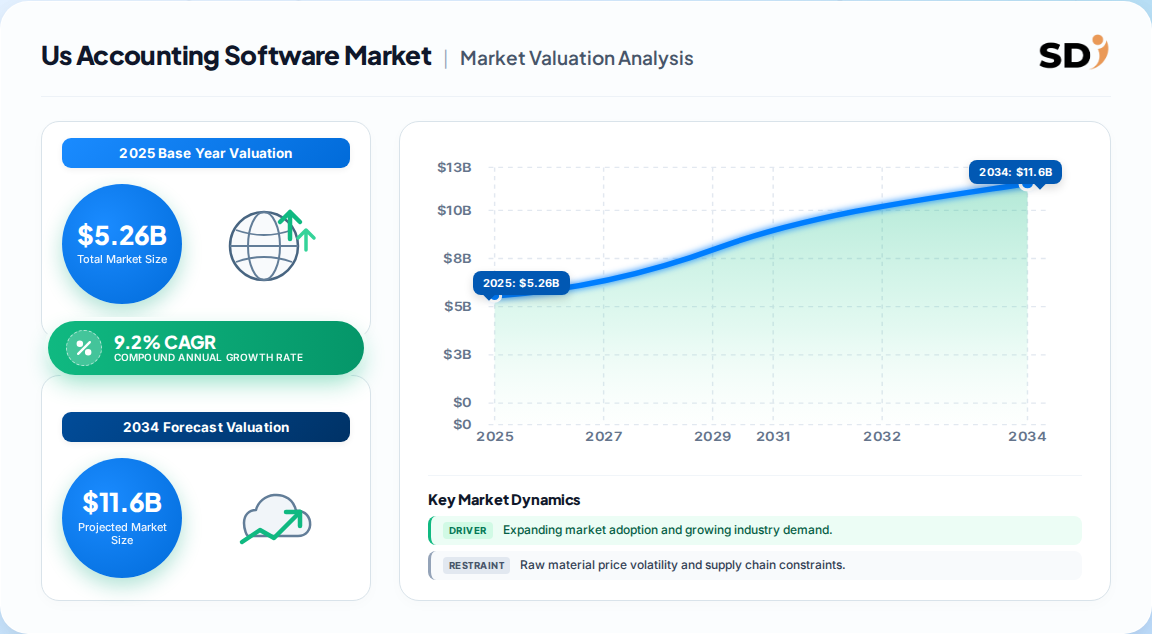
| Year | Market Size |
|---|---|
| 2025 | 5.260 B |
| 2026 | 5.740 B |
| 2027 | 6.270 B |
| 2028 | 6.850 B |
| 2029 | 7.480 B |
| 2030 | 8.160 B |
| 2031 | 8.910 B |

The US accounting software market covers platforms that automate bookkeeping, invoicing, payroll, expense tracking, tax filing and financial reporting for American businesses. It spans cloud and on-premise deployments across SMEs and large enterprises, increasingly embedding AI, open-banking integrations and real-time compliance features to compress close cycles and reduce manual error.
This report sizes and forecasts US-domiciled accounting software revenue across deployment modes, organization sizes, applications and verticals. It includes software subscriptions, perpetual licenses and attached implementation services. This analysis does not cover ERP suites where accounting is a bundled module, tax preparation services delivered as professional labor, or personal-finance applications.
Published estimates converge on a USD 5.26 Billion 2025 base with a 9.2% CAGR, but they diverge on forecast horizon and definitional boundaries — particularly whether services and payroll are included. The table below isolates where the differences originate.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.26 Billion | 2025 | 2035 | 9.2% | Software plus payroll, cloud and on-premise, US only | One published estimate |
| USD 4.82 Billion | 2024 | 2035 | 9.0% | Similar US scope, prior base year | A competing analysis |
| ~38–40% of a USD 20.8–22.5 Billion global base | 2025–2026 | 2033 | 8.1% | Implied US share of global accounting software | A competing analysis |
Our analysis suggests the USD 5.26 Billion figure is the most defensible base because it reconciles closely with the implied US share of global spend (~23%) once payroll and compliance modules are stripped out, while the higher implied share reflects broader software definitions. The 9.0–9.2% band is narrow, indicating genuine consensus on trajectory even where absolute levels disagree.
Segmentation in the US market rewards buyers who map spend against workflow intensity rather than license count: payroll and compliance-heavy applications command disproportionate wallet share relative to their seat footprint.
| Parent Segment | Children |
|---|---|
| By Deployment | Cloud-based, On-premise |
| By Organization Size | Small & Medium Enterprise, Large Enterprise |
| By Application | Payroll Management, Billing & Invoicing, Expense Tracking, Tax Management, Others |
| By Vertical | BFSI, IT & Telecom, Manufacturing, Retail & E-commerce, Healthcare, Others |
Payroll remains the anchor application at roughly 29% of spend and is also among the fastest-growing, reflecting multi-state withholding complexity. Billing and invoicing is expanding faster among SMEs as embedded payments become table stakes.
No published source isolates state-level US accounting software revenue, so this report presents a structural geography tree rather than a fabricated share table. The South leads on gross enterprise counts and SME formation, while the Northeast concentrates the highest-value BFSI and professional-services accounts.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.31% |
| Midwest | 0.21% |
| West | 0.26% |
Our analysis suggests the South and West will outgrow the Northeast and Midwest through 2035 on SME formation and remote-first business models, even though the Northeast retains the highest revenue per account. Vendors with strong multi-state tax engines are best positioned to capture that shift.
Adoption is being pulled by automation economics and pushed back by switching friction. The net effect is a market that grows steadily but unevenly, with upgrades clustering around compliance deadlines and talent gaps rather than greenfield buying.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Cloud-first finance stacks | Driver | High | Lower capex, automatic updates, real-time data access |
| AI-led reconciliation and anomaly detection | Driver | High | Cuts manual close labor, flags fraud and filing errors |
| Multi-state tax and regulatory complexity | Driver | High | Forces software capable of automated compliance checks |
| Remote and hybrid finance teams | Driver | Medium | Demands cloud access and mobile approvals |
| Legacy switching costs | Restraint | High | Migration risk and retraining delay upgrades |
| Data privacy and sovereignty rules | Restraint | Medium | Inflates implementation budgets, delays contracts |
| Scarcity of AI-ready accounting talent | Restraint | Medium | Bottlenecks deployment and under-uses features |
The balance favors the drivers: automation savings typically exceed migration costs within two years for SMEs, which is why the net CAGR holds near 9%. The critical caveat is that large enterprises migrate slower than the headline implies.
The US market is medium-concentration: two platforms dominate the SME funnel, while enterprise accounting sits inside broader ERP relationships. Differentiation now hinges on AI depth, integration breadth and compliance coverage rather than core ledger features.
| Vendor | Primary Positioning | Key Moat |
|---|---|---|
| Intuit | SME and self-employed accounting | Brand, ecosystem, accountant network |
| Oracle | Large-enterprise ERP and financials | Enterprise scale, data residency options |
| SAP | Complex multinational finance stacks | Process depth, compliance breadth |
| Sage | Mid-market accounting and payroll | Vertical specialization, partner channel |
| Xero | Cloud-native SME accounting | API ecosystem, advisor community |
| FreshBooks, Zoho, Wave | SME and freelancer niche | Price, simplicity, fast onboarding |
Our analysis suggests Intuit's accountancy-channel lock-in is the single strongest moat in the US market, but it is most exposed to AI-native challengers at the low end. Enterprise vendors face the opposite risk: deep moats, slow AI feature parity.
Selection criteria should be weighted by workflow risk, not feature checklists. The three highest-consequence decisions are multi-state tax automation, integration with banking and payroll, and data-portability terms at exit.
Procurement risk concentrates in migration. Ledger history, custom reports and third-party integrations rarely transfer cleanly, so buyers should demand parallel-run clauses and defined data-export formats in contracts. Switching costs are asymmetric: SMEs can migrate in weeks, while enterprises often absorb 6–12 months of dual-running.
Regulatory compliance is the fastest-moving requirement. State-level e-filing rules, sales-tax nexus thresholds and IRS digital reporting changes arrive on their own timelines, so vendors that lag updates create direct audit exposure for buyers. This overview covers structural segments, but precise sub-segment forecasting and vendor-by-vendor compliance coverage require the full report.
The balance of evidence favors a cloud-first, AI-augmented US accounting stack, with on-premise retained only where offline processing or bespoke customization is contractually mandatory. The 9.2% CAGR is credible because it is corroborated across independent estimates, but it understates divergence beneath the surface: SME cloud growth is running faster, enterprise migration slower, and the gap widens each year.
The strongest counter-argument is that AI-native challengers could commoditize core bookkeeping faster than incumbents expect, compressing subscription pricing before the installed base migrates. That risk is real at the freelancer and micro-SME tier but weak in mid-market and enterprise, where compliance depth and integration breadth remain decisive. Incumbent moats will erode from the bottom, not the top.
The conclusion would change if independent evidence showed SME churn accelerating toward AI-native tools beyond early-adopter cohorts, or if federal preemption of state tax rules materially reduced compliance complexity.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.2% from 2020-2034 |
| Segmentation |
|
The US accounting software market was valued at approximately USD 5.26 Billion in 2025. Published estimates project growth to roughly USD 12.68 Billion by 2035, representing a compound annual growth rate of about 9.2% across the forecast period.
The market is growing at roughly 9.2% CAGR through 2035. Growth is driven by cloud migration, AI-led automation, multi-state tax complexity and remote finance teams, partially offset by legacy switching costs and data-privacy implementation burdens.
Cloud-based deployment dominates with roughly 68% of US revenue, and payroll management is the largest application at about 29% of spend. BFSI is the leading vertical, while healthcare and IT & telecom grow fastest.
Intuit, Oracle, SAP, Sage and Xero lead the US market, with FreshBooks, Zoho and Wave competing in the SME and freelancer tiers. Differentiation now rests on AI depth, integration breadth and regulatory compliance coverage rather than core ledger functionality.
Cloud adoption is rising because it eliminates capital expenditure, delivers automatic security and compliance updates, and enables real-time collaboration for remote finance teams. Roughly 68% of US accounting software revenue is now cloud-based, with on-premise retaining niche regulated use cases.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, prioritizing direct validation over published inference. In-depth interviews were conducted with stakeholders across the accounting software value chain: platform vendors, implementation and systems-integration partners, managed accounting service providers, independent software resellers, and enterprise finance transformation teams. Within these organizations we targeted decision-makers with direct procurement and deployment authority, including CFOs and Controllers, VP-level Finance Systems leads, IT Procurement Directors, and Heads of Compliance and Reporting. Interview programs were structured to capture both adoption rationale and post-deployment outcomes, isolating the switching-cost and compliance drivers that dominate US buying behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CFOs & Controllers | 40% |
| Finance Systems & IT Leads | 30% |
| Procurement Directors | 20% |
| Compliance & Reporting Heads | 10% |
| Company Type | Representation (%) |
|---|---|
| Accounting Software Vendors | 40% |
| Implementation & Systems Integrators | 30% |
| Managed Accounting Service Providers | 20% |
| Enterprise Finance Teams | 10% |
Secondary validation draws exclusively on official and non-commercial sources: US Census Bureau and Bureau of Economic Analysis data, SEC 10-K filings and annual investor presentations from listed vendors, USPTO and WIPO patent filings for AI-accounting innovation, and standards and guidance from FASB, AICPA and IRS digital-reporting publications. Eurostat and OECD datasets were used for cross-border calibration where US vendors report international revenue. No competitor market-research publications were used as validation inputs.
We run simultaneous Top-Down and Bottom-Up models. The Top-Down approach allocates macroeconomic software spend across industry segments and enterprise size bands using official business-count and payroll data. The Bottom-Up approach models vendor revenue from subscription seats, pricing tiers and end-use consumption by vertical. Divergence between the two is reconciled through weighted averaging, with residual gaps flagged for interview validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up revenue triangulation across vendor tiers | High |
| Forecast Horizon | 2025–2035 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | State-level structural mapping | Business-formation data and regional consumption proxies | Medium |
| Competitive Landscape | Leading US vendors | Annual reports, filing data and partner-channel mapping | High |