 5g Security Market
5G Security Market Size, Growth & Forecast 2025-2035
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 263

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 5g Security Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 2.850 B |
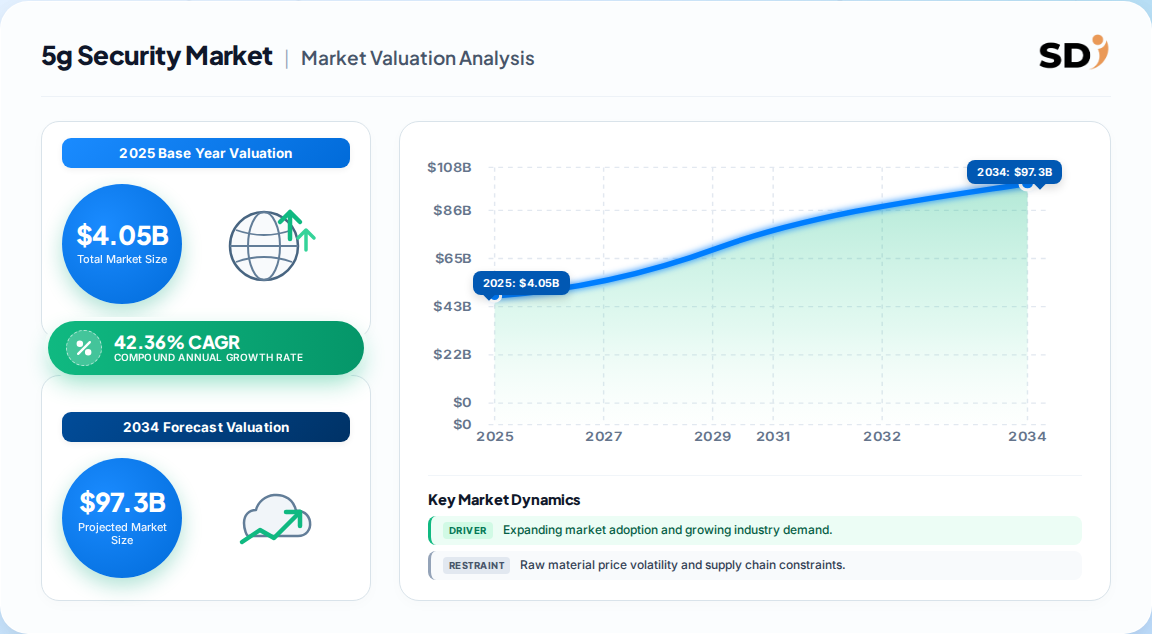
| 2025 | 4.050 B |
| 2026 | 5.770 B |
| 2027 | 8.210 B |
| 2028 | 11.69 B |
| 2029 | 16.64 B |
| 2030 | 23.69 B |

5G security refers to the comprehensive set of solutions, services, and protocols designed to protect fifth-generation mobile networks—including the core, RAN, transport, and edge layers—from cyber threats. It encompasses encryption, identity management, threat detection, and policy enforcement to ensure data integrity, privacy, and availability across ultra-low-latency, high-density, and network-sliced environments.
This analysis covers the global 5G security market across offering (solutions and services), network security architecture (RAN, core, transport, application, and edge security), deployment mode (on-premises and cloud), end-user verticals (telecom operators, manufacturing, healthcare, automotive, retail, BFSI, public safety, and others), and organization size (large enterprises and SMEs). It addresses market sizing, segmentation, regional dynamics, competitive landscape, and strategic outlook for the forecast period 2025–2035. This analysis does not cover adjacent markets such as traditional 4G security, general cybersecurity spending unrelated to 5G networks, or consumer mobile device security software.
Estimates for the global 5G security market vary due to differing scope definitions and base years, but all point to exceptional growth. The table below compares key published benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 4.05 billion | 2025 | 2035 | 42.36% | Global 5G security solutions and services, all verticals | Aggregated industry analysis |
| USD 3.92 billion | 2025 | 2030 | 43.2% (to 2026), 42.4% (to 2030) | Global 5G security, component and deployment segmentation | One published estimate |
| USD 3.37 billion | 2025 | 2034 | 41.8% | Global 5G security, offering and architecture | Competing analysis |
| USD 11.37 billion | 2026 | 2031 | 30.15% | 5G network security, including transport and edge layers | Alternative benchmark |
| USD 1.10 billion | 2021 | 2030 | 41.4% | 5G security solutions and services, early base year | Historical baseline |
Our analysis suggests the 2025 valuation of USD 3.37–4.05 billion is most defensible, as it aligns with the rapid commercial rollout of 5G standalone cores and the corresponding surge in security spending. The 2026 figure of USD 11.37 billion from one source appears to use a broader definition that includes managed security services and adjacent network infrastructure security, which inflates the base. The 42.36% CAGR from the aggregated analysis is consistent with the 41.3–43.2% range reported across sources, reinforcing confidence in a ~41–42% growth trajectory through the early 2030s.
The 5G security market is segmented by offering, network security architecture, deployment mode, end-user vertical, and organization size, with each dimension revealing distinct growth dynamics.
| Parent Segment | Children |
|---|---|
| By Offering | Solutions (Next-Gen Firewall, Antivirus/Antimalware, Security Gateway, DDoS Protection, Sandboxing, Others), Services (Consulting, Implementation, Support & Maintenance, Managed Security) |
| By Network Security Architecture | RAN Security, Core Security, Transport Security, Edge Security, Application Security |
| By Deployment Mode | On-Premises, Cloud-Based |
| By End-User Vertical | Telecom Operators, Manufacturing, Healthcare, Automotive & Transportation, Retail, BFSI, Public Safety, Defense, Energy & Utilities, Others |
| By Organization Size | Large Enterprises, SMEs |
Solutions account for the majority of revenue (~60–67%), driven by demand for next-gen firewalls and DDoS protection. However, services are growing faster as operators seek managed security and consulting expertise to navigate multi-vendor complexity. Cloud deployment is outpacing on-premises as telcos virtualize security functions. Core security remains the largest architecture segment, while edge security is the fastest-growing due to MEC rollouts. Manufacturing leads vertical adoption, but healthcare and automotive are accelerating.
North America leads the global 5G security market with approximately 37% revenue share in 2025, driven by early 5G standalone deployments, stringent regulatory mandates, and high cybersecurity spending. Asia-Pacific is the fastest-growing region, forecast to expand at a ~36% CAGR through 2035, fueled by rapid 5G infrastructure buildouts in China, Japan, and South Korea.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.29% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) |
|---|---|
| North America | 37% |
| Asia-Pacific | 29% |
| Europe | 24% |
| Latin America | 5% |
| Middle East & Africa | 5% |
Regional Deep Dive:
The 5G security market is propelled by escalating cyber threats, regulatory mandates, and the proliferation of IoT and edge computing, while fragmentation and cost complexity temper adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising cyber threats and attack surface expansion | Growth | High | 30 billion connected devices by 2025; ransomware targeting IoT |
| Regulatory compliance (NIS2, NIST, ETSI, 3GPP) | Growth | High | Mandates 9% of IT budgets for cybersecurity; 24-hour incident reporting |
| Adoption of IoT devices | Growth | High | 75 billion IoT devices projected by 2025; secure authentication demand |
| Proliferation of 5G standalone cores and network slicing | Growth | Medium-High | 127 discrete security requirements for SA vs. NSA; slice isolation complexity |
| Edge computing and MEC infrastructure | Growth | Medium | 73% more controls required at edge vs. centralized |
| Fragmented security standards across vendors | Restraint | Medium | 78% of rollouts are multi-vendor; 23 custom tie-ins per integration |
| High implementation and management costs | Restraint | Medium | Upfront platform, hardware, and integration costs deter SMEs |
| Shortage of 5G-skilled cybersecurity workforce | Restraint | Medium | Acute talent gap in North America and Europe |
| Energy consumption of security functions | Restraint | Low-Medium | Inline encryption and AI inference raise power draw |
The balance of evidence favors robust growth, as regulatory mandates and threat escalation are non-discretionary drivers. However, vendors must address cost and complexity concerns through managed services and interoperable platforms to penetrate the SME segment. The fragmentation restraint is particularly acute in multi-vendor environments, where integration costs can erode ROI and delay deployment.
The 5G security market is moderately concentrated, with telecom equipment giants and cybersecurity specialists competing on integrated, AI-driven platforms.
| Company | Headquarters | Key 5G Security Offerings | Differentiation |
|---|---|---|---|
| Ericsson | Sweden | Network security, RAN security, managed services | Deep telco integration; 55% of 2024 contracts SA-only |
| Nokia | Finland | Security gateway, DDoS, cloud-native security | End-to-end portfolio; strong in Europe |
| Cisco Systems | USA | Next-gen firewall, cloud security, zero-trust | Broad enterprise reach; cloud security leadership |
| Huawei | China | 5G core security, RAN security | Cost-effective; dominant in Asia-Pacific |
| Palo Alto Networks | USA | Threat detection, slice-aware security | AI/ML leadership; embedded in T-Mobile slice |
| Fortinet | USA | Security fabric, DDoS, firewall | Integrated platform; strong SME focus |
| Juniper Networks | USA | Secure router, cloud-native security | Service provider focus; automation |
| ZTE Corporation | China | 5G security solutions | Competitive pricing; China market strength |
| Check Point Software | Israel | Threat prevention, cloud security | Strong threat intelligence |
Our analysis suggests vendors with end-to-end, cloud-native portfolios and proven integration with major telco orchestration platforms will capture disproportionate share. Differentiation is shifting from hardware-based security to software-defined, AI-augmented platforms that can secure slices and edge workloads in real time. Partnerships with hyperscalers and managed security providers are becoming critical to address the skills gap.
Buyers and operators must prioritize interoperability, regulatory compliance, and lifecycle management when selecting 5G security solutions. Multi-vendor environments are the norm (78% of rollouts), so vendors that offer open APIs and vendor-neutral orchestration reduce integration costs and future-proof investments. Compliance with 3GPP, NIST, and ETSI standards is non-negotiable, but buyers should also demand continuous monitoring and automated policy enforcement to keep pace with evolving threats.
Procurement risks include vendor lock-in, hidden integration costs, and skills shortages. Operators should evaluate managed security services to bridge talent gaps, especially for 24/7 threat detection. Switching costs are high once a security platform is embedded in the core, so pilot deployments and proof-of-concept trials are essential. Regulatory mandates, such as the EU's NIS2 Directive, require 24-hour incident reporting and 9% of IT budgets allocated to cybersecurity—buyers should verify vendor compliance and audit capabilities upfront. Finally, energy consumption and latency budgets must be assessed, particularly for edge deployments where power and space are constrained.
The balance of evidence strongly favors accelerated investment in 5G security, with the market on track to exceed USD 138 billion by 2035. The convergence of regulatory mandates, threat escalation, and architectural complexity creates a durable demand environment. However, the strongest counter-argument is that high implementation costs and fragmented standards could slow adoption among SMEs and price-sensitive operators, particularly in developing markets. We view this as a timing risk rather than a structural threat, as managed services and cloud-based delivery models are already lowering barriers.
Actionable Strategy:
What would change our conclusion: A significant delay in global 5G SA rollouts, a breakthrough in low-cost open-source security frameworks that commoditizes solutions, or a prolonged economic downturn that depresses telecom capex would temper growth. We would also revise our outlook if standards fragmentation persists and raises integration costs beyond 30% of total deployment budgets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 42.36% from 2020-2034 |
| Segmentation |
|
The global 5G security market was valued at approximately USD 4.05 billion in 2025 and is projected to reach USD 138.58 billion by 2035, growing at a 42.36% CAGR.
North America leads with about 37% revenue share in 2025, followed by Asia-Pacific (29%) and Europe (24%). Asia-Pacific is the fastest-growing region.
Rising cyber threats, regulatory compliance mandates (NIS2, NIST, ETSI), IoT adoption, and the proliferation of 5G standalone cores and network slicing are the primary growth drivers.
Key players include Ericsson, Nokia, Cisco Systems, Huawei, Palo Alto Networks, Fortinet, Juniper Networks, ZTE, and Check Point Software Technologies.
Services are the fastest-growing offering segment, while edge security is the fastest-growing architecture layer and healthcare is among the fastest-growing verticals.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with 45+ stakeholders across the 5G security value chain, including telecom equipment vendors, pure-play cybersecurity firms, managed security service providers (MSSPs), systems integrators, and enterprise end-users. Decision-maker designations interviewed include Chief Information Security Officers (CISOs), VP of Network Security, Heads of 5G Product Management, and Procurement Directors. These interviews provided granular insights into adoption timelines, budget allocation, vendor selection criteria, and deployment challenges.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CISOs & Security Leaders | 35% |
| Network & Infrastructure VPs | 30% |
| Procurement & Sourcing Directors | 20% |
| Product Management Heads | 15% |
| Company Type | Representation (%) |
|---|---|
| Telecom Equipment Vendors | 40% |
| Cybersecurity Pure-Plays | 30% |
| Managed Security Service Providers | 20% |
| Systems Integrators | 10% |
We triangulated primary data with official multilateral trade databases (UN Comtrade, WTO), regulatory filings (SEC 10-K, annual reports), patent databases (USPTO, EPO), and standards bodies (3GPP, ETSI, NIST, GSMA). Corporate investor presentations and technical white papers were also analyzed to validate vendor claims and market positioning. All secondary sources are publicly available and were cross-referenced for consistency.
We employed simultaneous top-down and bottom-up modeling. The top-down approach allocated global telecom capex and cybersecurity spending to 5G-specific security functions based on industry benchmarks. The bottom-up approach modeled vendor revenues by segment, deployment mode, and region, cross-validated with capacity and pricing data. Divergences were resolved through expert interviews and historical growth pattern analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up vendor revenue triangulation | High |
| Forecast Horizon | 2025–2035 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis, regional capex allocation | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |