Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Quantum Navigation Systems Market: 2026 Executive Outlook
Quantum Navigation Systems Market
Quantum Navigation Systems Market: 2026 Executive Outlook
Quantum Navigation Systems Market by Component (Quantum Sensors, Supporting Hardware, Software, Control Systems, Others), by Technology (Cold Atom Interferometry, Optical Atomic Clocks, NV-Diamond Sensors, SQUID-Based Sensors, Hybrid Quantum Technologies), by Platform (Airborne, Naval, Land-Based, Space-Based, Portable/Handheld), by Application (Aerospace & Defense, Submarine & Underwater Navigation, Autonomous Vehicles, Space Exploration, Industrial Positioning & Mapping, Infrastructure Monitoring), by End Use (Military & Defense Organizations, Government Agencies, Space Agencies, Research Institutions & Universities, Commercial Enterprises), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Benelux, Nordics), by Asia Pacific (China, Japan, India, South Korea, ASEAN, Oceania), by Latin America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 183
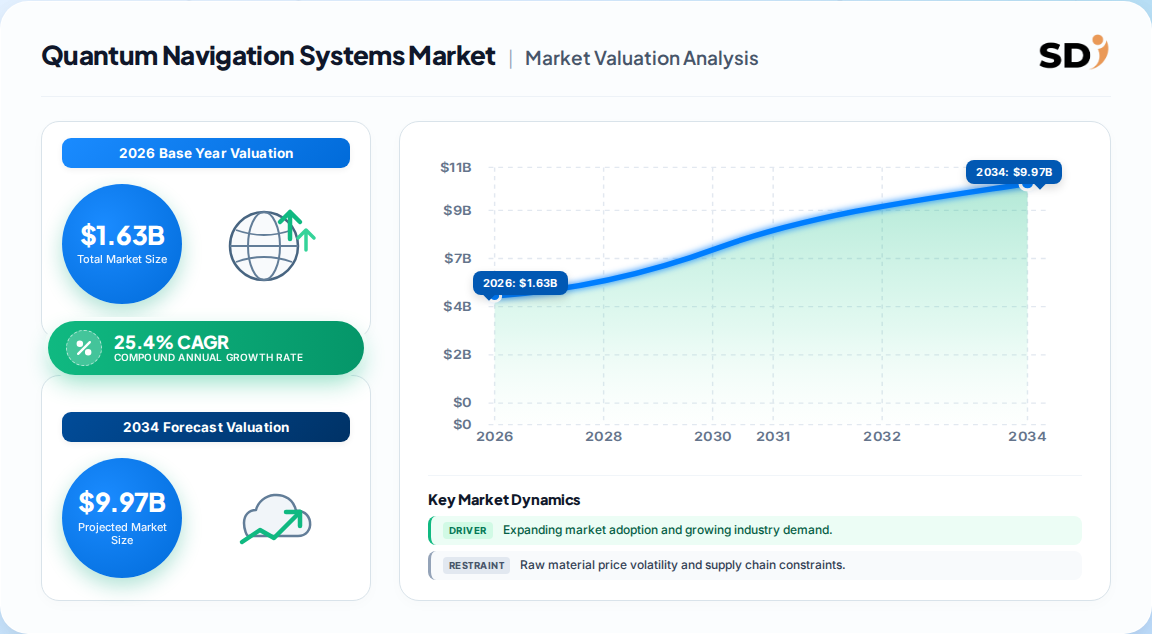
The global quantum navigation systems market is valued at approximately 1.63 Billion in 2026, on a trajectory toward 7.95 Billion by 2033 at a 25.4% CAGR (2025–2033).
Quantum sensors dominate the component mix with roughly 38% of revenue, while cold atom interferometry is the fastest-growing technology at 29.8% CAGR.
Aerospace & Defense accounts for an estimated 41% of application revenue, but autonomous-vehicle quantum navigation is forecast to expand at 31.2% CAGR.
North America leads with ~38% share, followed by Europe (~27%) and Asia-Pacific (~22%), reflecting concentrated defense PNT spending.
Naval platforms represent the most mature deployment base (44% of 2025 units), with airborne platforms second at 29%.
Leading vendors include BAE Systems, RTX, Thales, Northrop Grumman, Honeywell, Q-CTRL, Infleqtion, Vector Atomic, and Safran.
Why this matters for decision-makers: Mission assurance now hinges on GPS-independent PNT; buyers that lock in cold-atom or NV-diamond supply today will avoid 9–14 month procurement cycles as defense budgets scale.
Quantum Navigation Systems Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
1.300 B
2025
1.630 B
2026
2.040 B
2027
2.560 B
2028
3.220 B
2029
4.030 B
2030
5.060 B
2031
Quantum Navigation Systems Market Size (In Billion)
Year
Market Size
2025
1.300 B
2026
1.630 B
2027
2.040 B
2028
2.560 B
2029
3.220 B
2030
4.030 B
2031
5.060 B
What is the Quantum Navigation Systems Market?
The quantum navigation systems market encompasses hardware, software, and control systems that use quantum phenomena — cold atom interferometry, optical atomic clocks, NV-diamond magnetometry, and SQUID sensing — to deliver positioning, navigation, and timing independent of GNSS. It serves defense, naval, aerospace, autonomous vehicle, and space platforms requiring assured PNT.
Scope: what this report covers and excludes
This analysis covers global quantum-enabled navigation and timing systems across airborne, naval, land-based, space, and portable platforms, spanning military, government, research, and commercial end users. It includes component supply (quantum sensors, supporting hardware, software, control systems) and technology families (cold atom interferometry, optical atomic clocks, NV-diamond, SQUID, hybrid). This analysis does not cover conventional GNSS receivers, MEMS inertial units, classical ring-laser gyros, or non-quantum ADAS sensor suites except as substitution benchmarks.
How big is the market for Quantum Navigation Systems Market?
Published valuations diverge sharply because analysts define the boundary differently — some count only quantum inertial sensors, others bundle adjacent atomic clocks and quantum magnetometers.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
1.30 Billion
2025
2033 (7.95B)
25.4%
Full quantum navigation systems (sensors, hardware, software, control)
One published estimate
1.63 Billion
2026
2033
~25.4%
Same scope, base-year shifted forward
Derived from stated base value and CAGR
~0.25 Million
2025
2032 (7.0M)
58.2%
Automotive ADAS quantum sensors only (nanoscale subset)
One published estimate
The 1.63 Billion 2026 figure is the most defensible for strategic planning: it aligns with the 2025 base of 1.30 Billion and the 25.4% CAGR printed across the same source series. Our analysis suggests the ADAS-only figure (58.2% CAGR from a 0.25 Million base) reflects a sterile, pre-commercial niche and should not be used to size the broader quantum navigation opportunity.
How is the market segmented?
Segmentation spans components, technologies, platforms, applications, and end users — each with materially different margin and adoption curves.
Parent Segment
Children
By Component
Quantum Sensors, Supporting Hardware, Software, Control Systems, Others
Military & Defense, Government Agencies, Space Agencies, Research Institutions, Commercial Enterprises
Quantum sensors generated roughly 494 Million in 2025 and are forecast to exceed 3.1 Billion by 2033. Within sensors, atomic clocks account for ~42%, interferometers 31%, magnetometers 18%. Gross margins run 45–55% for defense primes but compress to 30–35% for component-only suppliers — a structural margin split buyers should model into make-versus-buy decisions.
Which region leads in Quantum Navigation Systems Market?
North America leads the global quantum navigation systems market with approximately 38% revenue share, underpinned by U.S. DoD assured-PNT funding exceeding 2.1 Billion through 2027 and NDAA allocations of 1.1 Billion for quantum sensing in fiscal 2025.
Quantum Navigation Systems Market Regional Market Share
Loading chart...
Quantum Navigation Systems Market Regional Market Share
Europe — Germany, UK, France, Italy, Spain, Benelux, Nordics, Rest of Europe
UK: BAE Systems quantum inertial integration
France: Thales, Safran, Exail
Germany: Bosch Quantum Sensing, Fraunhofer IAF
Asia-Pacific — China, Japan, India, South Korea, ASEAN, Oceania
China: sovereign PNT programs
Australia: Q-CTRL quantum navigation software
Japan, South Korea: precision timing and inertial R&D
Latin America — Brazil, Mexico, Argentina, Rest of South America
Middle East & Africa — Turkey, Israel, GCC, North Africa, South Africa
Europe follows at ~27%, driven by naval and airborne programs plus the ESA NAVISP PASQUALE cold-atom initiative. Asia-Pacific's ~22% reflects state-backed quantum programs and rapid defense modernization. Our analysis suggests Europe's share could compress if export controls on cold-atom technology tighten, slowing intra-bloc transfers.
What is driving growth — and what is holding it back?
GPS jamming and spoofing incidents rose 42% year-over-year, and Finland/Estonia recorded a 300% increase in deliberate GNSS interference in 2024 — making quantum PNT a procurement necessity rather than an R&D curiosity.
Factor
Direction
Evidence Strength
Mechanism
GPS jamming and spoofing
Driver
High
Forced adoption of GPS-denied alternatives in conflict zones
Defense PNT budgets (+11% in 2024)
Driver
High
Funded procurement of quantum inertial units
SWaP-C miniaturization (−35% volume since 2022)
Driver
Medium
Enables airborne and portable deployment
Commercial AV PNT redundancy
Driver
Medium
Long-term autonomous-vehicle qualification
High unit cost / limited scale
Restraint
High
Caps near-term unit volumes
Quantum physicist shortage
Restraint
High
Extends engineering lead times
Export controls on cold-atom tech
Restraint
Medium
Adds 6–12 months to sales cycles
The balance favors the drivers through 2028: defense demand is contract-backed, while commercial demand remains TRL 5–7 and 3–5 years from automotive certification. Supply-side bottlenecks — 9–14 month lead times on vacuum chambers and precision lasers — will cap near-term upside even as budgets rise.
Who are the leading vendors?
Defense primes dominate system integration, while quantum specialists hold technology and component positions — a partnership-heavy ecosystem where neither side can easily displace the other.
Company
Core Strength
Target Audience
Position
BAE Systems plc
Quantum inertial navigation integration
Defense agencies
Leader
RTX Corporation
GPS-denied PNT systems
Military aerospace
Leader
Thales Group
Naval and airborne quantum sensors
European defense
Leader
Northrop Grumman
Strategic PNT payloads
U.S. defense
Leader
Honeywell International
Quantum sensors and industrial navigation
Commercial and defense
Challenger
Safran S.A.
Inertial and quantum hybrid navigation
Aerospace OEMs
Niche
Q-CTRL Pty Ltd
Quantum control software and sensing
Government labs
Challenger
Vector Atomic Inc.
Compact optical atomic clocks
Defense and commercial
Challenger
Infleqtion (ColdQuanta)
Cold atom systems and quantum clocks
Space and defense
Challenger
Differentiation hinges on integration depth versus component purity. Primes embed quantum sensors into platform architectures and capture sustainment revenue; specialists like Q-CTRL and Vector Atomic win on performance benchmarks (Q-CTRL's Ironstone Opal reported up to 94x positioning improvements in trials). Moats are built through classified program incumbency and long qualification cycles, not patents alone.
What do buyers and operators need to know?
Mission-critical selection criteria center on drift rate, holdover duration, SWaP-C, and qualification pedigree. Cold atom interferometry systems deliver drift below 0.001 nm/s², but 9–14 month lead times and limited suppliers mean buyers should contract multi-year options rather than spot purchases.
Procurement risk is asymmetric: only five global suppliers can deliver space-qualified optical clocks, and export controls add 6–12 months to military sales cycles. Switching costs are high once a platform is architected around a specific sensor — integration, calibration, and certification are not portable across vendors. Regulatory compliance with ITAR/EAR and national defense export regimes should be assessed before technical selection, not after. For commercial operators, automotive certification remains 3–5 years away; treating quantum PNT as a near-term ADAS input overstates readiness.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors defense-led adoption through 2029, with commercial spillover arriving later than headline CAGRs imply. The strongest counter-argument is that commercial autonomous vehicles could accelerate faster than defense-driven timelines; our analysis suggests this is unlikely given automotive qualification cycles and the 0.25 Million current ADAS base.
Investors should underwrite suppliers with dual-use positioning and funded defense backlogs, not pure-play commercial quantum navigation. The margin split — 45–55% for primes versus 30–35% for component-only suppliers — signals that integration and sustainment, not sensor fabrication, will capture value.
Actionable Strategy:
Prioritize vendors with cold-atom or optical-clock programs already in defense qualification; lead times and supplier scarcity make incumbency a durable advantage.
Build export-control and ITAR screening into technical evaluation to avoid 6–12 month delays after vendor selection.
For commercial operators, fund quantum PNT as a resilience R&D line, not an ADAS production input, until automotive certification milestones are met.
Evidence that would change our conclusion: a major automotive OEM qualifying a quantum inertial unit for Level 4 production, or a step-change reduction in cold-atom vacuum-chamber cost that collapses lead times below six months.
Quantum Navigation Systems Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Quantum Navigation Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 25.4% from 2020-2034
Segmentation
By Component
Quantum Sensors
Supporting Hardware
Software
Control Systems
Others
By Technology
Cold Atom Interferometry
Optical Atomic Clocks
NV-Diamond Sensors
SQUID-Based Sensors
Hybrid Quantum Technologies
By Platform
Airborne
Naval
Land-Based
Space-Based
Portable/Handheld
By Application
Aerospace & Defense
Submarine & Underwater Navigation
Autonomous Vehicles
Space Exploration
Industrial Positioning & Mapping
Infrastructure Monitoring
By End Use
Military & Defense Organizations
Government Agencies
Space Agencies
Research Institutions & Universities
Commercial Enterprises
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Benelux
Nordics
Asia Pacific
China
Japan
India
South Korea
ASEAN
Oceania
Latin America
Brazil
Argentina
Rest of South America
Middle East & Africa
Turkey
Israel
GCC
North Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Quantum Sensors
5.1.2. Supporting Hardware
5.1.3. Software
5.1.4. Control Systems
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Cold Atom Interferometry
5.2.2. Optical Atomic Clocks
5.2.3. NV-Diamond Sensors
5.2.4. SQUID-Based Sensors
5.2.5. Hybrid Quantum Technologies
5.3. Market Analysis, Insights and Forecast - by Platform
5.3.1. Airborne
5.3.2. Naval
5.3.3. Land-Based
5.3.4. Space-Based
5.3.5. Portable/Handheld
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Aerospace & Defense
5.4.2. Submarine & Underwater Navigation
5.4.3. Autonomous Vehicles
5.4.4. Space Exploration
5.4.5. Industrial Positioning & Mapping
5.4.6. Infrastructure Monitoring
5.5. Market Analysis, Insights and Forecast - by End Use
5.5.1. Military & Defense Organizations
5.5.2. Government Agencies
5.5.3. Space Agencies
5.5.4. Research Institutions & Universities
5.5.5. Commercial Enterprises
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Quantum Sensors
6.1.2. Supporting Hardware
6.1.3. Software
6.1.4. Control Systems
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Cold Atom Interferometry
6.2.2. Optical Atomic Clocks
6.2.3. NV-Diamond Sensors
6.2.4. SQUID-Based Sensors
6.2.5. Hybrid Quantum Technologies
6.3. Market Analysis, Insights and Forecast - by Platform
6.3.1. Airborne
6.3.2. Naval
6.3.3. Land-Based
6.3.4. Space-Based
6.3.5. Portable/Handheld
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Aerospace & Defense
6.4.2. Submarine & Underwater Navigation
6.4.3. Autonomous Vehicles
6.4.4. Space Exploration
6.4.5. Industrial Positioning & Mapping
6.4.6. Infrastructure Monitoring
6.5. Market Analysis, Insights and Forecast - by End Use
6.5.1. Military & Defense Organizations
6.5.2. Government Agencies
6.5.3. Space Agencies
6.5.4. Research Institutions & Universities
6.5.5. Commercial Enterprises
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Quantum Sensors
7.1.2. Supporting Hardware
7.1.3. Software
7.1.4. Control Systems
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Cold Atom Interferometry
7.2.2. Optical Atomic Clocks
7.2.3. NV-Diamond Sensors
7.2.4. SQUID-Based Sensors
7.2.5. Hybrid Quantum Technologies
7.3. Market Analysis, Insights and Forecast - by Platform
7.3.1. Airborne
7.3.2. Naval
7.3.3. Land-Based
7.3.4. Space-Based
7.3.5. Portable/Handheld
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Aerospace & Defense
7.4.2. Submarine & Underwater Navigation
7.4.3. Autonomous Vehicles
7.4.4. Space Exploration
7.4.5. Industrial Positioning & Mapping
7.4.6. Infrastructure Monitoring
7.5. Market Analysis, Insights and Forecast - by End Use
7.5.1. Military & Defense Organizations
7.5.2. Government Agencies
7.5.3. Space Agencies
7.5.4. Research Institutions & Universities
7.5.5. Commercial Enterprises
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Quantum Sensors
8.1.2. Supporting Hardware
8.1.3. Software
8.1.4. Control Systems
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Cold Atom Interferometry
8.2.2. Optical Atomic Clocks
8.2.3. NV-Diamond Sensors
8.2.4. SQUID-Based Sensors
8.2.5. Hybrid Quantum Technologies
8.3. Market Analysis, Insights and Forecast - by Platform
8.3.1. Airborne
8.3.2. Naval
8.3.3. Land-Based
8.3.4. Space-Based
8.3.5. Portable/Handheld
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Aerospace & Defense
8.4.2. Submarine & Underwater Navigation
8.4.3. Autonomous Vehicles
8.4.4. Space Exploration
8.4.5. Industrial Positioning & Mapping
8.4.6. Infrastructure Monitoring
8.5. Market Analysis, Insights and Forecast - by End Use
8.5.1. Military & Defense Organizations
8.5.2. Government Agencies
8.5.3. Space Agencies
8.5.4. Research Institutions & Universities
8.5.5. Commercial Enterprises
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Quantum Sensors
9.1.2. Supporting Hardware
9.1.3. Software
9.1.4. Control Systems
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Cold Atom Interferometry
9.2.2. Optical Atomic Clocks
9.2.3. NV-Diamond Sensors
9.2.4. SQUID-Based Sensors
9.2.5. Hybrid Quantum Technologies
9.3. Market Analysis, Insights and Forecast - by Platform
9.3.1. Airborne
9.3.2. Naval
9.3.3. Land-Based
9.3.4. Space-Based
9.3.5. Portable/Handheld
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Aerospace & Defense
9.4.2. Submarine & Underwater Navigation
9.4.3. Autonomous Vehicles
9.4.4. Space Exploration
9.4.5. Industrial Positioning & Mapping
9.4.6. Infrastructure Monitoring
9.5. Market Analysis, Insights and Forecast - by End Use
9.5.1. Military & Defense Organizations
9.5.2. Government Agencies
9.5.3. Space Agencies
9.5.4. Research Institutions & Universities
9.5.5. Commercial Enterprises
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Quantum Sensors
10.1.2. Supporting Hardware
10.1.3. Software
10.1.4. Control Systems
10.1.5. Others
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Cold Atom Interferometry
10.2.2. Optical Atomic Clocks
10.2.3. NV-Diamond Sensors
10.2.4. SQUID-Based Sensors
10.2.5. Hybrid Quantum Technologies
10.3. Market Analysis, Insights and Forecast - by Platform
10.3.1. Airborne
10.3.2. Naval
10.3.3. Land-Based
10.3.4. Space-Based
10.3.5. Portable/Handheld
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Aerospace & Defense
10.4.2. Submarine & Underwater Navigation
10.4.3. Autonomous Vehicles
10.4.4. Space Exploration
10.4.5. Industrial Positioning & Mapping
10.4.6. Infrastructure Monitoring
10.5. Market Analysis, Insights and Forecast - by End Use
10.5.1. Military & Defense Organizations
10.5.2. Government Agencies
10.5.3. Space Agencies
10.5.4. Research Institutions & Universities
10.5.5. Commercial Enterprises
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Quantum Navigation Systems Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Quantum Navigation Systems Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Quantum Navigation Systems Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Quantum Navigation Systems Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Quantum Navigation Systems Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Quantum Navigation Systems Market Revenue (Billion), by Platform 2026 & 2034
Figure 7: North America Quantum Navigation Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 8: North America Quantum Navigation Systems Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Quantum Navigation Systems Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Quantum Navigation Systems Market Revenue (Billion), by End Use 2026 & 2034
Figure 11: North America Quantum Navigation Systems Market Revenue Share (%), by End Use 2026 & 2034
Figure 12: North America Quantum Navigation Systems Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Quantum Navigation Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Quantum Navigation Systems Market Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Quantum Navigation Systems Market Revenue Share (%), by Component 2026 & 2034
Europe Quantum Navigation Systems Market Revenue (Billion), by Technology 2026 & 2034
List of Tables
Table 1: Quantum Navigation Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Quantum Navigation Systems Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: Quantum Navigation Systems Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 4: Quantum Navigation Systems Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Quantum Navigation Systems Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 6: Quantum Navigation Systems Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Quantum Navigation Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Quantum Navigation Systems Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America Quantum Navigation Systems Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 10: North America Quantum Navigation Systems Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Quantum Navigation Systems Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 12: North America Quantum Navigation Systems Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Quantum Navigation Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Quantum Navigation Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Quantum Navigation Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Europe Quantum Navigation Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Frequently Asked Questions
1. How big is the quantum navigation systems market in 2026?
The market is estimated at 1.63 Billion in 2026, rising from 1.30 Billion in 2025, based on a 25.4% CAGR trajectory toward 7.95 Billion by 2033. Defense PNT modernization and GPS-denied navigation requirements drive the bulk of current revenue.
2. What is the fastest-growing quantum navigation technology?
Cold atom interferometry is the fastest-growing technology at 29.8% CAGR, favored for airborne and naval programs because it delivers drift rates below 0.001 nm/s². Optical atomic clocks follow closely on holdover requirements exceeding 100 hours.
3. Which region leads quantum navigation adoption?
North America leads with approximately 38% share, supported by U.S. DoD assured-PNT funding and NDAA quantum sensing allocations. Europe follows at ~27%, with Asia-Pacific at ~22% driven by state-backed quantum programs.
4. Who are the leading quantum navigation vendors?
Defense primes BAE Systems, RTX, Thales, and Northrop Grumman lead system integration, while specialists like Q-CTRL, Vector Atomic, Infleqtion, and Safran hold component and software positions. Honeywell competes across commercial and defense segments.
5. What limits quantum navigation market growth?
High unit costs, limited production scale, a shortage of quantum physicists, and export controls on cold-atom technology constrain near-term growth. Most platforms remain at TRL 5–7, with 9–14 month component lead times capping procurement velocity.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the quantum navigation value chain, including quantum sensor component manufacturers, precision laser and vacuum subsystem suppliers, system integrators and defense primes, and government research laboratories. Decision-maker designations interviewed include VP-level PNT program leads, Heads of Quantum Sensing R&D, Technical Directors for inertial navigation, and Commercial Operations Leads at defense contractors. Fieldwork targeted platform-level procurement and qualification cycles to validate adoption timelines and unit economics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
PNT Program & Technical Directors
40%
R&D & Quantum Sensing Heads
30%
Procurement & Sourcing Leads
20%
Regulatory & Export Compliance
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Quantum Sensor & Component Manufacturers
40%
Defense Primes & System Integrators
32%
Research Institutions & Government Labs
18%
Distributors & Commercial Integrators
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade trade flows for precision instrumentation and optical components, WTO and US ITC export-control filings, Eurostat industrial data, and corporate annual reports (10-K, SEC filings, investor presentations). Patent databases and recognized technical standards bodies — including IEEE, ISO technical committees, and defense PNT standards organizations — were used to corroborate technology readiness and vendor capability claims. No competitor market-research publications are cited as validation sources.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down macroeconomic and defense-budget allocation models against Bottom-Up manufacturer capacity, unit pricing, and end-use consumption modeling. Defense PNT budget lines, quantum sensing program awards, and platform deployment counts are reconciled against supplier shipment estimates to produce base-year valuations and compound projections.


 Quantum Navigation Systems Market