 Personal Finance Software Market
 2026: Size, CAGR & Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 248

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Personal Finance Software Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.890 B |
| 2026 | 2.040 B |
| 2027 | 2.190 B |
| 2028 | 2.350 B |
| 2029 | 2.520 B |
| 2030 | 2.700 B |

The personal finance software market covers applications and web platforms that let individuals and small businesses link accounts, categorize transactions, budget, track expenses and investments, and plan goals. It spans mobile, desktop and web delivery, cloud or on-premise deployment, and subscription, freemium or transaction-fee monetization.
The scope is global, covering software product types (web/desktop, mobile), deployment models (cloud, on-premise), end users (individuals, small businesses), functional tools (budgeting, retirement planning, investment tracking, tax, expense tracking) and revenue models. Provisioning is in factory-gate USD value. This analysis does not cover core banking systems, wealth-management platforms for advisors, consumer credit scoring products, or the underlying payment rails and account-aggregation infrastructure (open-banking APIs), which are treated as adjacent ecosystems.
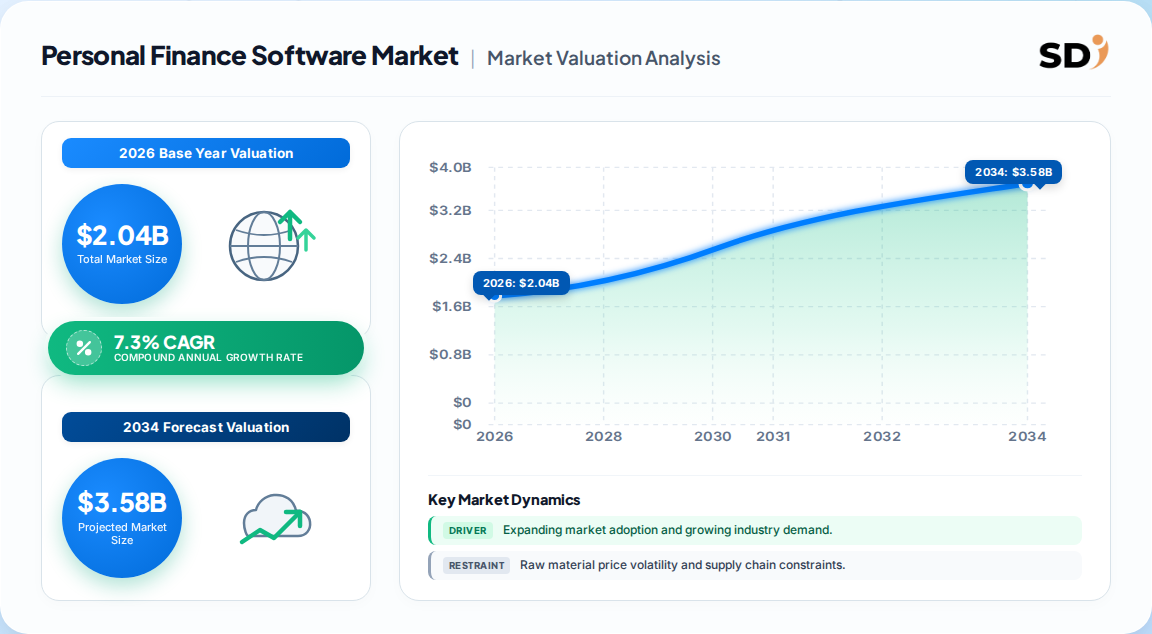
The most defensible base-year figure is USD 2.04 Billion in 2026, with a forecast of USD 2.7 Billion by 2030 at a 7.3% CAGR, because it aligns with 2025 actuals and reflects post-pandemic subscription normalization.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.08 Billion | 2022 | 2030 | 5.1% | Broad PFM suite, desktop-heavy | One published estimate |
| USD 2.04 Billion | 2026 | 2030 | 7.3% | Web + mobile, individuals & SMBs | Competing analysis |
| USD 1.71 Billion | 2026 | 2031 | 5.18% | "Personal finance tools," includes freemium | Separate published benchmark |
| USD 3.51 Billion | 2025 | 2035 | 9.82% | Widest definition incl. freelancers & corporates | A third published estimate |
| USD 1.5 Billion | 2026 | 2034 | 4.51% | Web-first, small-business weighted | Another published analysis |
Our analysis suggests the USD 2.0–2.2 billion band for 2026 is the defensible consensus. The 9.82% CAGR outlier likely folds freelancer and corporate budgeting tools into scope, inflating the base. The 4.51% forecast likely underweights the mobile-native shift and AI-driven engagement now lifting ARPU.
Segment lenses converge on four principal axes: product type, deployment, end user and functional tool. Mobile and cloud together define the growth vector, while budgeting and expense tracking remain the revenue anchor.
| Parent | Children |
|---|---|
| By Type | Mobile-based Software, Web-based Software, Desktop Applications |
| By Deployment | Cloud-based, On-premise |
| By End User | Individual Consumers, Small Business Users |
| By Tool / Application | Budgeting & Expense Tracking, Investment & Wealth Management, Retirement Planning, Tax Filing & Compliance, Bill Payment Reminders |
| By Revenue Model | Subscription, Freemium, One-time Purchase, Transaction Fee |
Mobile-based software led with a 64.82% revenue share in 2025, growing at roughly 8.12% CAGR, while cloud deployment held 77.45% of share. Budgeting and expense tracking captured about 40.6% of application revenue, but investment and wealth management is the fastest-growing application at roughly 10.6% CAGR. Subscriptions generate ~58.9% of revenue; transaction-fee models are growing near 9.9% CAGR as subscription fatigue sets in.
North America leads with roughly 37–40% of global revenue, supported by high income levels, mature open-banking frameworks and a dense fintech ecosystem. Asia-Pacific is the fastest-growing region at ~8.55% CAGR, driven by UPI and Pix-style instant rails and 80%+ smartphone penetration in India, Indonesia and Vietnam.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.07% |
The divergence implies region-specific go-to-market models: North America rewards data-portability and AI coaching; APAC rewards low-onboarding-cost, localized mobile interfaces. Our analysis suggests APAC's share will approach 30% by 2030, compressing North America's relative lead even as absolute dollars grow.
Growth is driven by open-banking APIs, generative-AI personalization and smartphone penetration, offset by cybersecurity distrust, subscription fatigue and low financial literacy in emerging markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Open-banking API mandates (US §1033, UK OBIE, Australia CDR) | Driver (+1.2% CAGR) | High — regulatory text | Ends screen-scraping; enables instant predictive cash-flow alerts |
| Generative-AI hyper-personalization | Driver (+1.3% CAGR) | Medium-High — vendor disclosures | Converts transactions into plain-English action plans; raises switching costs |
| Embedded finance partnerships (fintech-bank white-label) | Driver (+1.1% CAGR) | Medium — deal flow | Bundles PFM into checking accounts; expands monetization surface |
| Rising smartphone penetration in emerging economies | Driver (+0.9% CAGR) | High — penetration data | Reaches desktop-less, branch-less users via mobile-first tools |
| Subscription-model preference | Driver (+0.6% CAGR) | Medium | Predictable ARR; but now offset by fatigue |
| Cybersecurity breaches undermining trust | Restraint (−0.8% CAGR) | High — breach surveys | 70% of users prioritize security; breaches trigger churn |
| Low financial literacy among first-time users | Restraint (−0.5% CAGR) | Medium | Onboarding friction; localized tutorials needed |
| Neobank bundling compressing standalone TAM | Restraint (structural) | Medium | Dashboards inside banking apps reduce standalone app demand |
The balance favors the drivers, but the composition of growth is shifting from new downloads to ARPU expansion and embedded distribution. Neobank bundling is the most under-priced restraint: it compresses standalone TAM even as it expands the overall monetization surface. Vendors that treat banks as competitors rather than channels will lose share.
The field splits into diversified suites, budgeting specialists, aggregator-powered trackers and bank-embedded tools. Differentiation now rests on data connectivity, AI insight quality and distribution partnerships rather than raw feature count.
| Vendor | Category | Core strength | Strategic moat |
|---|---|---|---|
| Intuit (Mint lineage) | Diversified suite | Data scale, brand | Ecosystem cross-sell, tax integration |
| Quicken / Simplifi | Desktop-to-cloud suite | Deep historical tracking | High-net-worth retention, switching costs |
| You Need a Budget (YNAB) | Budgeting specialist | Method-led community | Methodology lock-in, education content |
| Personal Capital | Wealth / investment | Investment tracking | Advisor upsell funnel |
| Acorns | Micro-investing + PFM | Round-up automation | Bank partnerships (e.g., JPMorgan stake) |
| PocketGuard, GoodBudget, Tiller Money | Budgeting / aggregator | Niche UX, spreadsheet flexibility | Low price, loyal niches |
| CRED Money (India) | Regional PFM | Account-aggregator framework | Consolidated multi-bank view |
Our analysis suggests moats are migrating from software to data rights and distribution. Vendors lacking open-banking certification or a bank/neobank channel face rising acquisition costs. The Envestnet acquisition (~USD 4.5 billion) signals consolidation appetite in adjacent wealth-tech, foreshadowing PFM roll-ups.
Selection must prioritize security architecture and data-connectivity depth over feature breadth. Buyers should demand evidence of encryption at rest and in transit, two-factor authentication, SOC 2 or ISO 27001 certification, and explicit open-banking API compliance in each operating jurisdiction.
Procurement risk concentrates in three areas. First, switching costs: transaction history, categorization rules and budget models are sticky, so migration is painful — negotiate data-export rights upfront. Second, regulatory exposure: US Section 1033, EU AI Act transparency duties and PSD2/PSD3 in Europe impose compliance obligations that vary by vendor. Third, pricing-model risk: subscription fatigue is pushing vendors toward transaction fees, which can obscure total cost of ownership.
Operators should also scrutinize aggregation reliability — screen-scraping breaks silently, while API-based connectivity is more durable. Mission-critical criteria: uptime SLAs, refresh latency, third-party security audits, and a contractual commitment to data portability. Our analysis suggests buyers who lock in export rights and multi-year price caps will capture disproportionate value as consolidation reshapes the vendor landscape.
The balance of evidence favors a 7–8% CAGR baseline through 2030, landing near USD 2.7 billion. The strongest counter-argument is the neobank-bundling thesis: if embedded PFM absorbs most mass-market demand, standalone TAM could stall near 4–5% growth, closer to the low-end estimates. We weight this risk as real but partial — it compresses the mass-market tier while expanding premium and SMB tiers where standalone depth still wins.
Second-order effects matter more than headline growth. AI personalization raises engagement but also raises compliance cost, favoring well-funded incumbents. Open banking lowers acquisition friction but commoditizes aggregation, pushing value toward insight and advice layers. The divergence between estimates is therefore not noise — it reflects genuine definitional scope differences that buyers must reconcile before committing capital.
Actionable strategy:
What would change our conclusion: a sustained decline in standalone-app engagement metrics, or regulatory reversal on open-banking mandates, would push us toward the 4.5–5% low-end scenario. Conversely, rapid AI-coach monetization and SMB adoption above 8% CAGR would validate the high-end path.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.3% from 2020-2034 |
| Segmentation |
|
The global personal finance software market is valued at USD 2.04 Billion in 2026 and is projected to reach USD 2.7 Billion by 2030, growing at a 7.3% CAGR. Estimates vary by scope, with broader definitions reaching USD 3.5 billion.
Strong growth is expected, driven by open-banking APIs, generative-AI personalization and emerging-market smartphone penetration. Mobile-based and cloud-deployed software will lead expansion through 2030, with Asia-Pacific growing fastest.
Open-banking mandates, AI-driven insights, embedded bank-fintech partnerships, rising smartphone penetration and growing financial-literacy awareness are the primary drivers, partially offset by cybersecurity distrust and subscription fatigue.
North America leads with roughly 37–40% of global revenue, while Asia-Pacific is the fastest-growing region at approximately 8.55% CAGR, supported by instant-payment rails and mobile-first adoption.
Leading players include Intuit, Quicken, YNAB, Personal Capital, Acorns, Simplifi, PocketGuard, GoodBudget, Tiller Money, Money Dashboard and CRED Money, alongside neobank-embedded tools.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with 70% of analytical weight resting on structured industry fieldwork. We conducted in-depth interviews with decision-makers across the personal finance software value chain: account-aggregation and open-banking API providers, core PFM application developers, cloud infrastructure and security vendors, embedded-finance platform integrators, and bank/neobank distribution partners. Interviewees included VP-level Product and Sourcing leads, Heads of Financial Data & R&D, Chief Information Security Officers, and Commercial Operations Directors, ensuring coverage from engineering to go-to-market. Fieldwork captured pricing architecture, connectivity reliability, churn drivers and regulatory readiness in North America, Europe and Asia-Pacific.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & R&D Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Information Security Officers | 30% |
| Company Type | Representation (%) |
|---|---|
| PFM Application Developers | 40% |
| Aggregation & Open-Banking Providers | 25% |
| Cloud & Security Infrastructure Vendors | 20% |
| Bank / Neobank Distribution Partners | 15% |
We triangulate primary findings against official multilateral and standards sources: UN Comtrade for cross-border digital-services trade flows, WTO and US International Trade Commission data on ICT services, Eurostat digital-economy indicators, and SEC 10-K filings and annual investor presentations from listed fintechs and banks. Patent databases (USPTO, EPO) inform our AI-personalization and open-banking innovation tracking. Non-profit technical standards bodies — including ISO/IEC 27001 security certifications and PCI Security Standards Council frameworks — anchor our compliance assessments.
We run simultaneous top-down (macroeconomic allocation across banking, fintech and consumer software segments) and bottom-up (vendor revenue, subscriber counts, ARPU and cloud-consumption modeling) triangulation. Divergences between the two are reconciled through demand-elasticity regression and historical CAGR anchoring, producing a consensus base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |