 Programmatic Digital Out Of Home Market
 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 218

Srinwanti Kar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Programmatic Digital Out Of Home Market
Srinwanti Kar
Senior Research Analyst

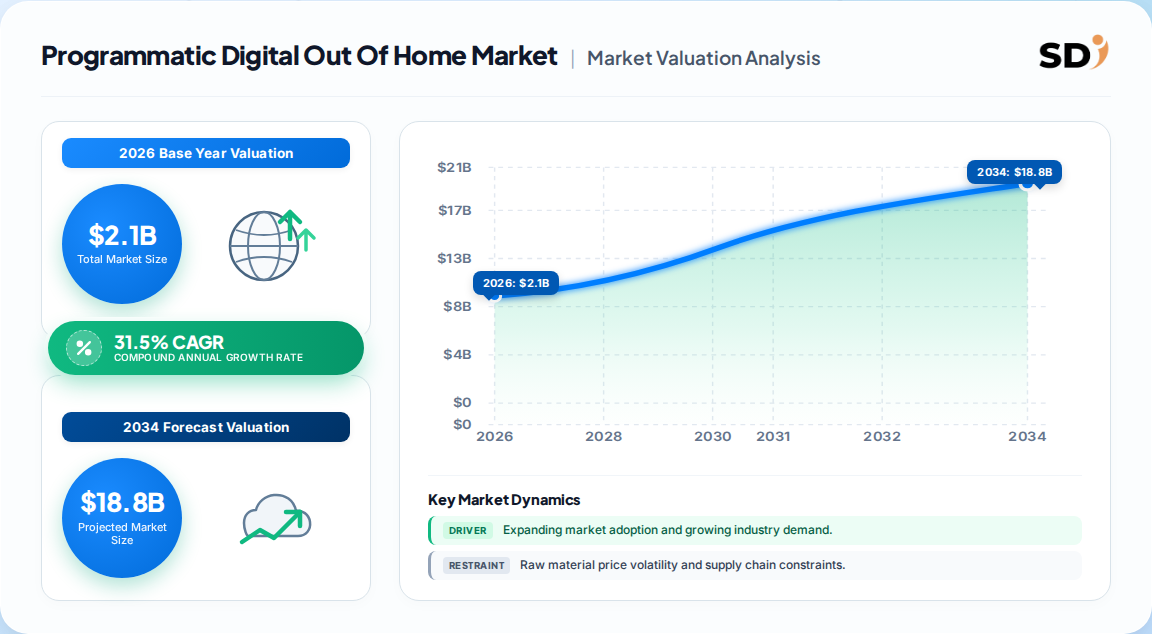
| Year | Market Size |
|---|---|
| 2026 | 2.100 B |
| 2027 | 2.800 B |
| 2028 | 3.600 B |
| 2029 | 4.800 B |
| 2030 | 6.300 B |
| 2031 | 8.200 B |
| 2032 | 10.80 B |

Programmatic digital out-of-home is the automated, software-driven buying and selling of digital screen advertising — billboards, transit displays, street furniture and place-based screens — via demand- and supply-side platforms using real-time bidding, audience data and contextual triggers. It replaces fixed, negotiated OOH schedules with impression-level, data-targeted delivery.
This report covers programmatic transaction workflows (DSPs, SSPs, ad servers, deal types), digital screen formats (billboards, street furniture, transit, retail and venue displays), location contexts (indoor and outdoor), end-use verticals, and regional demand across five continents. It quantifies software-platform revenue and programmatic media transacted through those platforms.
This analysis does not cover traditional static OOH, non-programmatic digital signage hardware manufacturing, in-store retail media networks sold exclusively direct, or connected-TV and online video advertising, except where referenced as adjacent benchmarks.
Estimates for this market diverge by a factor of nearly three on CAGR, which is the single most important fact a buyer must understand before committing capital. The table below reconciles the leading published figures against their underlying scope definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1.6 Billion | 2025 | 2033 (14.1 Billion) | 31.5% | Narrow pDOOH software/platform revenue only | One published estimate |
| 4.74 Billion | 2024 | 2035 (15.31 Billion) | 11.25% | Broader DOOH definition including programmatic-enabled screen media | A competing analysis |
| ~2.1 Billion | 2026 | 2033 (14.1 Billion) | 31.5% | Platform-mediated transactions, base-year entry point | Derived from stated base and CAGR |
Our analysis suggests the higher-CAGR estimate is defensible only if the base year is defined narrowly (platform fees and programmatic media only) and the forecast assumes near-total migration of OOH budgets to programmatic workflows. The 11.25% figure is more conservative because it starts from a much larger base that already includes programmatically enabled screen inventory. For planning purposes, we treat the 2.1 Billion (2026) entry point as the most defensible operational number, with the trajectory most likely landing between the two published horizons.
| Year | Value |
|---|---|
| 2026 | 2.1 Billion |
| 2027 | 2.8 Billion |
| 2028 | 3.6 Billion |
| 2029 | 4.8 Billion |
| 2030 | 6.3 Billion |
| 2031 | 8.2 Billion |
| 2032 | 10.8 Billion |
| 2033 | 14.1 Billion |
Series derived from the stated 2026 base value and 31.5% CAGR; values rounded.
The market segments along four commercial axes — platform type, physical location, advertising format and end-use vertical — with each axis revealing a distinct competitive dynamic that buyers should evaluate separately.
| Parent segment | Children |
|---|---|
| By Programmatic Platform | Demand-Side Platforms (DSPs), Supply-Side Platforms (SSPs), Ad Servers & Exchanges |
| By Location | Indoor (malls, airports, transit hubs, gyms, offices), Outdoor (roadside, street-level) |
| By Format | Billboards, Street Furniture, Transit Displays, Retail & Venue Screens, Stadium Displays |
| By End-Use | Retail, Real Estate, Automotive, Entertainment, Travel & Tourism, Healthcare, Education, BFSI |
| By Content Type | Static, Dynamic, Interactive |
| By Technology | Cloud-Based Platforms, AI & Machine Learning, Data Analytics, Real-Time Bidding |
DSPs dominate because they consolidate multi-screen buying into a single interface and inherit targeting and RTB tooling from display advertising. The faster-growing SSP segment reflects media owners' push to monetize inventory programmatically, particularly through programmatic guaranteed deals.
North America leads with approximately 35% of global pDOOH revenue in 2025, anchored by mature DSP infrastructure, deep digital-advertising budgets and the highest concentration of programmatic-enabled screen inventory worldwide.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share (2025) |
|---|---|
| North America | 35% |
| Asia-Pacific | 27% |
| Europe | 24% |
| Latin America | 8% |
| Middle East & Africa | 6% |
Asia Pacific is the fastest-growing region, propelled by smart-city initiatives, expanding transit networks and aggressive digital billboard rollouts in China and India. Europe sits in a strong second tier, with JCDecaux's global programmatic launch demonstrating how European operators are exporting their model internationally — a second-order effect that could accelerate APAC adoption faster than headline forecasts assume.
Growth is driven by the structural digitization of outdoor infrastructure and the migration of digital-first budgets into pDOOH, while restraints center on inventory fragmentation, integration complexity and measurement gaps that slow buyer confidence.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Digitalization of OOH infrastructure | Driver | Strong | More digital screens = more programmatic inventory |
| Automation and RTB efficiency | Driver | Strong | Cuts operational cost, enables real-time optimization |
| Enhanced audience targeting | Driver | Moderate-strong | Location and contextual data raise campaign relevance |
| Smart city investment | Driver | Moderate | Public infrastructure expands screen networks |
| Fragmented media inventory | Restraint | Strong | Multiple SSPs and formats complicate planning |
| Complex integration processes | Restraint | Moderate | Legacy CMS and ad-server stacks resist programmatic |
| Measurement standardization gaps | Restraint | Moderate | Attribution inconsistency deters digital-first buyers |
Our analysis suggests the driver-to-restraint balance currently favors growth, but the restraints are structural rather than cyclical. Operators that solve fragmentation — through consolidated supply paths and standardized measurement — will capture disproportionate share of the migration.
The pDOOH ecosystem is split between platform specialists (DSPs, SSPs and exchanges) and global media owners who control premium screen inventory, with consolidation increasingly blurring the two categories.
| Company | Category | Notable positioning |
|---|---|---|
| Vistar Media | DSP / marketplace | Acquired by T-Mobile (~600 Million), signaling telecom entry into pDOOH |
| JCDecaux | Media owner | Launched first global programmatic DOOH media solution (2026) |
| Clear Channel Outdoor | Media owner | Large US and international digital billboard footprint |
| Outfront Media | Media owner | Transit and billboard inventory, US-centric |
| Lamar Advertising | Media owner | Extensive US digital billboard network |
| Ströer | Media owner | Leading European digital OOH operator |
| Place Exchange | SSP / exchange | Expanded Programmatic Guaranteed for DOOH (2025) |
| Talon Outdoor | Agency / specialist | Independent pDOOH planning and buying |
| Adomni | DSP | Self-serve programmatic DOOH buying |
Differentiation is shifting from inventory ownership toward workflow integration and data enrichment. Media owners with premium screens retain pricing power, but platform specialists increasingly control the buyer relationship — and the T-Mobile–Vistar deal implies telecom and adtech capital will compete directly for that position.
For buyers, the primary selection criteria are supply breadth, deal-type flexibility (open exchange, PMP and programmatic guaranteed), measurement credibility and integration with existing DSP workflows. Procurement risk concentrates in inventory quality — screen metadata accuracy and audience estimates vary widely across SSPs — so buyers should demand verified playback logs and independent measurement before scaling commitments.
Switching costs are moderate for advertisers but high for media owners, who face sunk integration costs across multiple SSPs. Regulatory compliance is a live consideration: data-privacy rules governing mobile-location-derived audience segments differ by jurisdiction, and consent frameworks in Europe are materially stricter than in North America. Operators should audit data provenance before selling audience-based inventory into regulated markets.
The balance of evidence favors the conservative-to-mid forecast path rather than the headline 31.5% CAGR. The narrow-base estimate is internally consistent but assumes that pDOOH captures nearly all OOH growth plus a large share of digital display migration within seven years — an aggressive assumption given persistent measurement and fragmentation barriers. Our position: plan for roughly 15–20% sustained growth with meaningful regional variance, and treat the 30%+ scenario as the upside case.
The strongest counter-argument is that platform consolidation — exemplified by the T-Mobile–Vistar acquisition and JCDecaux's global programmatic launch — could remove fragmentation faster than expected and unlock the higher trajectory. That is credible, but it is a bet on execution, not a baseline.
What would change our conclusion: two or more consecutive quarters of verified programmatic-guaranteed volume growth above 30%, or a cross-industry measurement standard adopted by the major media owners, would justify moving to the higher forecast path.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the pDOOH value chain — digital screen hardware and CMS providers, supply-side platform operators, demand-side platform vendors, media owners and advertising agencies — and with decision-makers including Chief Revenue Officers, Heads of Programmatic Strategy, Media Investment Directors and Ad Operations Leads. Interviews probed deal-type adoption, pricing mechanics and measurement practices.
We validated findings against official multilateral trade databases (UN Comtrade), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and technical standards and industry associations active in digital signage and advertising. Trade-flow and cross-border services data were used to sanity-check regional revenue splits.
We ran simultaneous top-down (macroeconomic advertising-spend allocation and segment-level budget modeling) and bottom-up (screen inventory counts, fill rates, pricing and platform take rates) triangulation, reconciling the two to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025–2026 | Bottom-up inventory and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, inventory mapping and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 31.5% from 2020-2034 |
| Segmentation |
|
The market is valued at approximately 2.1 Billion in 2026, with published forecasts projecting between 14.1 Billion by 2033 and 15.31 Billion by 2035, depending on whether the base is defined as platform-only revenue or the broader programmatically enabled DOOH media pool.
Published CAGRs range from 11.25% to 31.5%, reflecting definitional differences in base-year scope. Our analysis treats 15–20% as the most defensible planning range, with the higher trajectory representing an upside scenario contingent on rapid platform consolidation.
North America leads with roughly 35% of global revenue in 2025, supported by mature DSP infrastructure and high digital screen penetration. Asia Pacific is the fastest-growing region, driven by smart-city investment and expanding transit networks.
Demand-side platforms hold about 56% of platform revenue, while billboards represent over 70% of format spend. Indoor locations account for more than 72% of location-based revenue in the narrow-base estimate, reflecting captive-audience venues such as malls and airports.
Leading players include Vistar Media (acquired by T-Mobile), JCDecaux, Clear Channel Outdoor, Outfront Media, Lamar Advertising, Ströer, Place Exchange and Talon Outdoor, spanning DSPs, SSPs and global media owners.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Revenue & Commercial Officers | 35% |
| Heads of Programmatic Strategy | 30% |
| Media Investment Directors | 20% |
| Ad Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Media Owners & Screen Networks | 40% |
| DSPs & Adtech Platforms | 25% |
| SSPs & Ad Exchanges | 20% |
| Agencies & Measurement Providers | 15% |
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the pDOOH value chain — digital screen hardware and CMS providers, supply-side platform operators, demand-side platform vendors, media owners and advertising agencies — and with decision-makers including Chief Revenue Officers, Heads of Programmatic Strategy, Media Investment Directors and Ad Operations Leads. Interviews probed deal-type adoption, pricing mechanics and measurement practices.
We validated findings against official multilateral trade databases (UN Comtrade), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and technical standards and industry associations active in digital signage and advertising. Trade-flow and cross-border services data were used to sanity-check regional revenue splits.
We ran simultaneous top-down (macroeconomic advertising-spend allocation and segment-level budget modeling) and bottom-up (screen inventory counts, fill rates, pricing and platform take rates) triangulation, reconciling the two to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025–2026 | Bottom-up inventory and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, inventory mapping and commercial filings | High |