 Online Gaming Market
: Size, Growth & Outlook 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 205

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Online Gaming Market
Srinwanti Kar
Senior Research Analyst

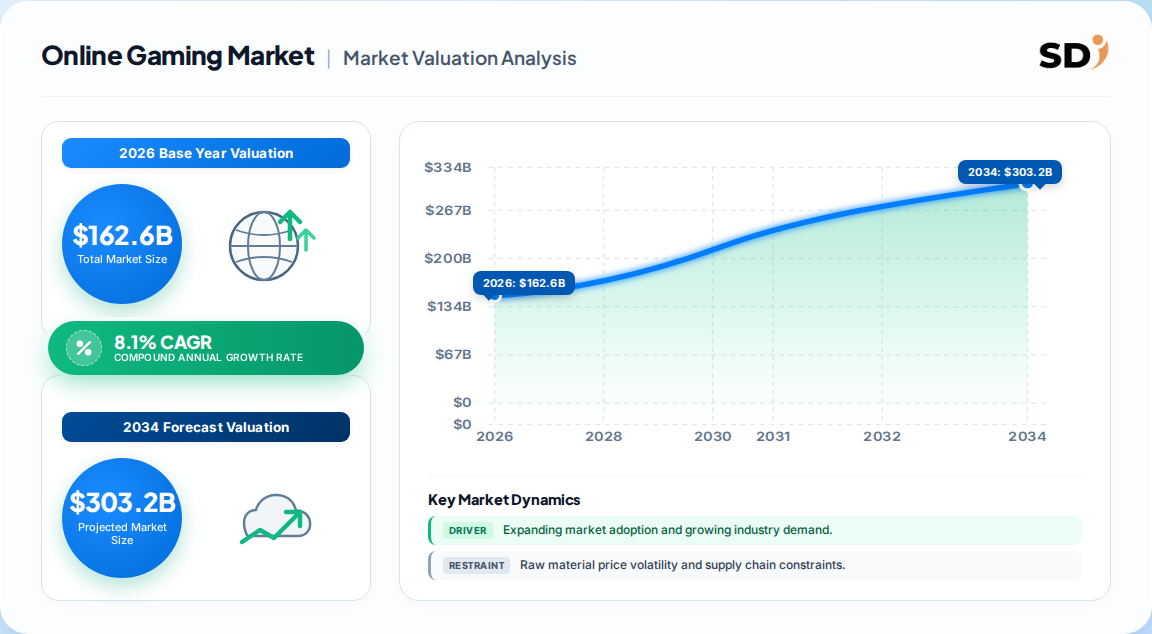
| Year | Market Size |
|---|---|
| 2025 | 144.6 B |
| 2026 | 162.6 B |
| 2027 | 175.8 B |
| 2028 | 190.0 B |
| 2029 | 205.4 B |
| 2030 | 222.1 B |
| 2031 | 240.0 B |

The online gaming market encompasses interactive digital entertainment delivered over the internet, spanning action, shooter, role-playing, and strategy genres across smartphones, computers, and consoles. It includes free-to-play, subscription, and pay-to-play revenue models, powered by cloud infrastructure, social features, and live-service content updates.
This analysis covers the global online gaming market across all major genres, device types, and revenue models, including mobile, PC, and console online gaming. It emphasizes the 2026–2033 forecast period.
This analysis does not cover traditional offline video game sales, gaming hardware manufacturing, esports betting, or gambling-adjacent services. Nor does it cover broad media and entertainment categories outside interactive gaming.
Estimates of the online gaming market vary meaningfully in scope and horizon. The table below compares the leading published benchmarks, which diverge largely because of definitional differences in device coverage, revenue inclusion, and whether hardware is counted.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 144.6 Billion | 2025 | 2033 | 8.1% | Global online gaming, all devices, digital revenue | One published market-research estimate |
| USD 162.6 Billion | 2026 | 2033 | 8.1% | Online gaming platforms, excluding hardware | Same source, forecast base |
| USD 560.55 Billion | 2026 | 2031 | 6.32% | Total games market, including hardware and accessories | A competing analysis (broad games definition) |
| USD 224.7 Billion | 2026 | 2032 | 8.87% | Gaming market, mobile-first, includes console | Another competing estimate |
The USD 162.6 billion figure for 2026 is the most defensible base because it isolates online, internet-delivered gaming without double-counting hardware or console shipments. The broader USD 560 billion figure captures the entire games ecosystem including physical sales and accessories — useful for context but not directly comparable. Our analysis suggests the narrower, platform-centric definition better reflects the buyer's operational reality.
The online gaming market is segmented primarily by genre, device, and revenue model, each reflecting distinct monetization strategies and audience demographics.
| Parent Segment | Children |
|---|---|
| By Genre | Action & Adventure, Shooter, MOBA, Real-Time Strategy, Role-Playing Games |
| By Device | Smartphones & Tablets, Computers, Gaming Consoles |
| By Revenue Model | Free-to-Play, Pay-to-Play/Premium, Subscription/Game-Pass |
| By Player Age Group | Under 18, 18–35, 36–50, 50+ |
Shooter and action/adventure genres command the largest revenue pools, while cloud gaming and subscription models represent the fastest-growing delivery and monetization channels. Mobile remains the volume leader, but console and PC segments generate higher ARPU. Our analysis suggests the free-to-play model's dominance creates a structural monetization ceiling unless live-service spending rises proportionally.
Asia Pacific leads the global online gaming market, holding an estimated 38.6% revenue share in 2025, driven by China, Japan, South Korea, and India's rapidly expanding mobile gamer base.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.42% |
| North America | 0.25% |
| Europe | 0.2% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Regional shares are shifting gradually. While Asia Pacific's share is dominant, the Middle East is forecast as the fastest-growing region, with several published estimates projecting nearly 10% CAGR through 2032. Europe and North America remain high-ARPU markets where monetization depth compensates for slower user growth. Our analysis suggests the next competitive battleground is Southeast Asia, where smartphone penetration is rising fastest but ARPU remains low.
Growth in the online gaming market is driven by smartphone proliferation, affordable data, and cloud infrastructure — offset by regulatory scrutiny and rising user-acquisition costs.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Smartphone penetration & 5G rollout | Driver | Strong | Expands addressable user base across emerging markets |
| Cloud gaming adoption | Driver | Moderate | Removes hardware barriers, lowers entry cost |
| Mobile-first monetization surge | Driver | Strong | Recurring in-app purchases and battle passes lift ARPU |
| Regulatory scrutiny (approval quotas, play-time limits) | Restraint | Strong | Constrains monetization in China and other regulated markets |
| Privacy rules (iOS ATT) | Restraint | Moderate | Inflates user-acquisition costs for free-to-play publishers |
| AAA talent shortage | Restraint | Moderate | Delays development cycles, raising production costs |
The balance of evidence favors sustained growth, but the nature of that growth is changing. Volume expansion from new smartphone users is slowing in developed markets, while monetization depth — through live services, subscriptions, and in-game advertising — is becoming the primary revenue lever. Our analysis suggests publishers that fail to build recurrent spending relationships will face margin compression even as top-line market growth continues.
Competition is medium-concentrated, with a mix of platform holders, publishers, and hardware-adjacent players competing across devices and geographies.
| Company | Primary Strength | Differentiation |
|---|---|---|
| Tencent Holdings | Mobile publishing & social gaming | Dominant in China; global mobile franchises |
| Sony Group | Console ecosystem (PlayStation) | Exclusive titles and integrated online services |
| Microsoft | Xbox ecosystem & cloud gaming | Game Pass subscription model; Azure cloud infrastructure |
| NetEase | PC and mobile game development | Strong China presence; diversified portfolio |
| Apple | iOS platform distribution | App Store monetization and privacy control |
Competitive moats rest on exclusive IP, platform lock-in, and live-service communities. Sony and Microsoft compete on ecosystem depth and subscription value, while Tencent and NetEase leverage scale and regional dominance. Our analysis suggests cloud gaming infrastructure will become a critical differentiator, with Microsoft's Azure advantage potentially reshaping competitive dynamics by 2030.
Buyers and operators must prioritize three areas: regulatory compliance, monetization model design, and infrastructure scalability. Regulatory risk is highest in China and the EU, where approval processes and privacy rules directly affect launch timelines and user-acquisition economics. Operators should build compliance into product roadmaps rather than treat it as an afterthought.
Monetization model selection is equally critical. Free-to-play dominates volume but requires sophisticated live-service operations to sustain revenue. Subscription models offer predictability but demand a compelling content pipeline. Switching costs are moderate for consumers but high for publishers locked into platform ecosystems.
Procurement risk centers on cloud infrastructure costs, which are rising and squeezing margins for free-to-play publishers. Buyers should negotiate long-term cloud contracts and diversify delivery partners to mitigate cost exposure. The full report provides detailed procurement frameworks and vendor scorecards.
The balance of evidence favors a moderately bullish outlook for the online gaming market, with 8.1% CAGR representing a realistic central case. The strongest counter-argument is that regulatory tightening and privacy-driven acquisition costs could suppress monetization below current forecasts — particularly in China, where approval quotas remain a structural constraint. However, this risk is partially offset by growth in Southeast Asia and the Middle East, where smartphone adoption is still rising.
Our analysis identifies a structural shift: the market is moving from user-acquisition-driven growth to monetization-depth-driven growth. Publishers that master live-service operations, subscription bundles, and in-game advertising will capture disproportionate value. Those relying solely on new user acquisition will face rising costs and thinning margins. The cloud gaming segment, growing at over 25% CAGR, represents the most significant long-term disruption to console and PC ecosystems.
Actionable Strategy:
What would change our conclusion: A significant escalation in Chinese regulatory restrictions, or a faster-than-expected collapse in mobile user acquisition economics, would push forecasts toward the low end. Conversely, accelerated cloud gaming adoption and successful subscription bundling could lift growth above 9%.
This study employed a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the gaming value chain: game publishers, platform operators, cloud infrastructure providers, and mobile device manufacturers. Decision-makers interviewed included VP-level executives in publishing, Heads of Live Operations, Technical Directors, and Commercial Strategy Leads.
Secondary validation drew on corporate annual filings (10-K, SEC), investor presentations from publicly listed gaming companies, patent databases, and official trade statistics from UN Comtrade and Eurostat. We also referenced industry association publications and regulatory filings from relevant jurisdictions.
We applied simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic gaming spend data and segment revenue splits. Bottom-up modeling triangulated publisher revenue, platform take rates, and end-user spending across devices to arrive at a reconciled market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up publisher revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border digital trade flow analysis and consumption data | High |
| Competitive Landscape | Leading market players | Annual reports, revenue mapping, commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.1% from 2020-2034 |
| Segmentation |
|
The global online gaming market is valued at approximately USD 162.6 billion in 2026, projected to reach USD 280.3 billion by 2033 at an 8.1% CAGR.
Asia Pacific holds the largest share at 38.6% in 2025, driven by China, Japan, South Korea, and India's expanding mobile gamer base.
Cloud gaming is the fastest-growing delivery segment, with subscription and game-pass models expanding at over 13% CAGR.
Tencent, Sony, Microsoft, NetEase, and Apple lead the market, competing on exclusive IP, platform ecosystems, and live-service monetization.
Regulatory scrutiny — particularly China's approval quotas and play-time limits — and rising user-acquisition costs from privacy rules are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the gaming value chain: game publishers, platform operators, cloud infrastructure providers, and mobile device manufacturers. Decision-makers interviewed included VP-level executives in publishing, Heads of Live Operations, Technical Directors, and Commercial Strategy Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Publishing & Strategy | 35% |
| Head of Live Operations | 30% |
| Technical Directors | 20% |
| Commercial Strategy Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Publishers & Game Developers | 40% |
| Platform & Console Operators | 30% |
| Cloud Infrastructure Providers | 20% |
| Mobile Device Manufacturers | 10% |
Secondary validation drew on corporate annual filings (10-K, SEC), investor presentations from publicly listed gaming companies, patent databases, and official trade statistics from UN Comtrade and Eurostat. We also referenced industry association publications and regulatory filings from relevant jurisdictions.
We applied simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic gaming spend data and segment revenue splits. Bottom-up modeling triangulated publisher revenue, platform take rates, and end-user spending across devices to arrive at a reconciled market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up publisher revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border digital trade flow analysis and consumption data | High |
| Competitive Landscape | Leading market players | Annual reports, revenue mapping, commercial filings | High |