Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Contract Management Software Market by Deployment Mode (Cloud, On-Premise), by Component (Software, Services), by Contract Type (Buy-Side, Sell-Side, Non-Commercial), by Business Function (Procurement & Supply Chain, Legal, Sales, Finance), by Pricing Model (Subscription, Perpetual, Usage-Based), by Integration Level (Standalone CLM, Integrated Suite), by Organization Size (Large Enterprise, SME), by End-User Industry (BFSI, IT & Telecom, Healthcare & Life Sciences, Manufacturing, Retail, Government), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 198
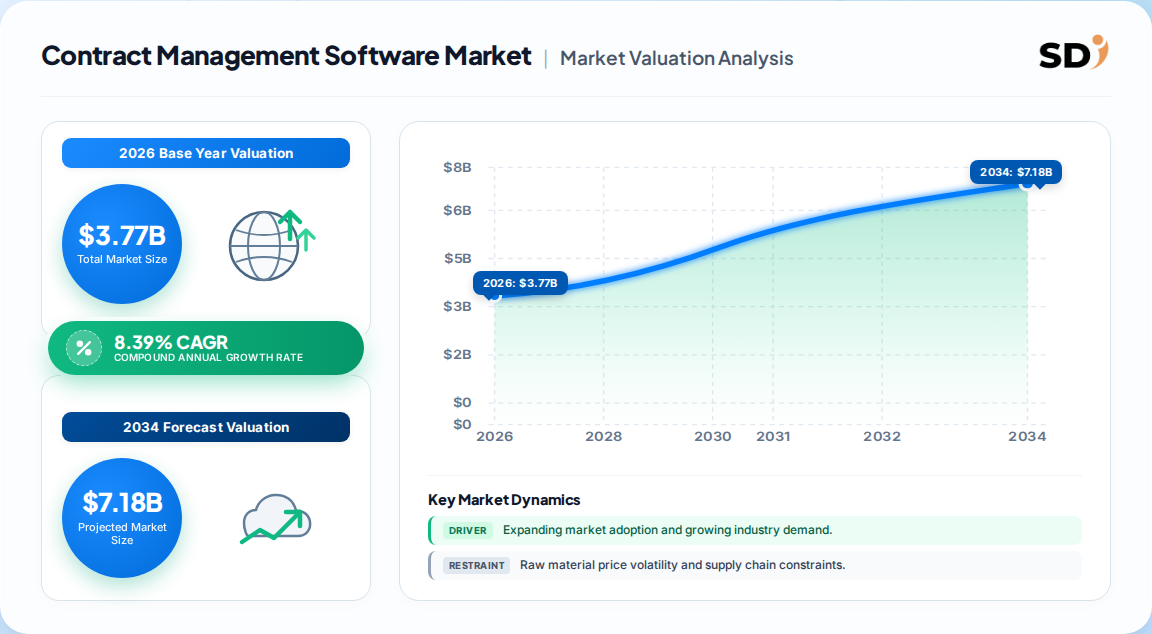
USD 3.77 Billion: Estimated global contract management software market size in 2026, up from USD 3.48 Billion in 2025. Scope: global, software and related services.
USD 5.64 Billion forecast by 2031, representing a 8.39% CAGR over the 2026–2031 period, per one aggregated industry estimate.
Cloud deployment dominates with 76.85% share in 2025; subscription pricing captured 92.08% of revenue, confirming the market's SaaS-native structure.
Procurement and supply chain is the largest business function at 33.72% share, while legal departments are the fastest-growing at a 9.48% CAGR.
North America leads with 41.05% of 2025 revenue; Asia-Pacific is the fastest-growing region at a 9.18% CAGR, driven by ERP suite integration.
Leading vendors include Icertis, DocuSign, Agiloft, Coupa, SAP, Oracle, and Conga, with medium market concentration and active AI feature competition.
Why this matters for decision-makers: Buyers must prioritize vendors with native ERP/CRM integration and proven AI obligation-tracking, because standalone CLM is losing share at 13.78% CAGR to integrated suites—a shift that will compress margins for non-integrated vendors by 2028.
Contract Management Software Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.480 B
2025
3.770 B
2026
4.090 B
2027
4.430 B
2028
4.800 B
2029
5.210 B
2030
5.640 B
2031
Contract Management Software Market Size (In Billion)
Year
Market Size
2025
3.480 B
2026
3.770 B
2027
4.090 B
2028
4.430 B
2029
4.800 B
2030
5.210 B
2031
5.640 B
What is the Contract Management Software Market?
The contract management software market encompasses platforms that automate the creation, negotiation, execution, tracking, and renewal of commercial agreements. It includes standalone CLM tools and integrated suites embedded in ERP, CRM, and procurement ecosystems, delivered predominantly as cloud subscriptions with AI-enabled analytics for risk, compliance, and obligation management.
Scope: what this report covers and excludes
This report covers global contract management software and related implementation services across all deployment modes, organization sizes, and end-user industries. It includes buy-side, sell-side, and non-commercial contract types. This analysis does not cover e-signature-only tools, general-purpose document management systems, or procurement suites where contract functionality is incidental rather than a dedicated module.
How big is the market for Contract Management Software Market?
The market is estimated at USD 3.77 Billion in 2026, with forecasts ranging from USD 5.64 Billion by 2031 to USD 4.6 Billion by 2033, depending on definitional scope. The divergence between estimates reflects whether services, e-signature adjacencies, and integrated suite revenue are included.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 3.77 B → USD 5.64 B
2026
2031
8.39%
Dedicated contract management software plus services, global
Contract management software, excludes services and e-signature
Alternative published estimate
Our analysis suggests the 8.39% CAGR figure is the most defensible for buyer planning because it aligns with observed cloud adoption rates and the 76.85% cloud share. The higher-CAGR estimates likely use a narrower base that excludes services, inflating growth optics. Buyers should anchor budgets to the mid-range figure while stress-testing vendor roadmaps against the 12–13% upside scenario.
How is the market segmented?
The market segments along deployment, component, contract type, business function, pricing model, integration level, organization size, and end-user industry. Cloud and subscription models dominate, but integrated suites and SME adoption are the fastest-growing pockets, reshaping vendor selection criteria.
Parent Segment
Children
Deployment Mode
Cloud, On-Premise
Component
Software, Services
Contract Type
Buy-Side, Sell-Side, Non-Commercial
Business Function
Procurement & Supply Chain, Legal, Sales, Finance
Pricing Model
Subscription, Perpetual, Usage-Based
Integration Level
Standalone CLM, Integrated Suite
Organization Size
Large Enterprise, SME
End-User Industry
BFSI, IT & Telecom, Healthcare & Life Sciences, Manufacturing, Retail, Government
Which region leads in Contract Management Software Market?
North America leads the global contract management software market with 41.05% of 2025 revenue, supported by mature legal-tech adoption and stringent regulatory oversight. Asia-Pacific is the fastest-growing region at a 9.18% CAGR, driven by ERP suite integration and digital transformation.
What is driving growth — and what is holding it back?
Unified buy-side and sell-side CLM demand across regulated industries adds 1.8% to CAGR, while AI-enabled contract analytics contributes 1.5% and e-signature-native workflows add 1.2%. These drivers outweigh restraints, but legacy data silos and SME cost barriers cap upside in emerging regions.
Factor
Direction
Evidence Strength
Mechanism
Unified buy-side/sell-side CLM demand
Driver
High (+1.8% CAGR)
Closes 8.6% value erosion gap; audit efficiency
AI-enabled contract analytics
Driver
High (+1.5% CAGR)
GenAI highlights indemnity gaps, renewal triggers
Remote/hybrid e-signature-native CLM
Driver
Medium (+1.2% CAGR)
Embeds signing in negotiation flows
Verticalized CLM templates in Europe
Driver
Medium (+0.9% CAGR)
Sector-specific clauses; higher switching costs
ESG-linked supplier compliance
Driver
Medium (+0.8% CAGR)
Procurement mandates drive obligation tracking
Fragmented legacy contract data silos
Restraint
High (-1.4% CAGR)
Impairs AI model accuracy; slows migration
Low digital maturity of Tier-2 suppliers
Restraint
Medium (-0.8% CAGR)
Limits addressable market in South America/Africa
Complex change management in government
Restraint
Medium (-0.6% CAGR)
Extends sales cycles; raises implementation costs
The balance of evidence favors the drivers, but the -1.4% silo restraint is underestimated by most forecasts. Our analysis suggests vendors that solve data migration—not just AI features—will capture disproportionate share. Buyers should demand migration SLAs, not just functionality demos.
Who are the leading vendors?
The market is moderately concentrated, with Icertis, DocuSign, Agiloft, Coupa, SAP, Oracle, and Conga competing on AI capability, integration depth, and vertical templates. Differentiation is shifting from contract storage to obligation intelligence and ecosystem embedding.
Vendor
Primary Strength
Strategic Positioning
Icertis
Enterprise CLM, AI obligation management
Deep buy-side and sell-side coverage
DocuSign
E-signature-native agreement management
1.6M customer base; AI review features
Agiloft
No-code configurability
Flexible workflow; mid-market and enterprise
Coupa
Procurement-integrated CLM
Supply chain spend visibility
SAP / Oracle
ERP-embedded CLM
Suite integration lowers switching costs
Conga
Verticalized templates, CRM/ERP connectors
European life sciences and utilities focus
Competitive moats are built on contract data gravity—the more contracts and integrations a vendor holds, the higher the switching cost. Standalone vendors face margin compression as ERP suites bundle CLM at incremental cost. Our analysis suggests the 13.78% CAGR for integrated suites will force standalone vendors to specialize vertically or risk disintermediation.
What do buyers and operators need to know?
Buyers must prioritize native ERP/CRM integration, AI-driven obligation tracking, and data migration guarantees over feature breadth. Procurement risk is concentrated in implementation services—often 30–40% of total cost—so vendors with certified partner networks and fixed-fee migration options reduce post-signature surprises. Regulatory compliance, particularly GDPR in Europe and sector rules in healthcare and BFSI, requires audit-ready obligation logs and data-residency controls; vendors lacking EU-hosted instances will fail European procurement reviews. Switching costs are high once contract repositories are populated, so buyers should negotiate data portability clauses and exit assistance before signing. SMEs should favor plug-and-play cloud solutions with transparent per-contract pricing, as total cost of ownership can reach EUR 50,000 annually for mid-sized firms.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit to low-double-digit growth market, with the 8.39% CAGR as the most defensible planning anchor. The strongest counter-argument is that AI commoditization could accelerate price erosion faster than forecast, compressing vendor revenue even as contract volumes grow. However, the 92.08% subscription share and 76.85% cloud penetration suggest revenue is recurring and sticky, muting that risk in the near term. Our analysis suggests the real disruption is structural: integrated suites growing at 13.78% will absorb standalone CLM budgets, forcing specialization.
For vendors, the winning strategy is vertical depth plus migration services—not horizontal feature expansion. For buyers, the priority is contract data portability and proven AI accuracy on their own contract corpus before full deployment. Investors should watch the services CAGR of 12.02%, which signals that implementation complexity remains a bottleneck and a margin opportunity.
Actionable strategy:
Vendors should prioritize certified ERP/CRM integration and fixed-fee data migration to capture the 13.78% integrated-suite growth.
Buyers should require AI accuracy benchmarks on their own contracts and negotiate exit-assistance clauses before signing multi-year subscriptions.
Investors should overweight vendors with vertical templates and services attach rates above 30%, as these defend against suite bundling.
What would change our conclusion: a sharp decline in cloud adoption rates, regulatory reversal on cross-border data flows, or evidence that AI reduces implementation services below 10% of total contract value—any of which would shift the growth anchor toward the higher 12–13% estimates.
Table 8: Contract Management Software Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 9: Contract Management Software Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: North America Contract Management Software Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 11: North America Contract Management Software Market Revenue Billion Forecast, by Component 2020 & 2034
Table 12: North America Contract Management Software Market Revenue Billion Forecast, by Contract Type 2020 & 2034
Table 13: North America Contract Management Software Market Revenue Billion Forecast, by Business Function 2020 & 2034
Table 14: North America Contract Management Software Market Revenue Billion Forecast, by Pricing Model 2020 & 2034
Table 15: North America Contract Management Software Market Revenue Billion Forecast, by Integration Level 2020 & 2034
Frequently Asked Questions
1. What is the contract management software market size in 2026?
The global contract management software market is estimated at USD 3.77 Billion in 2026, growing from USD 3.48 Billion in 2025 and projected to reach USD 5.64 Billion by 2031 at an 8.39% CAGR.
2. Which region leads the contract management software market?
North America leads with 41.05% of 2025 revenue, supported by mature legal-tech adoption and regulatory oversight. Asia-Pacific is the fastest-growing region at a 9.18% CAGR through 2031.
3. What is the fastest-growing segment in contract management software?
Integrated suites are the fastest-growing integration segment at a 13.78% CAGR, while legal departments are the fastest-growing business function at 9.48%. SMEs are the fastest-growing organization size at 13.02% CAGR.
4. Who are the leading contract management software vendors?
Leading vendors include Icertis, DocuSign, Agiloft, Coupa, SAP, Oracle, and Conga. Competition centers on AI obligation management, ERP/CRM integration depth, and vertical-specific templates.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the contract management value chain: enterprise software vendors, system integrators, legal operations consultancies, procurement outsourcing firms, and cloud infrastructure providers. Interviewees included VP-level Sourcing leads, Heads of Legal Operations, Technical Directors of CLM implementation, and Commercial Operations Leads at end-user enterprises. This fieldwork captured deployment timelines, AI feature adoption, and migration pain points not visible in public filings.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Leads
35%
Heads of Legal Operations
30%
Technical Directors (CLM Implementation)
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Enterprise Software Vendors
40%
System Integrators & Implementation Partners
30%
Legal Operations Consultancies
20%
Cloud Infrastructure Providers
10%
Secondary Benchmarking & Public Trade Validation
We validated primary findings against official multilateral and regulatory databases—UN Comtrade for cross-border software services trade, Eurostat for European cloud adoption rates (45.2% of enterprises in 2023), US SEC 10-K filings for vendor revenue and segment disclosure, and patent databases for AI contract analytics innovation. Industry association publications and technical standards on e-signature and data privacy (GDPR) informed compliance requirements. No competitor market research firms were used as sources.
Demand Modeling & Market Sizing Triangulation
We triangulated simultaneously via a Top-Down allocation from enterprise software spend and a Bottom-Up model of vendor revenue, contract volumes, and per-contract pricing. This reconciled divergent published estimates (8.39% to 13.6% CAGR) by isolating definitional differences in services and e-signature inclusion, producing a defensible mid-range forecast.
 Contract Management Software Market