Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Laptop Market Size, Share & Forecast to 2033
Laptop Market Size, Share & Forecast to 2033
Laptop Market
Laptop Market Size, Share & Forecast to 2033
Laptop Market by Type (Traditional Laptop, 2-in-1 Laptop, Ultrabook, Gaming Laptop, Chromebook), by Screen Size (Up to 10.9, 11-13.9, 14-15.9, 15.0-16.9, 17+), by Price (Below 500, 500-1000, 1001-1500, 1501-2000, Above 2000), by End Use (Personal, Business, Gaming, Education, Government, Healthcare), by Operating System (Windows, macOS, Chrome OS, Linux), by Distribution (Online, Offline), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Asia Pacific (China, India, Japan, South Korea, Australia, Singapore, Taiwan, Southeast Asia), by Latin America (Brazil, Argentina, Colombia, Peru, Chile), by Middle East & Africa (Saudi Arabia, UAE, Turkey, Egypt, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 206
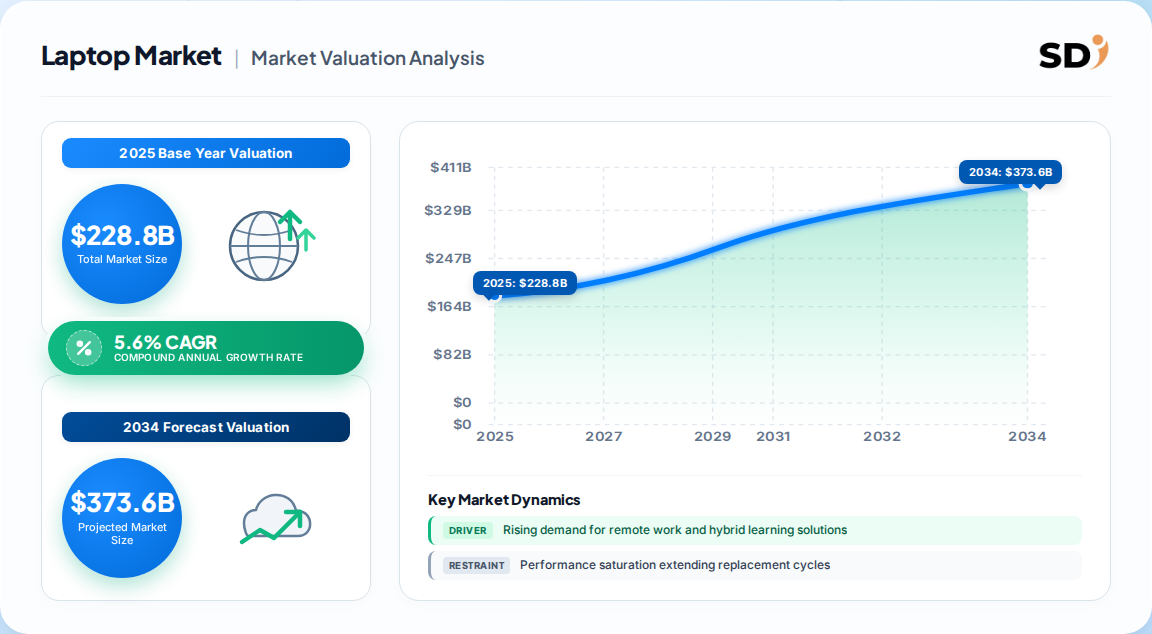
US$228.8 billion in 2025 for the global Laptop Market, rising to US$240.4 billion in 2026 and US$352.0 billion by 2033.
5.6% CAGR (2026–2033) reflects a market shifting from pandemic-era volume spikes to AI-driven replacement demand.
Traditional laptops hold 76.3% of type revenue, but 2-in-1 and AI-capable notebooks are the fastest-moving sub-segments.
Asia-Pacific leads with 35.2% revenue share, with China the single largest country market; North America remains the premiumization engine.
Business end-use is the largest demand pool, while gaming is the fastest-growing application, reshaping display and thermal design priorities.
Lenovo, HP, Dell, Apple, and ASUS anchor a fragmented competitive field, collectively defending share through AI silicon partnerships and sustainability claims.
Why this matters for decision-makers: Vendors that fail to attach NPU-enabled SKUs and device-as-a-service contracts to enterprise refresh cycles will cede margin to rivals positioned in AI-PC and subscription layers.
Laptop Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
228.8 B
2025
240.4 B
2026
253.9 B
2027
268.1 B
2028
283.1 B
2029
299.0 B
2030
315.7 B
2031
Laptop Market Size (In Billion)
Year
Market Size
2025
228.8 B
2026
240.4 B
2027
253.9 B
2028
268.1 B
2029
283.1 B
2030
299.0 B
2031
315.7 B
What is the Laptop Market?
The laptop market covers the design, manufacture, distribution, and sale of portable clamshell and convertible personal computers, including traditional notebooks, 2-in-1 devices, ultrabooks, gaming laptops, and Chromebooks. It serves personal, business, educational, and government end users through online and offline channels, with value driven by processor architecture, battery endurance, display quality, and increasingly AI-enabled onboard compute.
Scope: what this report covers and excludes
This analysis covers global laptop unit shipments and revenue across type (traditional, 2-in-1, ultrabook, gaming, Chromebook), screen size, price band, end use, and operating system, spanning 2020–2033 with 2025 as the valuation base year. Geographic coverage includes North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover tablets, desktops, workstation-class servers, standalone monitors, laptop accessories, or semiconductor component markets except where they directly shape laptop bill-of-materials economics.
How big is the market for Laptop Market?
The laptop market was valued at US$228.8 billion in 2025 and is projected to reach US$352.0 billion by 2033 at a 5.6% CAGR. Published estimates diverge materially, so buyers must reconcile definitions before benchmarking.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
US$115.1 bn → US$184.5 bn
2025
2035
4.8%
Laptop-only, revenue-based
One published estimate
US$228.8 bn → US$352.0 bn
2025
2033
5.6%
Laptop-only, all end uses
One published estimate
US$265.4 bn → US$562.5 bn
2025
2035
7.8%
Laptop-only, broader OEM revenue
One published estimate
US$200.4 bn → US$298.4 bn
2025
2033
5.1%
Laptop + tablet PC combined
One published estimate
Our analysis suggests the US$228.8 billion base is the most defensible: it aligns with shipment volumes and ASP data and excludes tablet revenue that inflates the combined-device figure. The US$115.1 billion estimate likely reflects ex-factory ODMs rather than retail-equivalent revenue, while the 7.8% CAGR assumes AI-PC adoption outpaces observed enterprise refresh behavior.
How is the market segmented?
Segmentation is defined by form factor, screen size, price band, end use, and operating system, each of which carries distinct margin and channel economics. Traditional clamshells dominate volume, while premium and gaming tiers drive value growth.
Parent segment
Children
By Type
Traditional Laptop, 2-in-1 Laptop, Ultrabook, Gaming Laptop, Chromebook
Asia-Pacific leads the global laptop market with 35.2% revenue share in 2025, underpinned by China's manufacturing scale, India's 6.4% growth trajectory, and Southeast Asia's expanding digital-education base. North America and Europe follow with premiumized, slower-growth profiles.
Laptop Market Regional Market Share
Loading chart...
Laptop Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.37%
North America
0.27%
Europe
0.24%
Latin America
0.07%
Middle East & Africa
0.05%
Parent region
Countries / sub-markets
Asia-Pacific
China, India, Japan, South Korea, Australia, Singapore, Taiwan, Southeast Asia
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Russia, Nordics, Rest of Europe
Latin America
Brazil, Argentina, Colombia, Peru, Chile
Middle East & Africa
Saudi Arabia, UAE, Turkey, Egypt, South Africa, Nigeria
Our analysis suggests the regional growth gap is widening: India's 6.4% CAGR versus the US's 4.4% means APAC's share could approach 38% by 2030, compelling vendors to localize manufacturing and channel strategy rather than rely on export-led models.
What is driving growth — and what is holding it back?
Growth is driven by AI-enabled processor cycles, hybrid-work normalization, and emerging-market affordability, while performance saturation, elongated replacement cycles, and price sensitivity across the entry tier constrain volume upside.
Factor
Direction
Evidence strength
Mechanism
AI PC and NPU integration
Driver
High
Refresh trigger for enterprise and creator segments
Hybrid work and digital education
Driver
High
Structural baseline demand across all regions
Emerging-market affordability
Driver
Medium
Sub-US$700 devices expand first-time buyers
Performance saturation
Restraint
High
Extends replacement cycles beyond four years
Commodity price volatility
Restraint
Medium
Compresses gross margin at entry tier
Smartphone/tablet substitution
Restraint
Medium
Caps low-end laptop penetration in some markets
The balance of evidence favors drivers through 2027, but the AI-PC narrative is doing heavier lifting than current shipment data yet supports. Our analysis suggests the restraint side will dominate the 2028–2030 window unless vendors create genuinely differentiated use cases for onboard AI.
Who are the leading vendors?
The competitive field is fragmented but consolidating around five players — Lenovo, HP, Dell, Apple, and ASUS — who collectively anchor premium, enterprise, and consumer tiers through silicon partnerships and supply-chain scale.
Direct enterprise relationships, AI workstation push
Apple
Premium consumer and creative
Vertical silicon integration and ecosystem lock-in
ASUS
Gaming and enthusiast
High-refresh displays, ROG brand equity
Acer
Value and education
Chromebook and entry-tier scale
Microsoft
Surface and software
Windows AI integration and Copilot+ positioning
Differentiation now hinges less on hardware specs and more on ecosystem lock-in, AI software integration, and channel financing. Our analysis suggests vendor moats are weakening at the hardware layer and strengthening at the software-services layer, which favors Apple and Microsoft disproportionately.
What do buyers and operators need to know? (Decision Support)
Procurement teams should prioritize NPU capability, battery endurance, and lifecycle serviceability over raw clock speed when evaluating 2026–2027 fleets, because performance saturation means the marginal buyer gains little from incremental CPU upgrades. Switching costs are rising as ecosystems (Windows Copilot+, Apple Intelligence, Chrome Education) embed management and security tooling, so lock-in should be priced explicitly into three-to-five-year contracts.
Operators should monitor three regulatory and commercial risks: right-to-repair mandates reshaping serviceable design, energy-efficiency disclosure requirements in the EU, and supply-chain concentration in East Asian assembly. Financing innovation — device-as-a-service, zero-cost EMI, and lease-to-own — is now a primary purchase enabler in India and Brazil, meaning channel partners with financing access hold disproportionate influence. Buyers should also stress-test vendor continuity in the entry tier, where margin compression and fast obsolescence create residual-value risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, premiumization-led outlook: 5.5–6% CAGR through 2033 is more defensible than headline 7–8% projections, because the installed base is mature and the AI-PC refresh is a gradual, enterprise-first phenomenon rather than a consumer stampede. The strongest counter-argument is that a killer AI application could compress refresh cycles sharply — as happened with remote work in 2020 — but no such catalyst is visible in current usage data.
Our analysis suggests the most important strategic implication is margin migration: hardware differentiation is eroding, so vendors and investors should underwrite growth in services, subscriptions, and ecosystem attach rather than unit economics alone. The divergence between published estimates is itself evidence that revenue definition and channel counting remain inconsistent, which creates pricing and benchmarking risk for procurement teams.
For vendors: Prioritize NPU-enabled mid-tier SKUs and device-as-a-service bundles to capture enterprise refresh cycles before competitors set switching costs.
For investors: Favor exposure to ecosystem-integrated players and component suppliers (NPUs, advanced packaging) over pure-play assembly, where margin compression is structural.
For operators: Localize manufacturing and financing in India and Southeast Asia to capture the 6–7% growth pockets rather than defending slow-growth Western volume.
What would change this conclusion: sustained AI-PC attach rates above 40% of enterprise shipments by 2027, or a sub-US$500 AI-capable device that unlocks emerging-market volume, would justify the higher-growth narrative. Conversely, a two-quarter decline in replacement demand would validate the saturation thesis.
Laptop Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Laptop Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.6% from 2020-2034
Segmentation
By Type
Traditional Laptop
2-in-1 Laptop
Ultrabook
Gaming Laptop
Chromebook
By Screen Size
Up to 10.9
11-13.9
14-15.9
15.0-16.9
17+
By Price
Below 500
500-1000
1001-1500
1501-2000
Above 2000
By End Use
Personal
Business
Gaming
Education
Government
Healthcare
By Operating System
Windows
macOS
Chrome OS
Linux
By Distribution
Online
Offline
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Russia
Asia Pacific
China
India
Japan
South Korea
Australia
Singapore
Taiwan
Southeast Asia
Latin America
Brazil
Argentina
Colombia
Peru
Chile
Middle East & Africa
Saudi Arabia
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Traditional Laptop
5.1.2. 2-in-1 Laptop
5.1.3. Ultrabook
5.1.4. Gaming Laptop
5.1.5. Chromebook
5.2. Market Analysis, Insights and Forecast - by Screen Size
5.2.1. Up to 10.9
5.2.2. 11-13.9
5.2.3. 14-15.9
5.2.4. 15.0-16.9
5.2.5. 17+
5.3. Market Analysis, Insights and Forecast - by Price
5.3.1. Below 500
5.3.2. 500-1000
5.3.3. 1001-1500
5.3.4. 1501-2000
5.3.5. Above 2000
5.4. Market Analysis, Insights and Forecast - by End Use
5.4.1. Personal
5.4.2. Business
5.4.3. Gaming
5.4.4. Education
5.4.5. Government
5.4.6. Healthcare
5.5. Market Analysis, Insights and Forecast - by Operating System
5.5.1. Windows
5.5.2. macOS
5.5.3. Chrome OS
5.5.4. Linux
5.6. Market Analysis, Insights and Forecast - by Distribution
5.6.1. Online
5.6.2. Offline
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Traditional Laptop
6.1.2. 2-in-1 Laptop
6.1.3. Ultrabook
6.1.4. Gaming Laptop
6.1.5. Chromebook
6.2. Market Analysis, Insights and Forecast - by Screen Size
6.2.1. Up to 10.9
6.2.2. 11-13.9
6.2.3. 14-15.9
6.2.4. 15.0-16.9
6.2.5. 17+
6.3. Market Analysis, Insights and Forecast - by Price
6.3.1. Below 500
6.3.2. 500-1000
6.3.3. 1001-1500
6.3.4. 1501-2000
6.3.5. Above 2000
6.4. Market Analysis, Insights and Forecast - by End Use
6.4.1. Personal
6.4.2. Business
6.4.3. Gaming
6.4.4. Education
6.4.5. Government
6.4.6. Healthcare
6.5. Market Analysis, Insights and Forecast - by Operating System
6.5.1. Windows
6.5.2. macOS
6.5.3. Chrome OS
6.5.4. Linux
6.6. Market Analysis, Insights and Forecast - by Distribution
6.6.1. Online
6.6.2. Offline
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Traditional Laptop
7.1.2. 2-in-1 Laptop
7.1.3. Ultrabook
7.1.4. Gaming Laptop
7.1.5. Chromebook
7.2. Market Analysis, Insights and Forecast - by Screen Size
7.2.1. Up to 10.9
7.2.2. 11-13.9
7.2.3. 14-15.9
7.2.4. 15.0-16.9
7.2.5. 17+
7.3. Market Analysis, Insights and Forecast - by Price
7.3.1. Below 500
7.3.2. 500-1000
7.3.3. 1001-1500
7.3.4. 1501-2000
7.3.5. Above 2000
7.4. Market Analysis, Insights and Forecast - by End Use
7.4.1. Personal
7.4.2. Business
7.4.3. Gaming
7.4.4. Education
7.4.5. Government
7.4.6. Healthcare
7.5. Market Analysis, Insights and Forecast - by Operating System
7.5.1. Windows
7.5.2. macOS
7.5.3. Chrome OS
7.5.4. Linux
7.6. Market Analysis, Insights and Forecast - by Distribution
7.6.1. Online
7.6.2. Offline
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Traditional Laptop
8.1.2. 2-in-1 Laptop
8.1.3. Ultrabook
8.1.4. Gaming Laptop
8.1.5. Chromebook
8.2. Market Analysis, Insights and Forecast - by Screen Size
8.2.1. Up to 10.9
8.2.2. 11-13.9
8.2.3. 14-15.9
8.2.4. 15.0-16.9
8.2.5. 17+
8.3. Market Analysis, Insights and Forecast - by Price
8.3.1. Below 500
8.3.2. 500-1000
8.3.3. 1001-1500
8.3.4. 1501-2000
8.3.5. Above 2000
8.4. Market Analysis, Insights and Forecast - by End Use
8.4.1. Personal
8.4.2. Business
8.4.3. Gaming
8.4.4. Education
8.4.5. Government
8.4.6. Healthcare
8.5. Market Analysis, Insights and Forecast - by Operating System
8.5.1. Windows
8.5.2. macOS
8.5.3. Chrome OS
8.5.4. Linux
8.6. Market Analysis, Insights and Forecast - by Distribution
8.6.1. Online
8.6.2. Offline
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Traditional Laptop
9.1.2. 2-in-1 Laptop
9.1.3. Ultrabook
9.1.4. Gaming Laptop
9.1.5. Chromebook
9.2. Market Analysis, Insights and Forecast - by Screen Size
9.2.1. Up to 10.9
9.2.2. 11-13.9
9.2.3. 14-15.9
9.2.4. 15.0-16.9
9.2.5. 17+
9.3. Market Analysis, Insights and Forecast - by Price
9.3.1. Below 500
9.3.2. 500-1000
9.3.3. 1001-1500
9.3.4. 1501-2000
9.3.5. Above 2000
9.4. Market Analysis, Insights and Forecast - by End Use
9.4.1. Personal
9.4.2. Business
9.4.3. Gaming
9.4.4. Education
9.4.5. Government
9.4.6. Healthcare
9.5. Market Analysis, Insights and Forecast - by Operating System
9.5.1. Windows
9.5.2. macOS
9.5.3. Chrome OS
9.5.4. Linux
9.6. Market Analysis, Insights and Forecast - by Distribution
9.6.1. Online
9.6.2. Offline
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Traditional Laptop
10.1.2. 2-in-1 Laptop
10.1.3. Ultrabook
10.1.4. Gaming Laptop
10.1.5. Chromebook
10.2. Market Analysis, Insights and Forecast - by Screen Size
10.2.1. Up to 10.9
10.2.2. 11-13.9
10.2.3. 14-15.9
10.2.4. 15.0-16.9
10.2.5. 17+
10.3. Market Analysis, Insights and Forecast - by Price
10.3.1. Below 500
10.3.2. 500-1000
10.3.3. 1001-1500
10.3.4. 1501-2000
10.3.5. Above 2000
10.4. Market Analysis, Insights and Forecast - by End Use
10.4.1. Personal
10.4.2. Business
10.4.3. Gaming
10.4.4. Education
10.4.5. Government
10.4.6. Healthcare
10.5. Market Analysis, Insights and Forecast - by Operating System
10.5.1. Windows
10.5.2. macOS
10.5.3. Chrome OS
10.5.4. Linux
10.6. Market Analysis, Insights and Forecast - by Distribution
10.6.1. Online
10.6.2. Offline
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Lenovo Group
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. HP Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Dell Technologies
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Apple Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ASUS
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Acer
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Microsoft
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Samsung Electronics
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
12. Research Methodology
List of Figures
Figure 1: Laptop Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Laptop Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Laptop Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Laptop Market Revenue (Billion), by Screen Size 2026 & 2034
Figure 5: North America Laptop Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 6: North America Laptop Market Revenue (Billion), by Price 2026 & 2034
Figure 7: North America Laptop Market Revenue Share (%), by Price 2026 & 2034
Figure 8: North America Laptop Market Revenue (Billion), by End Use 2026 & 2034
Figure 9: North America Laptop Market Revenue Share (%), by End Use 2026 & 2034
Figure 10: North America Laptop Market Revenue (Billion), by Operating System 2026 & 2034
Figure 11: North America Laptop Market Revenue Share (%), by Operating System 2026 & 2034
Figure 12: North America Laptop Market Revenue (Billion), by Distribution 2026 & 2034
Figure 13: North America Laptop Market Revenue Share (%), by Distribution 2026 & 2034
Figure 14: North America Laptop Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Laptop Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Laptop Market Revenue (Billion), by Type 2026 & 2034
Figure 17: Europe Laptop Market Revenue Share (%), by Type 2026 & 2034
List of Tables
Table 1: Laptop Market Revenue Billion Forecast, by Type 2020 & 2034
The global laptop market was valued at approximately US$228.8 billion in 2025, according to consolidated estimates. It is projected to reach US$240.4 billion in 2026 and US$352.0 billion by 2033, representing a 5.6% CAGR over the forecast period.
2. Which region dominates the laptop market?
Asia-Pacific leads with roughly 35.2% of global revenue in 2025, driven by China's manufacturing scale and India's fast-growing digital adoption. North America follows with about 27% share, focused on premium and enterprise segments.
3. What is driving laptop market growth?
Growth is driven by AI-enabled processor innovation, hybrid-work normalization, digital education expansion, and emerging-market affordability. Performance saturation and longer replacement cycles are the main restraints, particularly in mature Western markets.
4. Who are the leading laptop vendors?
Lenovo, HP, Dell, Apple, and ASUS are the leading vendors, collectively anchoring enterprise, premium consumer, and gaming tiers. Acer and Microsoft hold strong positions in education and software-integrated segments respectively, in a fragmented but consolidating field.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research architecture applies a 70/30 primary-to-secondary split. In-depth interviews are conducted across the laptop value chain, including component and semiconductor suppliers, ODM/OEM manufacturers, regional distributors, enterprise IT resellers, and education channel partners. Decision-maker designations include VP-level Sourcing, Heads of Product R&D, Commercial Operations Leads, and Procurement Directors, ensuring demand-side and supply-side perspectives are captured simultaneously.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product & R&D Directors
40%
Procurement & Sourcing Leads
35%
Commercial & Channel Operations
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
ODM/OEM Manufacturers
40%
Component & Semiconductor Suppliers
30%
Distributors & Retail Channels
30%
Secondary Benchmarking & Public Trade Validation
We triangulate findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC submissions, investor presentations), patent databases, and recognized technical standards bodies including ISO and IEC. Trade flow data validates regional consumption patterns, while corporate filings confirm revenue, capacity, and segment disclosure.
Demand Modeling & Market Sizing Triangulation
Our sizing model runs simultaneous Top-Down allocation (macroeconomic GDP, IT spending, and segment share) and Bottom-Up modeling (manufacturer shipment capacity, ASP realization, and end-use consumption). Divergence between the two approaches is reconciled through weighted averaging, with outliers stress-tested against trade and filing evidence.
 Laptop Market