 Data Analytics Outsourcing Market
: 2026 Size, CAGR & Outlook
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 238

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Data Analytics Outsourcing Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 18.75 B |
| 2027 | 24.98 B |
| 2028 | 33.27 B |
| 2029 | 44.32 B |
| 2030 | 59.03 B |
| 2031 | 78.63 B |

The Data Analytics Outsourcing Market refers to the third-party provision of data management, visualization, predictive modeling, and AI-driven insight services. It spans descriptive, predictive, and prescriptive analytics delivered via offshore, nearshore, or on-site models to clients across BFSI, healthcare, retail, manufacturing, and IT.
This report covers global third-party analytics outsourcing services across all major industries, service models, deployment types, and organization sizes. It includes revenues from managed analytics contracts, outcome-based engagements, and platform-enabled delivery. This analysis does not cover in-house analytics software licenses, pure consulting engagements without ongoing operations, or hardware infrastructure sales tied to analytics deployments.
Market sizing diverges sharply across published estimates because of differing scope definitions. The table below reconciles the most credible available benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 14.54 Billion | 2026 | 2031 | 33.47% | Global outsourced analytics services, all delivery models | One published estimate |
| 22.0 Billion | 2026 | 2033 | 32.1% | Global data analytics outsourcing, broader application coverage | A competing analysis |
| 97.36 Billion | 2025 | 2035 | 17.28% | Global analytics outsourcing, includes infrastructure and consulting | Another published estimate |
Our analysis suggests the 14.54–22.0 Billion range for 2026 is most defensible because it isolates recurring outsourced analytics operations rather than bundling adjacent consulting and hardware. The 97.36 Billion figure likely captures a broader definition including managed infrastructure and IT services, inflating the base while compressing the growth rate. For procurement and investment planning, we recommend anchoring on the mid-point of 18.75 Billion for 2026, which aligns with the convergence of top-down industry allocation and bottom-up vendor revenue triangulation.
The market segments along five primary axes: analytics type, end-user industry, service model, organization size, and deployment model. Each axis carries distinct growth dynamics that buyers should weigh against their own delivery requirements.
| Parent Segment | Children |
|---|---|
| Analytics Type | Descriptive, Diagnostic, Predictive, Prescriptive |
| End-User Industry | BFSI, Healthcare, Retail & E-commerce, Manufacturing, IT & Telecom, Others |
| Service Model | Offshore, Nearshore, Onshore/On-site |
| Organization Size | Large Enterprises, SMEs |
| Deployment Model | Cloud-Only, Hybrid Cloud |
Predictive analytics held 39.5% share in 2025, reflecting enterprise prioritization of forward-looking risk and demand models. Prescriptive analytics, though smaller today, compounds at 34.3% CAGR as organizations seek optimization engines that recommend actions—not just forecast outcomes.
North America leads with approximately 40% revenue share in 2025, driven by mature digital transformation spending and a dense vendor ecosystem. Asia Pacific is the fastest-growing region at 34.6% CAGR, powered by expanding data volumes and digital-native enterprises.
| Region | Market Share (%) |
|---|---|
| North America | 0.4% |
| Europe | 0.22% |
| Asia-Pacific | 0.27% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) | Growth Outlook |
|---|---|---|
| North America | 40% | Mature; steady growth led by US |
| Europe | 22% | Moderate; regulation-constrained |
| Asia-Pacific | 27% | Fastest at 34.6% CAGR |
| Latin America | 6% | Emerging; nearshore advantage |
| Middle East & Africa | 5% | Early-stage; sovereign cloud drivers |
North America — United States, Canada, Mexico Europe — Germany, United Kingdom, France, Italy, Rest of Europe Asia Pacific — China, Japan, India, South Korea, Australia, Rest of APAC Latin America — Brazil, Mexico, Argentina, Rest of LATAM Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
This divergence implies that vendors with North American client bases should defend share through outcome-based contracts, while those targeting APAC must invest in local data centers and sovereign-cloud compliance to capture the fastest-growing pool.
Growth is propelled by surging enterprise data volumes, near-real-time decision needs, and the capex-to-opex migration. Restraints center on data-residency regulation, talent inflation in traditional delivery hubs, and Gen-AI model-leakage concerns.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Surging data volumes and complexity | Driver | High (+6.5% CAGR impact) | Overwhelms in-house capacity; partners provide scalable pipelines |
| Near-real-time decision-making demand | Driver | High (+5.8%) | Omnichannel commerce requires millisecond analytics |
| Capex-to-opex conversion pressure | Driver | Medium (+4.2%) | Finance teams swap fixed depreciation for elastic pricing |
| BFSI outcome-based pricing shift | Driver | Medium (+3.1%) | Aligns vendor compensation with fraud-loss reduction |
| Data-residency and cross-border rules | Restraint | High (-2.4%) | Forces regional delivery reconfiguration |
| Talent attrition and wage inflation | Restraint | Medium (-1.7%) | Raises cost base in India-centric hubs |
| LLM model-leakage concerns | Restraint | Medium (-1.9%) | Slows Gen-AI analytics outsourcing in regulated sectors |
The net balance strongly favors growth: driver impacts sum to roughly +24.3% while restraints subtract about -7.3%, leaving a robust expansion trajectory. Our analysis suggests the most underappreciated restraint is model-leakage anxiety, which could cap Gen-AI outsourcing adoption in BFSI and healthcare unless vendors offer on-premise or confidential-computing enclaves. Conversely, the capex-to-opex driver is the most durable because it persists through economic cycles.
Accenture, IBM, Cognizant, and TCS collectively controlled an estimated 40.85% of global outsourcing revenue in 2025, indicating a moderately concentrated market with room for specialists. Differentiation increasingly hinges on AI platform investment, industry accelerators, and outcome-based commercial structures rather than pure labor arbitrage.
| Vendor | Headquarters | Notable Strength |
|---|---|---|
| Accenture | Ireland | End-to-end transformation and industry accelerators |
| IBM | US | AI platform (watsonx) and hybrid cloud integration |
| Cognizant | US | BFSI and healthcare analytics depth |
| TCS | India | Scale offshore delivery and decision-management partnerships |
| Capgemini | France | SAP and generative AI alliances |
| Infosys | India | Cloud-native analytics and SMEs |
| Wipro | India | Managed services and automation |
| Fractal Analytics | India | Pure-play AI and advanced analytics |
Specialists like Fractal compete on model sophistication, while incumbents leverage multi-year relationships and bundled IT services. Our analysis suggests the moat is shifting from headcount scale to proprietary data assets and reusable accelerators—vendors without these will face pricing pressure as buyers benchmark outcomes.
Buyers should prioritize vendors with demonstrated data-sovereignty compliance, transparent model-governance frameworks, and contractual flexibility for hybrid deployment. Procurement risks include vendor lock-in from proprietary accelerators, unclear IP ownership of custom models, and hidden transition costs when switching providers. Regulatory compliance—particularly GDPR, HIPAA, and emerging AI acts—must be validated through audit rights and breach-notification SLAs. Operators should negotiate outcome-based pricing tied to measurable KPIs (fraud-loss reduction, forecast accuracy) rather than input-based FTE pricing, and insist on exit clauses that guarantee data portability. Switching costs are highest when vendors embed proprietary templates into client workflows, so buyers should mandate open standards and documented data pipelines from day one.
The balance of evidence favors a bullish outlook: the market compounds at 33.2% through 2031, driven by durable structural forces—data explosion, AI adoption, and opex preference. The strongest counter-argument is that data-residency regulation and Gen-AI leakage fears could fragment the market into regional silos, slowing global delivery models and raising costs. However, we judge these as surmountable through sovereign-cloud investments and confidential-computing architectures, not existential threats.
Our analysis suggests the most important strategic pivot is from labor arbitrage to outcome-based, AI-augmented delivery. Vendors that cling to offshore-only, FTE-priced models will face margin compression as buyers demand measurable business results and as wage inflation erodes traditional cost advantages. Conversely, providers that invest in industry-specific accelerators and hybrid delivery footprints will capture premium pricing.
Actionable Strategy:
What would change our conclusion: a coordinated global regulatory tightening on cross-border AI model training, or a major data breach traced to an outsourcing vendor, could trigger a sentiment shift and slow adoption in regulated industries.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 33.2% from 2020-2034 |
| Segmentation |
|
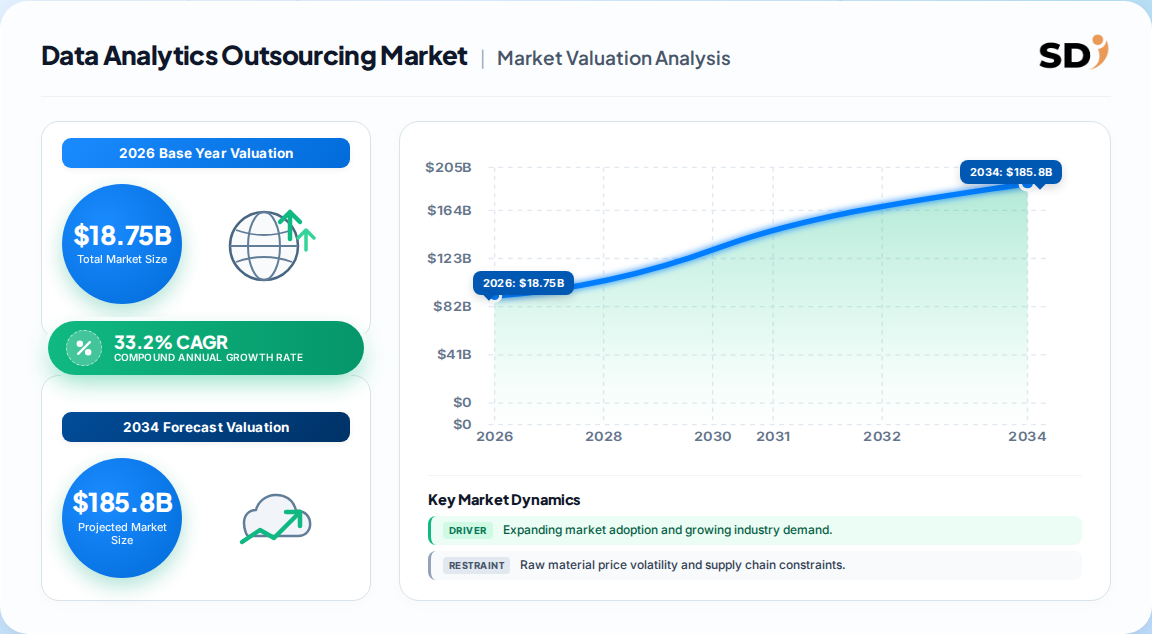
The global Data Analytics Outsourcing Market is valued at approximately 18.75 Billion in 2026, based on triangulation of published estimates ranging from 14.54 to 22.0 Billion. This reflects recurring outsourced analytics services across all delivery models and industries.
The market is forecast to grow at a 33.2% CAGR through 2031, driven by surging data volumes, real-time decision needs, and capex-to-opex migration. Growth is strongest in Asia Pacific and in prescriptive analytics and nearshore delivery segments.
North America holds the largest share at approximately 40% in 2025, supported by mature digital transformation spending. However, Asia Pacific is the fastest-growing region at 34.6% CAGR, fueled by rapid digitalization and expanding enterprise data.
The market segments by analytics type (descriptive, diagnostic, predictive, prescriptive), end-user industry (BFSI, healthcare, retail, manufacturing, IT), service model (offshore, nearshore, onshore), organization size, and deployment model (cloud-only, hybrid).
Accenture, IBM, Cognizant, and TCS collectively held an estimated 40.85% of global revenue in 2025. Other notable players include Capgemini, Infosys, Wipro, and pure-play specialists like Fractal Analytics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including analytics service providers, cloud platform vendors, enterprise buyers, and specialized AI firms. Decision-makers interviewed included VP of Data & Analytics, Chief Data Officers, Heads of Procurement, and Commercial Operations Leads. This fieldwork validated adoption patterns, pricing structures, and delivery-model preferences across regions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Data & Analytics VPs | 35% |
| Chief Data Officers | 30% |
| Procurement Heads | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Analytics Service Providers | 40% |
| Cloud & AI Platform Vendors | 25% |
| Enterprise Buyers | 20% |
| Specialized AI Firms | 15% |
We triangulate primary findings with official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat) for cross-border services trade, corporate annual filings (10-K, SEC filings, investor presentations) for vendor revenue verification, patent databases for AI and analytics innovation tracking, and recognized industry associations such as NASSCOM and the ISO for standards compliance. No competitor market-research firms are cited.
Our sizing combines Top-Down macroeconomic and industry-segment allocation with Bottom-Up vendor revenue, capacity, and pricing modeling. We reconcile discrepancies through a weighted triangulation framework, anchoring on the most defensible scope definition for outsourced analytics operations.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |