 IoT Data Management Market
: Size, CAGR & Forecast to 2031
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 257

Srinwanti Kar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 IoT Data Management Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 79.31 B |
| 2026 | 92.39 B |
| 2027 | 107.6 B |
| 2028 | 125.4 B |
| 2029 | 146.1 B |
| 2030 | 170.1 B |
| 2031 | 197.9 B |

The IoT Data Management Market encompasses software and services that ingest, store, process, govern, and analyze telemetry generated by connected devices. It spans integration, analytics, stream processing, security, and metadata management, delivered via cloud, on-premise, or hybrid models across industrial, healthcare, utility, and smart-city applications.
This analysis covers global IoT data management solutions and services across eight end-user industries and five application domains. It excludes adjacent markets such as IoT connectivity platforms, device hardware, network infrastructure, and standalone data-center hardware. This analysis does not cover consumer IoT devices or general-purpose enterprise data warehouses unless purpose-built for telemetry workloads.
The global IoT Data Management Market was estimated between USD 75.20 billion and USD 92.39 billion for 2025–2026, with forecasts diverging on horizon and scope definition. The table below compares leading estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 92.39 Bn | 2026 | 2031 | 16.49% | Full IoT data management solutions & services | One published estimate |
| USD 83.2 Bn | 2024 | 2030 | 12.0% | Component, deployment, organization size | A competing analysis |
| USD 75.20 Bn | 2025 | 2035 | 15.6% | Solution, deployment, data type, end-user | A competing analysis |
| USD 86.90 Bn | 2026 | 2035 | 15.6% | Global full-scope forecast | A competing analysis |
Which figure is most defensible? The USD 92.39 billion estimate for 2026 aligns with the 16.49% CAGR midpoint and the 2025 base of USD 79.31 billion. Our analysis suggests the 12.0% CAGR understates growth because it underweights stream-processing and hybrid deployment expansion. The 2035 horizon figures imply a larger terminal market but use a lower CAGR, indicating scope differences rather than genuine disagreement.
The market segments by solution, deployment model, data type, end-user industry, and application. Analytics and time-series workloads dominate current spend, while unstructured data and stream processing represent the fastest-growing pockets.
| Parent Segment | Children |
|---|---|
| By Solution | Integration, Migration, Analytics, Stream Processing, Storage, Security |
| By Deployment Model | Cloud, On-Premise, Hybrid |
| By Data Type | Structured, Semi-Structured, Unstructured, Time-Series |
| By End-User Industry | Agriculture, BFSI, Manufacturing & Industrial, Healthcare & Life Sciences, Government & Smart Cities, Energy & Utilities, Retail, Automotive & Transportation |
| By Application | Predictive Maintenance, Smart Metering, Smart Grid Analytics, Asset Tracking & Fleet Management, Remote Patient Monitoring |
Analytics at 36.42% of 2025 revenue confirms buyers are shifting budget from capture to insight. Time-series telemetry at 48.20% of processing demand reflects legacy SCADA migration and asset-health monitoring. Our analysis indicates that vendors offering unified governance across time-series and unstructured data will capture the fastest-growing hybrid workloads through 2031.
North America leads the global IoT Data Management Market with 40.55% revenue share in 2025, driven by hyperscaler proximity, industrial retrofit budgets, and mature regulatory frameworks. Asia Pacific is the fastest-growing region at 17.56% CAGR, powered by manufacturing telemetry and utility metering scale-up in China, India, and Japan.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.26% |
| Asia-Pacific | 0.27% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
Europe ranks second with roughly 26% share, propelled less by volume than by regulation: GDPR, the EU Data Act, and NIS2 make governed architecture a condition of market access. Our analysis suggests Europe's compliance-driven demand creates a defensible moat for vendors with native lineage and residency controls.
Connected-device proliferation adds approximately 4.2% to CAGR, cloud-native analytics maturity adds 3.4%, and regulatory governance pressure adds 3.0%. Fragmented standards subtract roughly 2.5%, and high total cost of ownership subtracts 2.0%.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Connected-device proliferation | Driver | High | Terabytes of telemetry overwhelm legacy stores |
| Cloud-native data lakes & analytics | Driver | High | Auto-scaling, built-in ML pipelines, lower ETL cost |
| Regulatory governance & security | Driver | High | EU Data Act, GDPR, NIS2 mandate lineage and access |
| Real-time edge analytics | Driver | Medium | Sub-second quality checks and grid balancing |
| 5G network slicing | Driver | Medium | Prioritized low-latency IoT data streams |
| Fragmented standards & interoperability | Restraint | High | Custom middleware inflates maintenance cost |
| High total cost of ownership | Restraint | Medium | Integration and security expenses triple license fees |
| Data-sovereignty regulations | Restraint | Medium | Cross-border flow restrictions complicate unified architecture |
The balance of evidence favors growth. Drivers collectively add roughly 16.4% to CAGR while restraints subtract about 6.8%, implying net acceleration above baseline. However, our analysis suggests the restraint impact is understated for SMEs, where TCO and skill shortages delay deployment by 6–12 months. Managed, pay-as-you-grow services are the natural hedge.
The competitive landscape is medium-concentrated, with hyperscalers and industrial-software incumbents competing on unified ingestion, governance, and AI-ready analytics. No single vendor exceeds 15% share.
| Vendor | Primary Strength | Differentiation | Strategic Moat |
|---|---|---|---|
| Microsoft | Azure IoT, Fabric analytics | Cloud-native integration | Enterprise footprint & governance |
| AWS | IoT Core, Timestream | Scalable ingestion | Hyperscaler ecosystem |
| Google Cloud | BigQuery, edge TPU | AI/ML pipeline depth | Data analytics leadership |
| IBM | Maximo, Watson IoT | Industrial asset management | Enterprise trust & services |
| Cisco | Splunk acquisition (USD 28 Bn) | Unified observability | Security-telemetry convergence |
| Oracle | Cloud infrastructure, database | Time-series database | Enterprise database lock-in |
| SAP | Leonardo, BTP | ERP-integrated telemetry | Manufacturing process depth |
| PTC | ThingWorx | Industrial AR/IoT | Brownfield integration |
Cisco's USD 28 billion Splunk acquisition sharpens differentiation around unified ingestion, governance, and AI-ready analytics. Our analysis suggests vendors without native governance will face pricing pressure as buyers consolidate from three to two platform vendors per enterprise.
Buyers should prioritize governance-native platforms that enforce lineage, retention, and residency policy in the same control plane as analytics. Procurement risks include hidden cloud egress charges, integration cost overruns, and skill shortages in edge orchestration. Switching costs are high once telemetry pipelines are embedded in operational workflows.
Regulatory compliance is non-negotiable in Europe and increasingly in North America. The EU Data Act's September 2025 applicability and September 2026 design requirements convert governed pipelines from a nice-to-have into a compliance obligation. Operators should demand machine-readable export, per-tenant access control, and demonstrable lineage across the full retention window.
Mission-critical selection criteria include time-series write throughput, stream-processing latency, hybrid deployment flexibility, and vendor interoperability with legacy SCADA and MES systems. Our analysis suggests buyers who lock into proprietary data models face 20–30% higher migration costs at renewal. Prefer vendors with open metadata standards and documented APIs.
The balance of evidence favors a 16–17% CAGR trajectory through 2031, anchored by regulatory mandates, industrial downtime economics, and AI-driven analytics demand. The strongest counter-argument is that fragmented standards and TCO pressures could cap growth at 12–13%, particularly if SME adoption stalls. We judge this unlikely because managed services and modular platforms are actively dissolving the TCO barrier.
Our analysis suggests the most important strategic shift is the convergence of governance and analytics into a single product. Vendors treating them as separate modules will lose deals to platforms that enforce policy at ingestion. The EU Data Act accelerates this: compliance is an architecture decision, not a documentation exercise. Buyers should weight governance depth equally with analytics capability in RFPs.
Actionable Strategy:
What evidence would change our conclusion? A sustained decline in connected-device shipments below 8% annual growth, or delayed EU Data Act enforcement beyond 2027, would materially lower the CAGR toward the 12% low case. Conversely, accelerated generative-AI training-corpus demand could push growth above 18%.
While this overview covers segment-level dynamics, precise sub-segment forecasting, vendor market-share modeling, and country-level regulatory impact analysis require the full report's proprietary datasets and scenario models.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.49% from 2020-2034 |
| Segmentation |
|
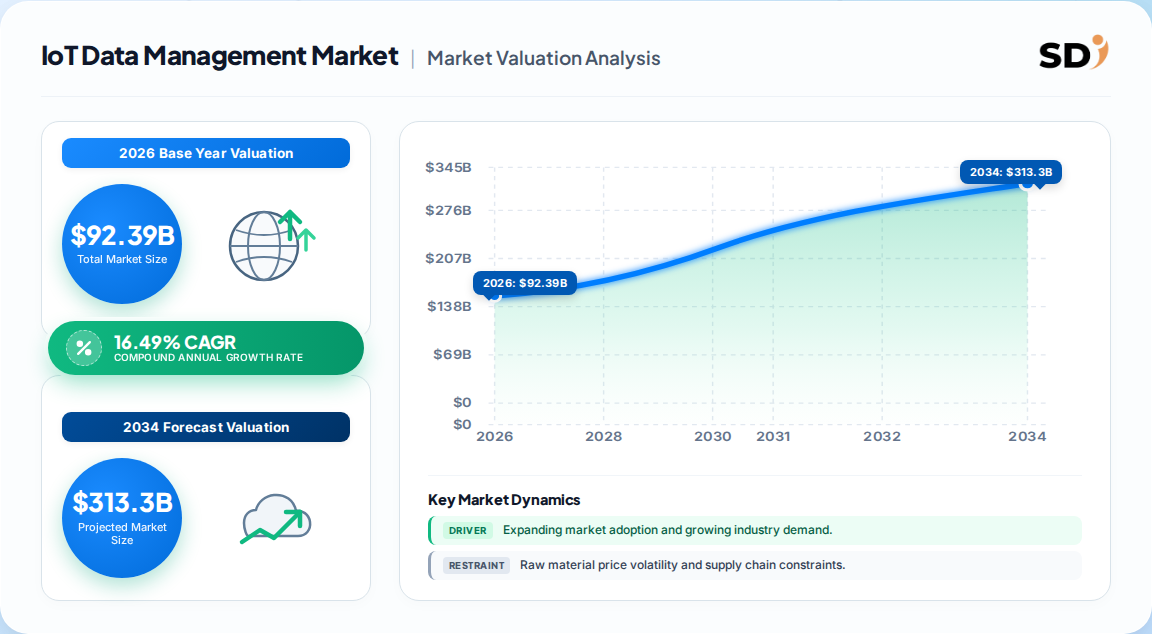
The global IoT Data Management Market is estimated at USD 92.39 billion in 2026, up from USD 79.31 billion in 2025. It is forecast to reach USD 197.94 billion by 2031 at a 16.49% CAGR, driven by connected-device growth and analytics demand.
North America leads with 40.55% of 2025 revenue, supported by hyperscaler proximity and industrial retrofit spending. Asia Pacific is the fastest-growing region at 17.56% CAGR, driven by manufacturing telemetry and utility metering scale-up.
Stream processing is the fastest-growing solution at 16.86% CAGR through 2031, while hybrid deployment grows at 17.12% CAGR. Healthcare and life sciences leads end-user growth at 17.19% CAGR, reflecting remote monitoring and trial digitization.
Leading vendors include Microsoft, AWS, Google Cloud, IBM, Cisco, Oracle, SAP, and PTC. Competition centers on unified ingestion, governance, and AI-ready analytics, with Cisco's Splunk acquisition sharpening differentiation around security-telemetry convergence.
Connected-device proliferation adds about 4.2% to CAGR, cloud-native analytics adds 3.4%, and regulatory governance pressure adds 3.0%. Real-time edge analytics and 5G network slicing contribute a further 4.5% combined, outweighing interoperability and TCO restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, with in-depth interviews across the IoT data management value chain. We engaged cloud infrastructure providers, telemetry platform vendors, systems integrators, industrial automation specialists, and managed-service providers. Decision-maker interviews covered VP-level platform engineering, Heads of Industrial Data Architecture, Chief Data Officers, and Commercial Operations Leads across manufacturing, healthcare, utilities, and smart-city programs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Data Officers & VP Engineering | 35% |
| Industrial Data Architects | 30% |
| Procurement & Vendor Management | 20% |
| Regulatory & Compliance Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud & Telemetry Platform Vendors | 40% |
| Systems Integrators & Managed Services | 30% |
| Industrial Automation & Device OEMs | 20% |
| Enterprise End-Users | 10% |
We triangulated findings against UN Comtrade, WTO digital-services trade statistics, US ITC filings, Eurostat ICT usage data, SEC 10-K filings, annual investor presentations, patent databases, and standards bodies including ISO/IEC JTC 1, IEEE, and the European Commission's Data Act impact assessments.
Simultaneous top-down macroeconomic allocation and bottom-up endpoint-base × managed-data-volume × realized-price modeling were applied. The 2025 base year was triangulated against public filings before forward CAGR application, cross-checked against IT budget allocations.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up endpoint & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |