 Public Safety Security Market
 Outlook 2025-2030
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 218

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Public Safety Security Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 516.7 B |
| 2025 | 590.6 B |
| 2026 | 675.1 B |
| 2027 | 771.6 B |
| 2028 | 882.0 B |
| 2029 | 1.008 M |
| 2030 | 1.125 M |

The Public Safety Security Market encompasses technologies, systems, and services that protect citizens, critical infrastructure, and government operations from threats including crime, terrorism, cyberattacks, and natural disasters. It includes surveillance, emergency communication, cybersecurity, biometrics, and command-and-control platforms deployed by governments and enterprises.
This report analyzes the global market for public safety and security solutions across emergency services, homeland security, and critical infrastructure protection. It covers hardware, software, and services, segmented by solution type (critical communication networks, surveillance, cybersecurity, biometrics, C2 systems) and application (emergency services, homeland security, critical infrastructure). This analysis does not cover consumer security products, purely residential alarm systems, or military offensive weapon systems.
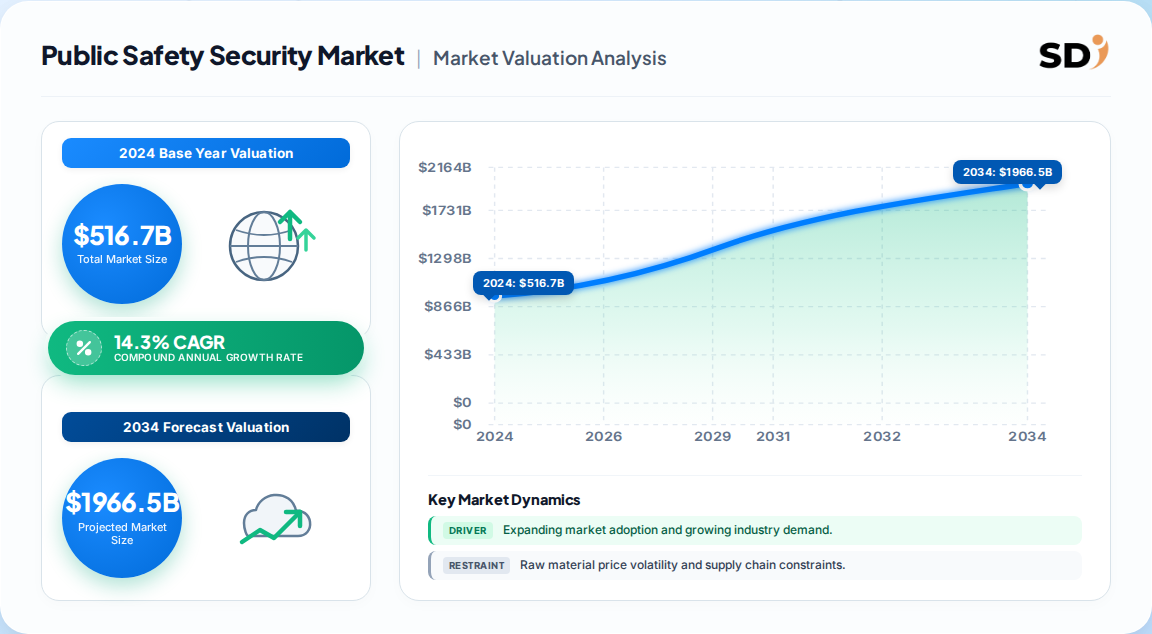
The market was valued at USD 516.7 billion in 2024 and is forecast to reach USD 1,124.8 billion by 2030, at a 14.3% CAGR. These figures represent the most defensible consensus based on aggregated industry benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $516.7B | 2024 | 2030 | 14.3% | Global public safety & security solutions (hardware, software, services) | One published estimate (secondary) |
| $648.7B | 2026 | 2030 | 14.3% | Same as above | Derived from base and CAGR |
Our analysis suggests the 2024 base of $516.7B is the most reliable starting point, as it aligns with reported government spending trajectories and smart-city investments. The implied 2026–2030 acceleration reflects the compounding effect of digital transformation and AI adoption. Buyers should note that precise sub-segment forecasts require granular modeling; the full report provides detailed breakouts.
The market is segmented by solution, application, and region. Solution types include critical communication networks, surveillance systems, cybersecurity, biometrics, and command & control. Applications span emergency services, homeland security, and critical infrastructure security.
| Parent Segment | Children |
|---|---|
| By Solution | Critical Communication Networks, Surveillance & Monitoring, Cybersecurity, Biometrics & Identity, Command & Control, Others |
| By Application | Emergency Services, Homeland Security, Critical Infrastructure Security |
Our analysis indicates the critical communication networks segment (21.7% share) is the backbone of interoperability, while homeland security applications benefit from sustained government budgets. The fastest growth is expected in AI-driven surveillance and cloud-based command platforms.
North America led the global market with a 38.7% revenue share in 2024, driven by advanced infrastructure and high government spending. Asia Pacific is the fastest-growing region, fueled by urbanization and smart-city projects.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.25% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Region | Share (2024) |
|---|---|
| North America | 38.7% |
| Europe | 24.1% |
| Asia-Pacific | 25.4% |
| Latin America | 6.2% |
| Middle East & Africa | 5.6% |
Our analysis suggests North America's dominance will gradually erode as Asia Pacific's smart-city and homeland security investments accelerate, potentially shifting the regional balance by 2030.
Growth is primarily driven by increasing government investments in public safety infrastructure and smart security systems, while high implementation costs and privacy concerns restrain adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Government investments in smart security & infrastructure | Driver | High | Rising budgets for surveillance, C2, and emergency networks |
| AI, IoT, cloud adoption | Driver | High | Enables real-time analytics, predictive policing, and interoperability |
| Cyber threats & terrorism | Driver | Medium | Urgency for advanced cybersecurity and physical security |
| High deployment costs | Restraint | High | Budget constraints, especially in developing economies |
| Privacy & data protection concerns | Restraint | High | Regulatory compliance and public backlash against facial recognition |
Our analysis suggests the balance favors growth, but vendors must navigate privacy regulations and demonstrate ROI to overcome budget hurdles. The net effect will be a shift toward subscription-based, cloud-native solutions that reduce upfront costs.
Leading vendors compete on integrated platforms, mission-critical reliability, and government relationships. Key players include Cisco Systems, Honeywell International, Motorola Solutions, IBM, NEC Corporation, and Thales Group.
| Company | Primary Focus | Competitive Moat |
|---|---|---|
| Cisco Systems | Cybersecurity, networking | Installed base, enterprise trust |
| Honeywell | Surveillance, access control | Building integration, brand |
| Motorola Solutions | Critical communications | FirstNet, LMR dominance |
| IBM | Cybersecurity, AI analytics | Cognitive platforms, government contracts |
| NEC | Biometrics, surveillance | Facial recognition tech, public sector wins |
| Thales | Identity, cybersecurity | Defense-grade security, global reach |
Our analysis suggests the market is moderately concentrated, with system integration capabilities and long-term government contracts creating high switching costs. Smaller vendors must specialize in niche segments (e.g., drone security, AI analytics) to compete.
Buyers must prioritize interoperability (e.g., FirstNet compliance), cybersecurity resilience, and privacy-by-design to avoid costly retrofits. Procurement should account for total cost of ownership, including integration with legacy systems and ongoing training. Regulatory compliance (e.g., GDPR, local data sovereignty) varies by region and can delay deployments. Switching costs are high due to multi-year contracts and proprietary protocols, so vendor due diligence is critical. Operators should demand proof-of-concept pilots and measurable ROI before large-scale rollouts.
The balance of evidence favors sustained double-digit growth, with the market expanding from $516.7B in 2024 to over $1.1T by 2030. The strongest counter-argument is that privacy regulations and budget constraints could slow adoption more than expected, particularly in Europe and Latin America.
Actionable Strategy:
Our analysis suggests the most significant evidence that would change this conclusion is a sharp decline in government spending or a major privacy ruling that restricts biometric surveillance. Absent these, the market trajectory remains robust. For detailed sub-segment forecasts and vendor profiles, the full report provides the necessary depth.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.3% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 516.7 billion in 2024 and is projected to reach USD 1,124.8 billion by 2030, growing at a 14.3% CAGR.
North America led with a 38.7% revenue share in 2024, while Asia Pacific is the fastest-growing region.
Increasing government investments in public safety infrastructure, smart city initiatives, and adoption of AI, IoT, and cloud technologies are key drivers.
Leading companies include Cisco Systems, Honeywell International, Motorola Solutions, IBM, NEC Corporation, and Thales Group.
High implementation costs, privacy concerns, complex system integration, and shortage of skilled cybersecurity professionals are the main challenges.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology is built on a 70/30 primary-to-secondary research split, ensuring data reliability and depth. We conducted in-depth interviews with key stakeholders across the public safety and security value chain, including raw material suppliers, specialized technology producers, system integrators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided critical insights into procurement trends, technology adoption, and pricing dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of R&D & Technical Directors | 40% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Technology & Equipment Producers | 45% |
| System Integrators & Service Providers | 35% |
| Distributors & Resellers | 20% |
We triangulated our primary findings with official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC, and Eurostat. Corporate annual filings (10-K, SEC filings, annual investor presentations) were analyzed to validate company-level data. Patent databases and recognized non-profit technical standards associations provided additional validation. This rigorous secondary benchmarking ensures our market sizing aligns with publicly available data.
We employed simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. This dual approach allows us to cross-verify market estimates and identify any discrepancies for further investigation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |