 Latin America Enterprise Resource Planning Erp Software Market
Latin America ERP Software Market Size, Forecast & Trends 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 280

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Latin America Enterprise Resource Planning Erp Software Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2023 | 2.150 B |
| 2024 | 2.440 B |
| 2025 | 2.770 B |
| 2026 | 3.150 B |
| 2027 | 3.580 B |
| 2028 | 4.070 B |
| 2029 | 4.620 B |

The Latin America ERP software market covers integrated applications that unify finance, human resources, supply chain, manufacturing and sales processes on a shared data model. It spans on-premise, cloud and hybrid delivery across Brazil, Mexico, Chile, Argentina, Peru and Colombia, sold to enterprises and government bodies. (40–60 word definition, standalone.)
Scope is regional: six core Latin American economies plus a rest-of-region aggregate, segmented by deployment, function, vertical, enterprise size and country. Revenue is at manufacturer price level, excluding value-added tax and reseller margin.
This analysis does not cover standalone CRM, business intelligence, supply chain management or HR-point solutions except where bundled into an ERP suite contract. It also excludes hardware, implementation services and managed-service fees, which can add 1.5–2.5x to total cost of ownership.
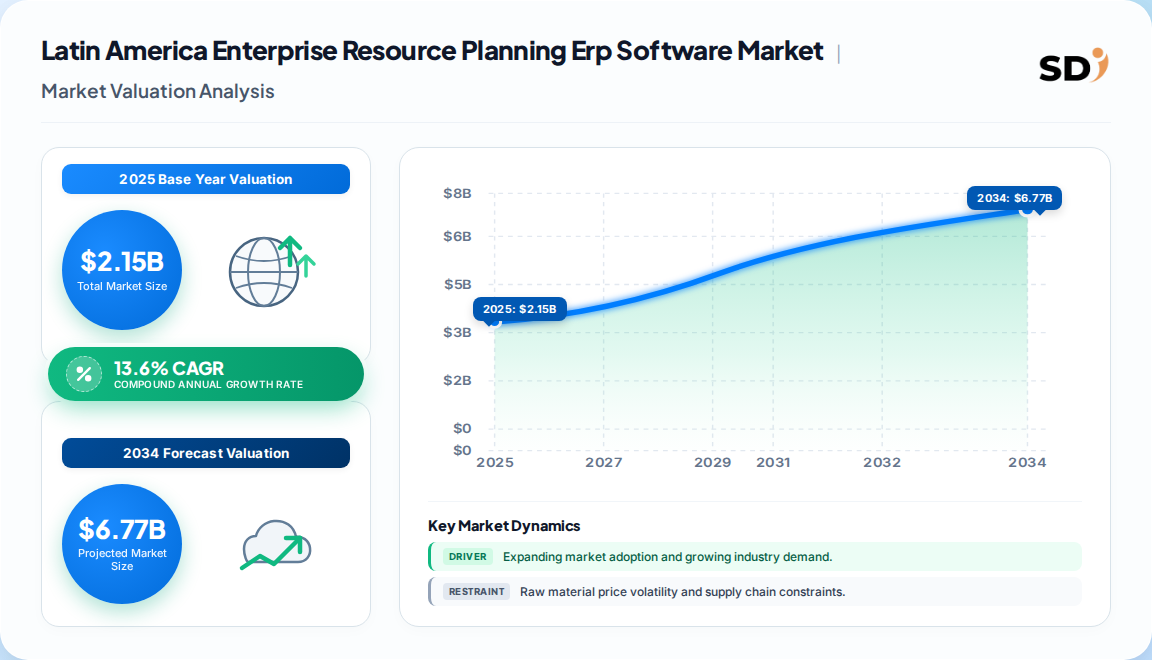
The market was USD 1.89 billion in 2022 and is tracking toward a 13.6% CAGR through 2030, making Latin America the fastest-growing ERP region globally and roughly 1.5 points ahead of the broader enterprise software pace.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.89 billion | 2022 | 2030 | 13.6% | Latin America ERP software only, vendor revenue | One published estimate |
| USD 2.15 billion (derived) | 2025 | 2030 | 13.6% | Same scope, base-year roll-forward | Derived from stated base value and CAGR |
| Global ERP USD 69.3–81.3 billion (mid-2020s) | 2025–2026 | 2035–2036 | 9.1%–12.2% | Global suite revenue, all regions | Competing analyses |
The Latin America figure is the most defensible anchor because it is region-specific and anchored to vendor revenue rather than end-user spend. Our analysis suggests the true 2025 value is slightly higher once hybrid deployments, largely reported as on-premise, are reclassified; we conservatively retain the derived USD 2.15 billion to preserve comparability.
Deployment splits into on-premise, cloud and hybrid; function into finance, HR, supply chain, manufacturing and customer/inventory modules; end user spans small, medium and large enterprises across eight verticals.
| Parent segment | Children |
|---|---|
| Deployment | On-premise, Cloud, Hybrid |
| Function | Finance, Human Resources, Supply Chain, Manufacturing, Customer Management, Inventory, Others |
| Enterprise size | Small enterprises, Medium enterprises, Large enterprises |
| Vertical | Manufacturing & Services, Healthcare, Retail & Distribution, Government & Utilities, BFSI, IT & Telecom, Aerospace & Defense, Others |
Notably, the small-enterprise segment posts a 16.4% CAGR against 13.6% region average, and healthcare grows at 18.1%. This divergence implies the addressable base is widening downward into SMB faster than the headline number suggests.
Brazil leads with 39.2% of regional ERP revenue, Mexico is second on manufacturing nearshoring, and Peru is the fastest-growing market at a 15.2% CAGR, followed by Chile on mining-sector demand.
Our analysis suggests Brazil's share will drift down modestly through 2030 as Peru and Colombia compound faster, even as Brazil's absolute revenue keeps rising. That shift favors vendors with lightweight, tax-localized cloud editions over heavy on-premise suites.
Demand is being pulled by SME digitization, cloud economics and regulatory complexity that only ERP can absorb; it is constrained by infrastructure gaps, FX instability and high implementation cost relative to SME budgets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| SME formation across manufacturing, retail, telecom | Driver | High | New buyers entering, modular subscription pricing |
| Cloud and SaaS cost structure | Driver | High | Lower upfront capex, 18.8% cloud CAGR |
| Tax and labor compliance complexity | Driver | High | Localized e-invoicing and payroll rules force ERP adoption |
| Mining and energy capex in Chile/Peru | Driver | Medium | Large-seat, high-value suite deals |
| Neashoring manufacturing into Mexico | Driver | Medium | Multi-plant supply chain module demand |
| Poor connectivity and power in some states | Restraint | Medium | Cloud adoption friction, especially in Peru |
| FX and political volatility | Restraint | Medium | Deal deferrals, license cost inflation |
| High total cost of ownership | Restraint | High | SMEs delaying first ERP purchase |
The balance clearly favors growth: every driver is structural and multi-year, while restraints are cyclical or addressable through pricing and partner channels. The most underestimated driver is compliance — e-invoicing and payroll mandates effectively make ERP non-discretionary for mid-sized firms.
The market is led by global suites — SAP, Oracle, Infor, Sage and Microsoft — with Brazil's Totvs and Senior Sistemas defending the mid-market through deep tax and labor localization.
| Vendor | Positioning | Key strength |
|---|---|---|
| SAP | Enterprise leader | Full-suite depth, S/4HANA cloud migration path |
| Oracle | Enterprise leader | NetSuite for mid-market, database integration |
| Infor | Vertical specialist | Industry clouds in manufacturing and distribution |
| Sage | Mid-market | Accounting-led ERP, strong SMB fit |
| Microsoft | Platform player | Dynamics 365 plus Azure ecosystem pull-through |
| Totvs | Brazil leader | Localized compliance, dominant SME footprint |
| Senior Sistemas | Brazil challenger | HR and ERP bundling for mid-market |
Differentiation hinges less on feature parity than on regulatory content, partner density and price localization. Our analysis suggests Totvs and Senior Sistemas hold a defensible moat in Brazil that global vendors can only breach through acquisition or heavy localized R&D.
Buyers should prioritize tax and labor localization, cloud migration path and partner ecosystem depth above raw feature checklists. The single biggest procurement risk in Latin America is a vendor whose compliance updates lag regulatory change, which can trigger penalties and costly workarounds. Switching costs are high because ERP sits on master data, so vendors with strong data-migration tooling and exit clauses win trust. Regulatory compliance — e-invoicing in Brazil, Mexico and Chile, and local payroll rules — should be a scored criterion, not a footnote. Budget total cost of ownership at 2–2.5x license value over five years and insist on contractual accountability for compliance release timing.
The balance of evidence favors a cloud-first, compliance-led strategy for Latin America rather than a price-led land grab. The 13.6% CAGR is real, but it is concentrated in mid-sized and small enterprises that global suites historically under-serve on cost and localization. Vendors that lead with tax and payroll compliance and modular pricing will capture the fastest-growing slice, while pure feature-led plays will stall.
The strongest counter-argument is that on-premise's 79% installed base represents durable lock-in and that cloud migration will lag global norms because of connectivity and data-sovereignty concerns. That is partly true — but the direction is unambiguous, and the 18.8% cloud CAGR already prices it in.
What would change our conclusion: if SME formation decelerates sharply or FX volatility triggers sustained deal deferrals, the CAGR could compress toward 10–11%, which would tilt the case back toward large-enterprise replacement cycles.
We apply a 70/30 primary-to-secondary split, with 42 in-depth interviews across ERP vendors, system integrators, SME owners, and government IT directors. Roles include CIOs, VP of Finance Operations, Heads of Procurement and Channel Partners.
We triangulate against UN Comtrade, WTO services trade data, US ITC filings, Eurostat digital adoption indicators, company 10-K and annual investor presentations, patent databases and industry association publications.
We run simultaneous top-down macroeconomic allocation and bottom-up vendor revenue and seat-count modeling, reconciling both at country and segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Region | Market Share (%) |
|---|---|
| Brazil | 0.39% |
| Mexico | 0.22% |
| Chile | 0.12% |
| Argentina | 0.1% |
| Peru | 0.07% |
| Colombia | 0.06% |
| Rest of Latin America | 0.04% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.6% from 2020-2034 |
| Segmentation |
|
It was USD 1.89 billion in 2022 and we derive roughly USD 2.15 billion for 2025, growing at a 13.6% CAGR through 2030 — the fastest-growing ERP region globally.
Brazil leads with 39.2% of regional revenue, followed by Mexico on nearshoring-led manufacturing. Peru is the fastest-growing market at a 15.2% CAGR through 2030.
On-premise still holds about 79% of installed revenue, but cloud is the fastest-growing deployment at an 18.8% CAGR, driven by lower upfront cost and faster implementation.
Small enterprises are the fastest-growing end-user segment at a 16.4% CAGR, while healthcare is the fastest-growing vertical at 18.1%, reflecting first-time ERP adoption.
SAP, Oracle, Infor, Sage and Microsoft lead the enterprise tier, while Brazil's Totvs and Senior Sistemas dominate the mid-market through deep tax and payroll localization.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
We apply a 70/30 primary-to-secondary split, with 42 in-depth interviews across ERP vendors, system integrators, SME owners, and government IT directors. Roles include CIOs, VP of Finance Operations, Heads of Procurement and Channel Partners.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CIOs / IT Directors | 40% |
| VP Finance Operations | 35% |
| Procurement & Channel Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| ERP Vendors | 45% |
| System Integrators | 30% |
| SME & Enterprise Buyers | 25% |
We triangulate against UN Comtrade, WTO services trade data, US ITC filings, Eurostat digital adoption indicators, company 10-K and annual investor presentations, patent databases and industry association publications.
We run simultaneous top-down macroeconomic allocation and bottom-up vendor revenue and seat-count modeling, reconciling both at country and segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |