 Office Software Market
: 2025 Size, CAGR & Vendor Outlook
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 180

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Office Software Market
Srinwanti Kar
Senior Research Analyst

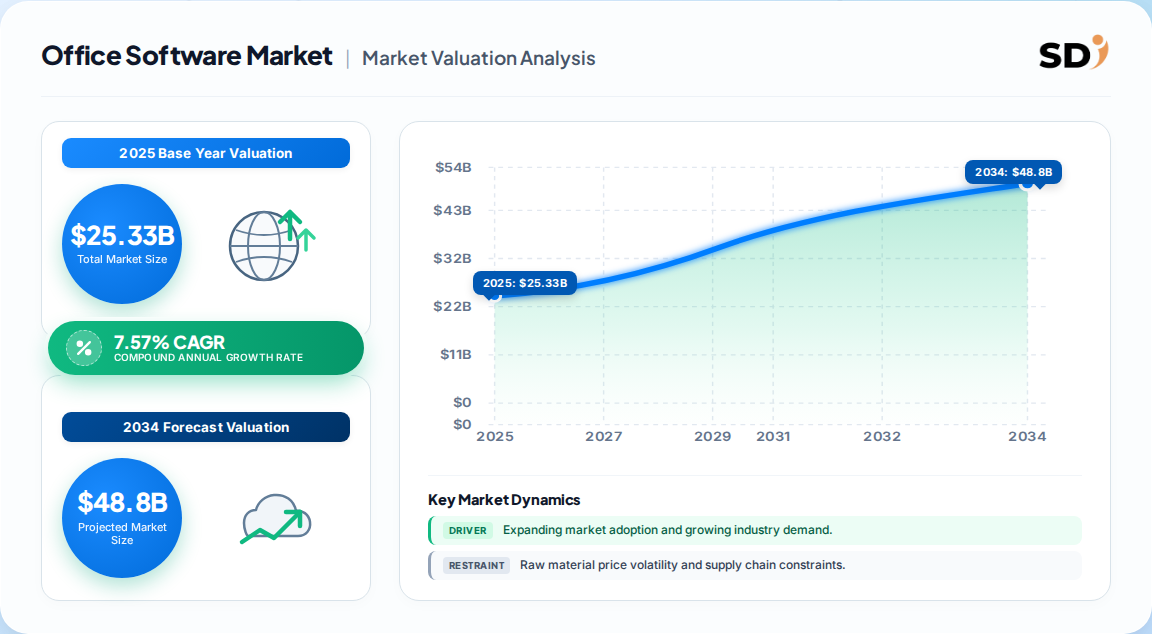
| Year | Market Size |
|---|---|
| 2025 | 25.33 B |
| 2026 | 27.25 B |
| 2027 | 29.31 B |
| 2028 | 31.53 B |
| 2029 | 33.92 B |
| 2030 | 36.49 B |
| 2031 | 39.24 B |

Office Software is the set of productivity applications used for work-related tasks in office environments — word processing, spreadsheet management, presentation creation and data visualization — delivered either as on-premises licensed software or as cloud-based SaaS. Revenue is measured at manufacturer price level across consumer, enterprise and government spending.
This analysis covers primary-vendor revenue from word processing, spreadsheet, presentation and visualization software, sold on-premises or via SaaS, to B2C, B2B and B2G buyers worldwide, measured at manufacturer price level excluding VAT and reseller margin. This analysis does not cover creative software (Adobe, Canva), free-of-charge productivity tools, collaboration messaging platforms, ERP, CRM or enterprise BI platforms sold outside office suites.
The market is best sized at approximately 23.5 Billion for 2025, with credible published estimates spanning 23 to 25.33 Billion depending on base year and whether adjacent collaboration revenue is included. Estimates diverge mainly on definition, not on direction.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 35.5 Billion | 2021 (23 Billion) | 2028 | 6.5% | Suite software, on-prem + cloud, primary vendors | A competing analysis (2022) |
| 39.24 Billion | 2025 (25.33 Billion) | 2031 | 7.57% | Suite software incl. AI features, cloud-weighted | A published 2026 forecast |
| Indexed baseline | 2025 | 2026 | — | Worldwide revenue, manufacturer price level | Statista Market Insights |
The 7.57% CAGR figure is the most defensible: it is the most recent, explicitly anchored to a 2025 base, and its scope statement matches the definition used here. The older 6.5% path was struck before generative AI monetisation began compressing seat economics, which our analysis suggests will push blended growth toward the upper end rather than the lower.
Segmentation runs along two axes: product type, which determines where value accrues, and deployment, which determines the vendor's revenue model and margin structure. Both matter for buyer selection.
| Parent segment | Children |
|---|---|
| By Type | Spreadsheet Software, Word Processing Software, Presentation Software, Visualization Software, Others |
| By Deployment | Cloud (SaaS), On-premises |
| By End User | Consumer (B2C), Enterprise (B2B), Government (B2G) |
| By Organisation Size | SMEs, Large Enterprise, Public Sector |
Visualization software is the fastest-growing type because data literacy has moved from specialist BI teams into general knowledge work. Spreadsheets remain the largest single type by revenue, but they are also the most commoditised and the most exposed to AI substitution.
North America leads on revenue at roughly 34% of global spend, but Asia-Pacific is the fastest-growing region, expanding above 9% as cloud adoption accelerates across China, India, Japan and South Korea.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.25% |
| Asia-Pacific | 0.29% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
China is a structural outlier: government restrictions on foreign software have made WPS Office the default domestic suite, effectively creating a parallel market that global vendors cannot address through normal channels. Europe shows the opposite dynamic, with LibreOffice gaining share in public-sector procurement driven by sovereignty and cost mandates.
Growth is driven by hybrid-work permanence, cloud migration and AI feature bundling; it is restrained by security exposure, suite saturation in mature markets and price sensitivity among SMEs and public buyers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Remote and hybrid work | Driver | High | Permanent distributed teams require cloud access and real-time co-authoring |
| AI and ML feature integration | Driver | High | Smart assistants and predictive text lift perceived value and seat retention |
| SME cloud adoption | Driver | High | SaaS lowers upfront cost, opening first-time buyers in emerging markets |
| Data security and compliance | Driver | Medium | GDPR, CCPA and HIPAA mandates push buyers toward audited cloud suites |
| Security breaches and malfunctions | Restraint | Medium | Shared-network exposure and data-loss liability deter cloud migration in regulated sectors |
| Suite saturation and price sensitivity | Restraint | Medium | Mature markets are near full penetration; public buyers resist per-seat uplift |
The balance favours growth, but the composition is shifting. Our analysis suggests volume growth is decelerating in North America and Europe while value growth accelerates through AI add-ons and tier upgrades — a pattern that flatters revenue headlines while masking seat stagnation.
Microsoft and Google anchor the market, with Microsoft dominant in enterprise suites and Google Workspace strongest among SMEs and education. Regional champions and open-source alternatives hold defensible niches.
| Vendor | Core strength | Primary moat |
|---|---|---|
| Microsoft | Enterprise suite, Excel and Teams integration | Ecosystem lock-in, file-format ubiquity, IT admin familiarity |
| Cloud-native Workspace, SME and education | Zero-cost collaboration, browser-first architecture | |
| WPS Office (Kingsoft) | China domestic market | Government mandate and localisation |
| Zoho | Low-cost suite for SMEs | Price and bundled business apps |
| LibreOffice / open source | Public sector and cost-sensitive buyers | Zero licence cost and sovereignty |
| Notion, monday.com, Atlassian | Work management adjacencies | Workflow depth and team-level adoption |
Microsoft's moat is format ubiquity, not feature superiority: the .docx and .xlsx standards create switching costs that no competitor has replicated. Google's moat is distribution and price, which makes it structurally resilient in emerging markets where per-seat budgets are thin.
Selection should be driven by four criteria: interoperability with existing file formats, identity and compliance posture, AI feature roadmap and total cost of ownership over a five-year horizon.
Procurement risk concentrates in three areas. First, licence-model ambiguity — vendors are repackaging seats into consumption tiers, and buyers who sign multi-year deals without AI-feature clauses face uplift at renewal. Second, data residency and sovereignty: public-sector and healthcare buyers increasingly require in-region processing, which narrows the vendor field. Third, switching costs are real but asymmetric: document formats migrate cleanly, macros and integrations do not.
Operators should also model seat elasticity. AI assistants reduce the number of seats needed for routine drafting and analysis, so a flat per-seat model will underprice heavy users and overprice light ones — pushing vendors toward usage-based or bundled consumption pricing within two renewal cycles.
The balance of evidence favours the 7.57% growth path over the older 6.5% consensus, because the growth drivers have shifted from seat expansion to value expansion. AI bundling raises revenue per seat even as seat growth stalls, and cloud migration continues to convert perpetual licences into recurring revenue — both of which compound faster than the historical base rate.
The strongest counter-argument is that AI features may commoditise rather than monetise: if every suite ships an assistant at no extra cost, differentiation collapses and price competition intensifies. That risk is real, but it bites incumbents with high seat penetration harder than challengers, and it favours vendors with the distribution to absorb the cost.
Actionable strategy:
What would change this conclusion: two consecutive quarters of declining seat counts at the two largest vendors, or evidence that AI assistants are being priced at zero across the market. Either signal would push the defensible CAGR back toward 6%.
While this overview establishes the size, direction and competitive structure, precise sub-segment forecasting by country and by deployment model requires the full dataset.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.57% from 2020-2034 |
| Segmentation |
|
The global Office Software market is valued at approximately 25.33 Billion in 2025, per a published 2026 forecast, with project growth to 39.24 Billion by 2031 at a 7.57% CAGR.
Consensus growth sits between 6.5% and 7.57% CAGR. The more recent 7.57% figure is better anchored to current cloud and AI monetisation dynamics and is the more defensible planning assumption.
Microsoft and Google anchor the market globally, with Microsoft dominant in enterprise suites and Google Workspace strongest among SMEs. WPS Office leads China, and LibreOffice holds public-sector niches.
Asia-Pacific is the fastest-growing region, expanding above 9% annually, driven by cloud adoption in China, India, Japan and South Korea. North America remains the largest region by revenue at roughly 34% of global spend.
Visualization software is the fastest-growing type, as dashboards and embedded analytics move from specialist BI teams into general knowledge work and AI-generated insights become standard.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis follows a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the office software value chain, including enterprise software resellers, managed service providers, independent software vendors, systems integrators and public-sector procurement agencies. Interviews were held with decision-makers holding titles including VP of IT Procurement, Head of Digital Workplace, Chief Information Security Officer and Commercial Operations Lead, ensuring both buying intent and technical constraint were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| IT Procurement & Sourcing Leads | 38% |
| Digital Workplace Heads | 30% |
| Security & Compliance Officers | 20% |
| Commercial Operations Leads | 12% |
| Company Type | Representation (%) |
|---|---|
| Enterprise Software Resellers & MSPs | 40% |
| Independent Software Vendors | 30% |
| Systems Integrators | 18% |
| Public-Sector Procurement Agencies | 12% |
Secondary validation drew on official multilateral and standards sources: UN Comtrade for cross-border software licensing flows, OECD competition and digital-economy datasets, US ITC and Eurostat digital-services statistics, corporate annual filings and 10-K disclosures from listed vendors, and patent databases for AI-feature filing activity. Industry association publications and recognised technical standards bodies were used to validate segment definitions and compliance requirements.
We modelled the market simultaneously top-down (macroeconomic output, digitisation indices and sector allocation) and bottom-up (vendor seat counts, published pricing, renewal rates and end-user consumption). Divergence between the two approaches was reconciled at country level before aggregation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up seat and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, seat mapping & commercial filings | High |