 Plastics Personal Protective Equipment Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 268

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Plastics Personal Protective Equipment Market
Khageshwar Rongkali
Senior Analyst

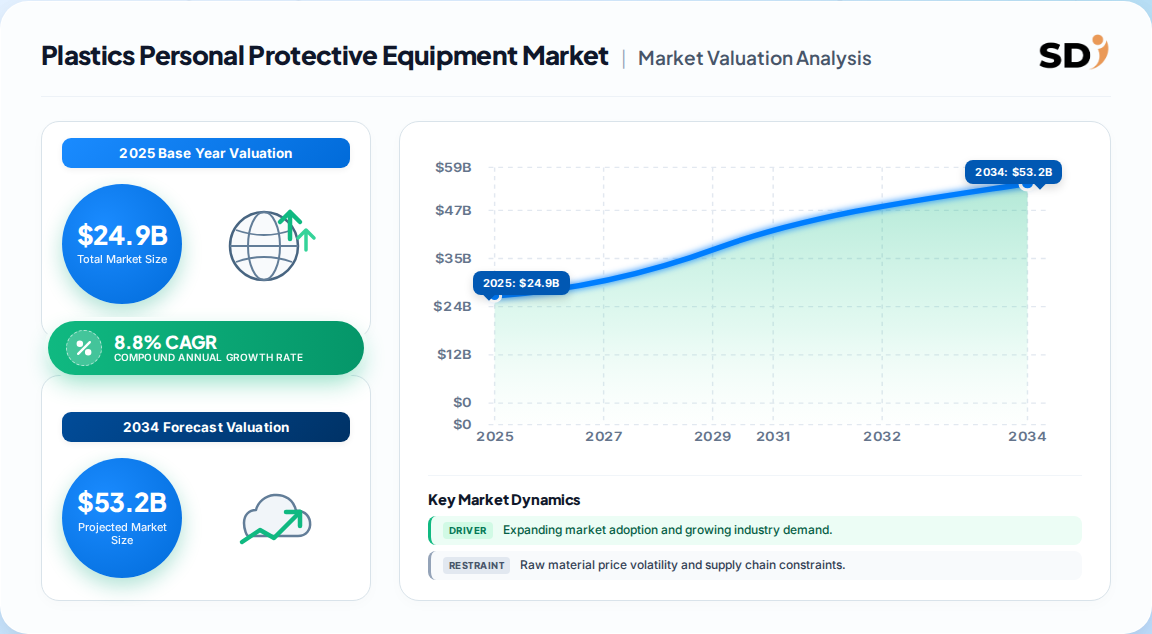
| Year | Market Size |
|---|---|
| 2025 | 24.90 B |
| 2026 | 29.30 B |
| 2027 | 31.90 B |
| 2028 | 34.70 B |
| 2029 | 37.80 B |
| 2030 | 41.10 B |
| 2031 | 44.70 B |

The plastics in personal protective equipment market encompasses the supply of polymer-based materials—polyethylene, polypropylene, polyurethane, polycarbonate, and PET—used to manufacture PPE such as gloves, masks, gowns, face shields, and protective footwear. These plastics provide barrier protection, chemical resistance, durability, and lightweight comfort essential for healthcare, construction, manufacturing, and hazardous industrial applications.
This analysis covers the global market for plastic materials consumed in PPE manufacturing, segmented by product type (PE, PP, PU, and others) and application (hand protection, protective clothing, respiratory protection, head/eye/face protection, hearing protection, and protective footwear). It spans the 2025–2035 forecast horizon and includes regional and country-level breakdowns across Asia Pacific, North America, Europe, Latin America, and the Middle East & Africa. This analysis does not cover finished PPE product retail markets, textile-based PPE without plastic content, or non-plastic PPE materials such as leather and metal components.
Published estimates diverge by nearly 20 Billion in projected 2033–2035 values, reflecting differing assumptions about post-pandemic demand normalization and sustainability-driven material substitution.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 24.9 Billion | 2025 | 2033 (53.0 Billion) | 8.8% | Plastics in PPE, all products and applications | One published estimate |
| 20.84 Billion | 2025 | 2035 (33.67 Billion) | 4.9% | Plastics in PPE, PE/PP/PU and others | A competing analysis |
The 8.8% CAGR appears to assume accelerated healthcare infrastructure investment and rapid adoption of sustainable polymers that command premium pricing. The 4.9% CAGR likely reflects a more conservative view of post-COVID normalization and slower replacement cycles in industrial PPE. Our analysis suggests the lower forecast is more defensible for volume-based planning, while the higher figure better captures value growth from premium sustainable materials. Buyers should model both scenarios and stress-test procurement budgets against raw-material price volatility, which 76% of stakeholders cited as their primary concern.
Segmentation spans product type and application, with polyethylene and hand protection dominating current revenue but polypropylene and respiratory protection gaining share as healthcare standards tighten.
| Parent Segment | Children |
|---|---|
| By Product | Polyethylene (PE), Polypropylene (PP), Polyurethane (PU), Polycarbonate (PC), PVC, PET, Others |
| By Application | Hand Protection, Protective Clothing, Respiratory Protection, Head/Eye/Face Protection, Hearing Protection, Protective Footwear, Others |
Polyethylene's 24.4% share is anchored in high-volume disposable applications like gowns and aprons where cost and flexibility matter most. Polypropylene follows closely, particularly in surgical masks and nonwoven medical textiles where breathability and filtration efficiency are critical. The application mix is shifting toward respiratory and face protection as regulatory standards—including FDA and OSHA requirements—demand higher barrier performance, creating opportunities for higher-margin engineering plastics.
Asia Pacific leads with 48.7% of global revenue in 2025, driven by China's manufacturing scale, low-cost production, and expanding healthcare infrastructure across India and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.49% |
| North America | 0.22% |
| Europe | 0.19% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Parent Region | Countries / Sub-regions |
|---|---|
| Asia Pacific | China, Japan, India, South Korea, Australia-New Zealand |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Latin America | Brazil, Argentina, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Asia Pacific's dominance reflects both consumption and production concentration—China alone grows at 6.5% CAGR, faster than any other major economy. North America and Europe prioritize chemical resistance and sustainability compliance respectively, creating premium niches for high-performance polymers. The Middle East & Africa region is the fastest-growing, albeit from a small base, as industrialization and workplace safety regulations expand. This divergence implies vendors should localize material formulations: cost-optimized PE for Asia, chemical-resistant PC for North America, and recyclable bio-based polymers for Europe.
Growth is driven by healthcare demand, regulatory tightening, and material innovation, while raw-material price volatility and environmental concerns constrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Healthcare industry demand | Driver | High | Rising infection prevention, disposable PPE consumption in hospitals |
| Stringent safety regulations (OSHA, FDA, EU) | Driver | High | Mandates certified PPE, boosts plastic material consumption |
| Sustainable/recyclable PPE adoption | Opportunity | Medium | 89% of stakeholders demand recyclable plastics |
| Raw material cost fluctuations | Restraint | High | 76% of stakeholders cite price volatility as top concern |
| Environmental concerns over plastic waste | Restraint | Medium | Regulatory pressure on single-use plastics, microplastic pollution |
The balance of evidence suggests demand-side drivers outweigh supply-side restraints through 2030, but the margin between them narrows significantly after 2030 as environmental regulations on single-use plastics intensify in Europe and North America. Healthcare demand is the most reliable growth engine—hospitals, dental clinics, and diagnostic centers are expanding globally, and polypropylene-based disposable masks and gowns remain the standard. However, the sustainability transition represents a double-edged sword: it creates premium pricing opportunities for bio-based and recyclable materials while threatening volume demand for conventional single-use plastics. Vendors that fail to develop recyclable or biodegradable product lines risk regulatory exclusion from European public procurement within five years.
The competitive landscape is dominated by diversified chemical and materials companies that supply plastic raw materials and specialized compounds to PPE manufacturers, with differentiation built on material performance, ESG compliance, and regional production agility.
| Company | Key Plastic Products | PPE Applications | Strategic Focus |
|---|---|---|---|
| BASF SE | Ultramid (PA), Elastollan (TPU) | Face shields, protective garments | High-performance engineering plastics |
| SABIC | Polycarbonates | Impact-resistant face shields, visors | Clarity and impact strength |
| Evonik Industries | Lightweight polymers | Healthcare and industrial PPE | Chemical resistance, lightweighting |
| DuPont | Polypropylene, specialty fibers | Surgical masks, breathable PPE | High-performance nonwovens |
| Arkema | Bio-based polymers | Sustainable PPE solutions | Renewable material innovation |
| Sumitomo | Specialty plastics | Protective equipment components | Regional supply chain strength |
Competitive moats are built on three pillars: material certification and regulatory approval (FDA, EU CE marking), integrated production systems that ensure supply reliability, and ESG credentials that increasingly determine procurement eligibility. BASF and SABIC leverage their scale and brand trust, while Arkema and Sumitomo differentiate through bio-based offerings. Our analysis suggests mid-tier suppliers face margin compression unless they secure either cost leadership in commodity PE/PP or specialized positions in antimicrobial or smart-material niches. Recent developments include partnerships between manufacturers and healthcare providers to recycle face masks into new medical products, signaling a shift toward circular economy models that could reshape competitive dynamics.
Procurement decisions in this market hinge on three mission-critical criteria: regulatory compliance, supply chain resilience, and total cost of ownership. Buyers must verify that plastic materials meet applicable standards—FDA requirements for medical PPE, OSHA regulations for industrial applications, and EU PPE Regulation 2016/425 for European procurement. Non-compliance can result in product recalls, liability exposure, and exclusion from public tenders. Supply chain risk is acute: 76% of stakeholders cite raw material price volatility as their primary concern, and the pandemic demonstrated how quickly demand shocks can disrupt availability. Buyers should qualify multiple suppliers across regions and consider dual-sourcing strategies for critical materials like polypropylene nonwovens. Switching costs are moderate—material substitution is feasible but requires re-certification and performance testing, which can take 6–12 months. Operators should also monitor the sustainability transition closely: European procurement rules are increasingly favoring recyclable or bio-based materials, and early adoption of certified sustainable polymers can create competitive advantage in public tenders. Finally, buyers should demand full traceability documentation from suppliers, as regulatory scrutiny of microplastic pollution and single-use plastic waste intensifies globally.
The balance of evidence favors a cautious growth outlook, not because demand is weak but because the market is undergoing a structural transition that will redistribute value rather than simply expand it. Healthcare demand is robust and will continue to anchor volume growth, but the pricing environment is shifting toward sustainable materials that command premiums while conventional plastics face regulatory headwinds. The 8.8% CAGR forecast captures this premiumization effect; the 4.9% forecast reflects volume growth in a business-as-usual scenario. The strongest counter-argument to our cautious view is that healthcare infrastructure investment in emerging markets could accelerate faster than expected, particularly if post-pandemic preparedness spending remains elevated. If India, Brazil, and Southeast Asian nations sustain current investment rates, volume growth could approach the higher forecast.
Actionable Strategy:
The evidence that would change our conclusion is a sustained acceleration in healthcare spending in emerging markets above 7% annually, or a regulatory rollback on single-use plastic restrictions in Europe and North America. Absent these developments, the structural shift toward sustainable materials and the geographic center of gravity in Asia Pacific will define competitive success through 2035. Precise sub-segment forecasting—particularly for smart PPE with embedded sensors—requires deeper primary research than publicly available data can support.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.8% from 2020-2034 |
| Segmentation |
|
The market was valued at 24.9 Billion in 2025 and is estimated at 29.3 Billion in 2026. Forecasts diverge, projecting 33.67 Billion by 2035 at 4.9% CAGR or 53.0 Billion by 2033 at 8.8% CAGR, reflecting different assumptions about sustainability-driven premiumization and healthcare demand.
Asia Pacific dominates with 48.7% of global revenue in 2025, driven by China's manufacturing scale and expanding healthcare infrastructure in India and Southeast Asia. The Middle East & Africa is the fastest-growing region, albeit from a smaller base.
Polyethylene (PE) leads with 24.4% market share, used primarily in disposable gowns and aprons. Polypropylene (PP) follows for surgical masks and nonwovens. Polycarbonate, PET, and polyurethane serve specialized applications requiring impact resistance, clarity, or flexibility.
Healthcare demand for infection prevention, stringent workplace safety regulations from OSHA and FDA, and material innovation in barrier protection are primary drivers. Sustainability requirements and smart PPE technologies represent emerging growth opportunities.
BASF, SABIC, Evonik, DuPont, Arkema, and Sumitomo lead the market. They compete on material performance, regulatory compliance, and ESG credentials, with integrated production systems and certified sustainable product lines providing competitive advantage.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized PPE producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated demand drivers, pricing dynamics, and regulatory compliance requirements across healthcare, construction, manufacturing, and oil and gas end-use sectors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Polymer Producers | 40% |
| Specialized PPE Manufacturers | 35% |
| Distributors & Supply Chain Intermediaries | 25% |
Secondary research draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ISO, FDA, OSHA, and EU regulatory bodies. Trade flow analysis validated regional consumption patterns and cross-border material flows.
Market sizing employs simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic and industry segment data to PPE material consumption; bottom-up modeling builds from manufacturer capacity, product pricing, and end-use consumption data. Divergences between approaches were reconciled through stakeholder validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |