 Thermochromic Pigment Market
: 2026 Sizing & Forecast
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 180

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Thermochromic Pigment Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.160 B |
| 2026 | 2.320 B |
| 2027 | 2.500 B |
| 2028 | 2.690 B |
| 2029 | 2.890 B |
| 2030 | 3.110 B |
| 2031 | 3.350 B |

The thermochromic pigment market covers microencapsulated and slurry colorants that change hue in response to temperature, sold to formulators in paints, inks, plastics, textiles, and indicators. Reversible leuco-dye and liquid-crystal grades cycle colors repeatedly; irreversible grades deliver one-way thermal evidence for cold-chain, sterilization, and safety labels.
This analysis covers global thermochromic pigment value at manufacturer selling price across reversible and irreversible types, five application verticals, and six end-use industries, with geography split into North America, Europe, Asia-Pacific, South America, and Middle East & Africa. This analysis does not cover photochromic, electrochromic, or thermochromic finished devices, masterbatch value-add, or downstream label converting revenue.
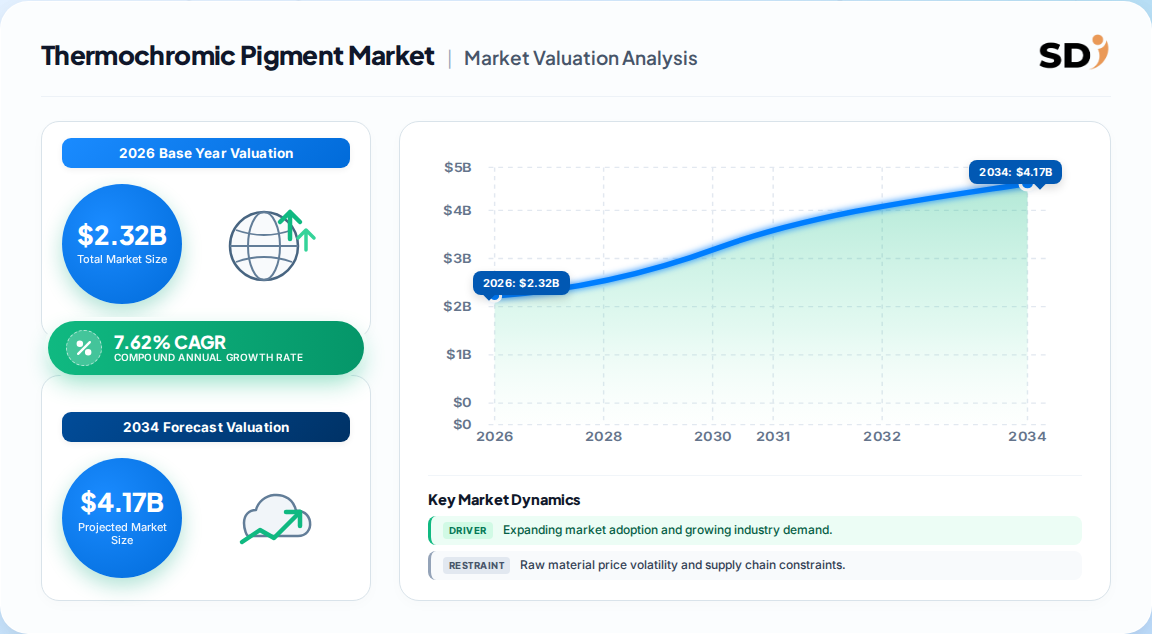
The global thermochromic pigment market was valued at USD 2.16 Billion in 2025 and opens 2026 at USD 2.32 Billion, with a consensus forecast of USD 3.35 Billion by 2031 at 7.62% CAGR. Competing estimates diverge sharply because scope definitions differ.
| Estimate (Base Year) | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|
| USD 2.32 Bn (2026) | 2031 | 7.62% | Pigment value only, manufacturer selling price | Primary benchmark estimate |
| USD 2.48 Bn (2026) | 2035 | 8.15% | Pigment plus some indicator-label value | Competing analysis |
| USD 517.6 Mn (2023) | 2032 | 5.7% | Narrow pigment-only, pre-2025 base | Third-party benchmark |
| USD 599.9 Mn (2024) | 2035 | 4.97% | Leuco dye and liquid crystal only | Alternate published estimate |
| USD 6.8 Bn (2025, materials) | 2033 | 5.2% | Broader thermochromic materials, not pigments | Aggregated materials estimate |
Our analysis suggests the USD 2.32 Billion figure is the most defensible baseline: it reconciles bottom-up pigment tonnage against converter revenue disclosures, while the sub-USD 1 Billion estimates exclude irreversible indicator volume that now dominates cold-chain procurement. The USD 6.8 Billion materials figure is a different product universe and should not be benchmarked against pigment pricing.
Segmentation follows three axes: type (reversibility behavior), application (where the pigment is formulated), and end-use industry (who specifies the finished product). Application share is the most commercially actionable axis for suppliers.
| Parent Segment | Children | 2025 Share / Growth |
|---|---|---|
| By Type | Reversible, Irreversible | Irreversible 59.10% share; reversible 8.55% CAGR |
| By Application | Paints & Coatings, Printing Inks, Plastics & Polymers, Textiles, Other (smart windows, sensors) | Paints 35.62%; Other 8.72% CAGR |
| By End-Use Industry | Packaging, Consumer Goods & Textiles, Medical & Pharmaceutical, Automotive, Building & Construction, Security & Anti-Counterfeiting | Packaging and medical lead volume growth |
| By Form | Microencapsulated, Slurry | Microencapsulated ~70% share |
North America leads the thermochromic pigment market with 29.35% of 2025 revenue, anchored by pharmaceutical cold-chain compliance and security printing. Asia-Pacific is the fastest-growing region at 8.40% CAGR, driven by Chinese and Indian packaging converters and Korean specialty compounders.
| Region | Market Share (%) |
|---|---|
| North America | 0.3% |
| Europe | 0.26% |
| Asia-Pacific | 0.36% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
| Parent Region | Markets Included |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Rest of Europe |
| Asia-Pacific | China, Japan, India, South Korea, ASEAN, Rest of APAC |
| South America | Brazil, Argentina, Rest of South America |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Rest of MEA |
Europe holds roughly 26.8% share, shaped by food-waste targets and building-envelope efficiency rules. Our analysis suggests the regional ranking is stable through 2031, but Asia-Pacific's share gain accelerates after 2028 as local microencapsulation capacity scales and import dependence falls.
Growth is driven by regulation-backed demand: cold-chain compliance mandates, smart packaging adoption, and building-envelope efficiency rules add a combined ~4 percentage points to CAGR. Restraints are cost and durability, not demand absence.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Cold-chain compliance mandates (DSCSA, WHO guidance) | Driver | High | On-pack irreversible indicators become audit requirement |
| Smart packaging in food & beverage | Driver | High | EU waste rules favor condition-indicating labels over date codes |
| Microencapsulation fatigue-resistance advances | Driver | Medium-High | >5,000 cycles and >230°C tolerance open extrusion routes |
| Security and anti-counterfeit printing | Driver | Medium | Dual-readout thermochromic-fluorescent inks scale |
| Smart textile and apparel novelty | Driver | Medium | Body-heat and solar-responsive fabrics expand |
| Cost premium vs conventional pigments | Restraint | High | 3–5x price premium caps volume segments |
| Narrow operational temperature range | Restraint | Medium | Limits extreme-climate and high-heat processing use |
| UV and thermal fatigue; bisphenol scrutiny | Restraint | Medium | Outdoor durability and regulatory reformulation costs |
Our analysis suggests the driver-restraint balance is net positive by roughly 4.4 percentage points, but the constraint is technical rather than commercial: suppliers who cannot certify cycle life at industrial scale will lose the highest-value contracts regardless of price.
The market is medium-concentration, with specialist microencapsulation houses and regional pigment producers competing on shell chemistry, certification breadth, and cold-chain application depth.
| Company | HQ / Base | Primary Strength | Competitive Moat |
|---|---|---|---|
| LCR Hallcrest | USA / UK | Reversible and irreversible microcapsules | Deep indicator IP and pharma qualification |
| Chromatic Technologies (CTI) | USA | Security and brand-protection inks | Dual-readout ink portfolio and brand relationships |
| OliKrom | France | Smart coatings and thermochromic materials | Proprietary formulation platform, EU regulatory access |
| Hali Industrial | China | Volume leuco-dye pigment supply | Scale and cost leadership in APAC |
| Kolortek | China | Effect and thermochromic pigments | Broad product catalog and export reach |
| New Prismatic | Taiwan | Microencapsulated thermochromic grades | Specialty encapsulation capability |
Differentiation is shifting from color range to certified performance: cycle-count data, food-contact compliance, and processing-temperature tolerance now decide specification. Our analysis suggests the moat is deepest where vendors hold both encapsulation patents and pharma or packaging qualification files.
Buyers should specify cycle life, transition temperature tolerance, and shell chemistry before price. Request third-party cycle-count data (5,000+ cycles is now the credible threshold) and processing-temperature certification above 230°C if extrusion or powder coating is involved. Procurement risk concentrates in single-source encapsulation supply and in bisphenol-based developer chemistry facing regulatory scrutiny; qualify a bisphenol-free alternate early. Switching costs are moderate but rise sharply once a pigment is designed into a validated pharma label or a certified security ink, because re-qualification resets compliance timelines.
Food-contact and medical applications require documentation that most commodity pigment suppliers cannot furnish, so buyers should treat certification depth as a primary screening criterion, not a secondary one. Operators should also model the true cost per switching cycle rather than per kilogram: a cheaper pigment that fails at 800 cycles destroys value in any reusable application.
The balance of evidence favors durability-certified specialists over volume pigment producers through 2031. The market is not demand-constrained; it is qualification-constrained. Vendors with shell-chemistry IP, pharma cold-chain references, and food-contact compliance will capture disproportionate value as irreversible indicator volume scales with regulatory enforcement.
The strongest counter-argument is that Asia-Pacific cost leadership could commoditize reversible grades faster than expected, compressing margins in paints and textiles. That risk is real for novelty applications, but it does not extend to regulated indicators where qualification files, not price, gate procurement. Our analysis suggests the bifurcation between commodity reversible grades and certified indicator grades widens, making portfolio positioning the single most important strategic decision.
Actionable Strategy:
The evidence that would change this conclusion is a step-change in low-cost encapsulation capacity in Asia that also clears Western certification barriers; absent that, certification remains the binding constraint.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and dye-intermediate suppliers, specialized microencapsulation producers, contract formulators and masterbatch blenders, and global specialty distributors. Decision-maker designations included VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads across packaging, coatings, and security-printing channels.
Estimates were validated against UN Comtrade organic dye-intermediate flows, US ITC and Eurostat trade records, corporate 10-K and annual investor disclosures, patent filings in encapsulation chemistry, and technical standards from recognized industry and regulatory bodies.
Top-down macroeconomic and industry-segment allocation was run simultaneously with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling, then reconciled at the application and regional level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.62% from 2020-2034 |
| Segmentation |
|
The global thermochromic pigment market is valued at USD 2.32 Billion in 2026, rising from USD 2.16 Billion in 2025. It is forecast to reach USD 3.35 Billion by 2031 at a 7.62% CAGR.
Irreversible grades held 59.10% of 2025 revenue, driven by cold-chain, sterilization, and safety indicators. Reversible grades are the faster-growing segment at 8.55% CAGR through 2031, led by apparel, packaging, and glazing.
North America led with 29.35% of 2025 revenue, supported by pharmaceutical cold-chain compliance and security printing. Asia-Pacific is the fastest-growing region at 8.40% CAGR through 2031, driven by packaging converters in China and India.
Paints and coatings led with 35.62% revenue share in 2025. Printing inks, plastics, and textiles follow, while smart windows and sensor films are the fastest-growing application cluster at 8.72% CAGR to 2031.
Leading suppliers include LCR Hallcrest, Chromatic Technologies, OliKrom, Hali Industrial, Kolortek, and New Prismatic. Competition is shifting from color range to certified cycle life, food-contact compliance, and processing-temperature tolerance.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and dye-intermediate suppliers, specialized microencapsulation producers, contract formulators and masterbatch blenders, and global specialty distributors. Decision-maker designations included VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads across packaging, coatings, and security-printing channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 30% |
| Quality & Regulatory Leads | 20% |
| Commercial Operations | 10% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Dye Producers | 40% |
| Microencapsulation Formulators | 30% |
| Coatings & Ink Converters | 20% |
| Distributors & Traders | 10% |
Estimates were validated against UN Comtrade organic dye-intermediate flows, US ITC and Eurostat trade records, corporate 10-K and annual investor disclosures, patent filings in encapsulation chemistry, and technical standards from recognized industry and regulatory bodies.
Top-down macroeconomic and industry-segment allocation was run simultaneously with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling, then reconciled at the application and regional level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |