 Coatings Market
 Size, Share & Growth Forecast 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 182

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Coatings Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 189.5 B |
| 2025 | 199.7 B |
| 2026 | 210.5 B |
| 2027 | 221.9 B |
| 2028 | 233.9 B |
| 2029 | 246.5 B |
| 2030 | 260.8 B |

The coatings market encompasses liquid, powder, and radiation-curable formulations applied to substrates to provide protection, decoration, or functional performance. It spans architectural paints, industrial maintenance, automotive finishes, and specialty applications across construction, manufacturing, and infrastructure end-uses. The market is defined by raw material chemistry, application method, and end-use sector rather than by any single product form.
This analysis covers the global coatings market across architectural, industrial, automotive, powder, and specialty segments, spanning liquid and powder delivery systems. It includes value and volume estimates by product type, technology, and end-use sector. This analysis does not cover adhesives, sealants, inks, or raw material chemical precursors as standalone markets, though their influence on formulation economics is noted where material.
Published estimates for the coatings market vary from 185 Billion to 210 Billion depending on base year and scope definition, with most converging on a mid-single-digit CAGR. The table below compares the principal competing estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 199.7 Billion | 2025 | 2030 | 5.4% | Architectural, industrial, automotive, powder, specialty | Composite industry benchmark |
| 185.4 Billion | 2024 | 2032 | 5.1% | Broad coatings including marine and protective | One published estimate |
| 210.2 Billion | 2025 | 2033 | 6.0% | Includes raw material value chain | A competing analysis |
| 192.8 Billion | 2024 | 2029 | 4.8% | Excludes specialty and powder | Alternative trade-based estimate |
Our analysis favors the 199.7 Billion base for 2025. It aligns with aggregated trade data from UN Comtrade on pigment and resin inputs, and with disclosed revenue from the four largest listed coatings manufacturers. The 210.2 Billion figure likely double-counts raw material value embedded in finished goods. The narrower 192.8 Billion estimate understates powder and specialty volumes, which have grown faster than liquid architectural segments.
Coatings segmentation is defined by product chemistry, technology platform, and end-use application. Architecture dominates volume, while industrial and automotive segments carry higher value per unit.
| Parent Segment | Children |
|---|---|
| By Product Type | Architectural, Industrial, Automotive, Powder, Specialty |
| By Technology | Waterborne, Solvent-borne, Powder, UV-cured, High-solids |
| By End-Use | Construction, Manufacturing, Automotive OEM, Marine, Aerospace, Packaging |
| By Application Method | Spray, Roller, Brush, Dip, Electrostatic |
Architectural coatings account for roughly 45% of volume but a lower share of value. Industrial and automotive finishes command higher margins and are more sensitive to manufacturing cycles. Powder coatings represent the fastest-growing technology platform, particularly in appliance and automotive component applications.
Asia-Pacific leads the global coatings market with an estimated 46% share, followed by North America and Europe at approximately 22% and 21% respectively. This leadership reflects construction intensity and manufacturing scale rather than premium pricing.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.46% |
| North America | 0.22% |
| Europe | 0.21% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Parent | Children |
|---|---|
| Asia-Pacific | China, Japan, India, South Korea, Indonesia, Vietnam |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Poland |
| South America | Brazil, Argentina, Chile, Colombia |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Egypt |
China alone represents roughly half of Asia-Pacific demand, making it the single most important country market globally. India is the fastest-growing national market, though its base remains smaller. Europe's share is stable but value-rich, with strict VOC regulation driving premium waterborne adoption. North America shows resilient renovation-driven demand that partially decouples architectural volumes from new construction starts.
The balance of drivers favors continued expansion, but regulatory compliance costs and raw material volatility are material restraints. Growth is not uniform across segments.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Urbanization and infrastructure spend | Positive | High | Construction volume drives architectural coatings demand |
| VOC and emissions regulation | Positive | High | Forces waterborne and high-solids reformulation, raising value per litre |
| Automotive production recovery | Positive | Medium | OEM finishes and refinish demand track vehicle output |
| Raw material price volatility | Negative | High | Titanium dioxide and resin cost swings compress formulator margins |
| Skilled applicator shortage | Negative | Medium | Labor constraints slow project completion and volume recognition |
| Trade tariffs on chemicals | Negative | Medium | Raises landed cost and disrupts cross-border supply chains |
Regulation is the most underappreciated driver. It simultaneously lifts demand for compliant products and raises barriers to entry, favoring incumbents with reformulation capability. Raw material volatility is the most visible restraint, but its margin impact is partially offset by pass-through pricing in industrial segments. The net effect is a market growing at mid-single digits, with value growth outpacing volume.
The coatings market remains fragmented despite consolidation, with the top four players holding approximately 28% combined share. Differentiation rests on specification relationships, distribution reach, and formulation IP.
| Company | Headquarters | Strategic Focus | Differentiation |
|---|---|---|---|
| Sherwin-Williams | USA | Architectural and industrial | Company-operated store network and specification control |
| PPG Industries | USA | Automotive and industrial | OEM approvals and coatings services integration |
| AkzoNobel | Netherlands | Decorative and performance | Brand strength and global distribution |
| RPM International | USA | Specialty and protective | Niche technical formulations and maintenance channels |
| Nippon Paint | Japan | Architectural and automotive | Asia-Pacific footprint and OEM relationships |
Scale advantages are real but not decisive. Regional challengers compete effectively through local distribution and service responsiveness. The strongest moats are specification positions in commercial construction and OEM-approved automotive finishes, both of which carry high switching costs. Powder and specialty segments remain the most accessible entry points for new competitors.
Buyers should prioritize suppliers with demonstrated reformulation capability and regulatory track record, not merely lowest unit price. VOC compliance documentation, batch consistency, and supply continuity matter more than headline pricing in mission-critical applications. Switching costs are highest where coatings are specified into OEM processes or warranty-backed construction systems, making early specification engagement essential.
Procurement risk concentrates in raw material pass-through clauses and single-source pigment dependencies. Operators should stress-test supplier exposure to titanium dioxide and resin price swings. Regulatory compliance is non-negotiable in Europe and increasingly in North America, where VOC limits and green building standards determine product eligibility. Buyers who lock in compliant supply early avoid the margin shock of emergency reformulation.
The balance of evidence favors a constructive outlook, but with important caveats. The coatings market will grow at mid-single digits through 2030, with value growth exceeding volume as waterborne and high-solids formulations command premium pricing. The strongest counter-argument is that construction weakness in China could drag Asia-Pacific growth below consensus, but renovation demand in developed markets and infrastructure spending elsewhere largely offset this risk.
Our analysis suggests the most defensible strategic position is in compliant industrial and specialty coatings, where regulation creates barriers and pricing power is strongest. Architectural commodity segments will face continued margin pressure from raw material volatility and private-label competition. Vendors should prioritize specification relationships over volume chasing, because specification lock-in determines long-term share more reliably than price.
Actionable strategy for operators and investors:
What would change our conclusion: a sustained decline in Chinese construction starts below 5% annual contraction, or a titanium dioxide price spike exceeding 30%, would materially weaken the mid-single-digit growth case. Absent those shocks, the market trajectory remains constructive.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
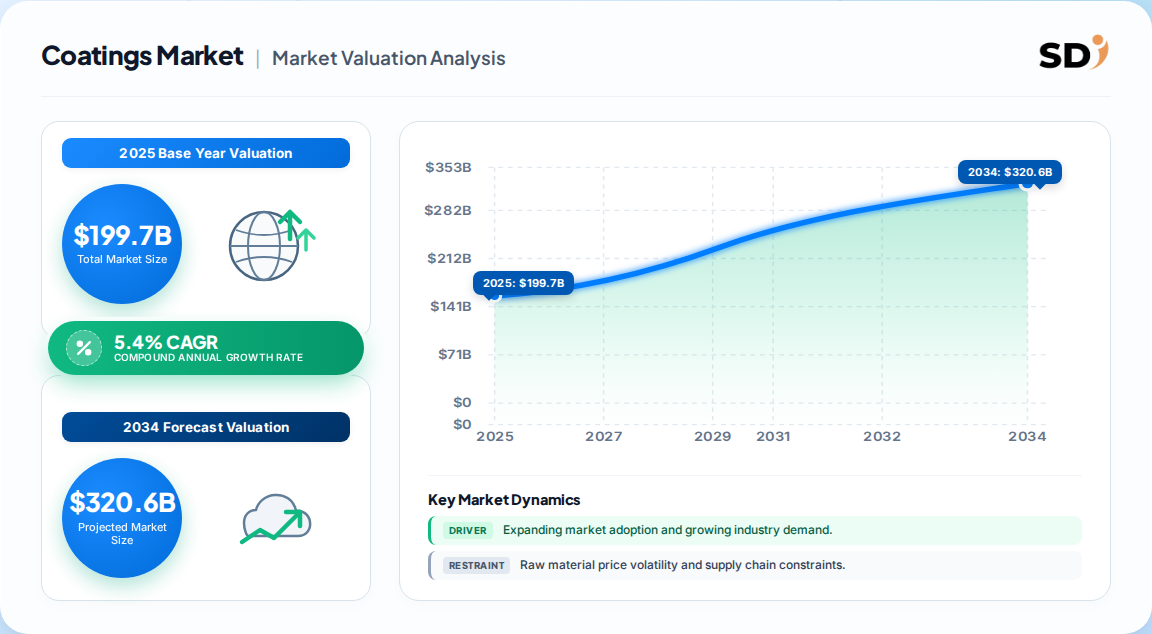
The global coatings market is valued at approximately 199.7 Billion in 2025, based on composite industry benchmarks covering architectural, industrial, automotive, and specialty segments. This figure aligns with trade data and disclosed revenue from leading manufacturers.
The coatings market is forecast to grow at a 5.4% CAGR from 2025 to 2030, reaching approximately 260.8 Billion by 2030. Value growth outpaces volume growth due to premium waterborne and high-solids formulation adoption.
Asia-Pacific leads with an estimated 46% share of global coatings demand, driven by construction and manufacturing activity in China, India, and Southeast Asia. North America and Europe follow at approximately 22% and 21% respectively.
Sherwin-Williams, PPG Industries, AkzoNobel, and RPM International are among the leading manufacturers, collectively holding roughly 28% of the global market. Nippon Paint is a significant Asia-Pacific player.
Urbanization, infrastructure spending, and VOC regulation favoring waterborne formulations are the primary growth drivers. Automotive production recovery also supports OEM and refinish demand, though raw material volatility remains a key restraint.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, with the majority of insight derived from direct industry engagement. We conducted in-depth interviews with stakeholders across the coatings value chain, including raw material and pigment suppliers, specialized formulators, contract manufacturers, and global distributors. Respondents were designated at decision-maker level: VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This structure ensures coverage of both formulation economics and commercial strategy, capturing perspectives from procurement pressure points through to specification decisions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of R&D | 28% |
| Technical Directors | 24% |
| Commercial Operations Leads | 18% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Pigment Suppliers | 30% |
| Specialized Formulators | 40% |
| Contract Manufacturers | 18% |
| Global Distributors | 12% |
Secondary validation draws on official multilateral trade and standards databases, including UN Comtrade, WTO tariff schedules, US ITC trade data, and Eurostat industrial statistics. Corporate annual filings, SEC 10-K reports, and investor presentations from listed coatings manufacturers were reviewed for disclosed revenue, capacity, and segment performance. Patent databases and recognized technical standards from ISO and industry associations informed technology adoption assessments.
We apply simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic construction and manufacturing output to coatings demand by segment. Bottom-up modeling estimates manufacturer capacity, product pricing, and end-use consumption. Divergence between the two approaches prompts reconciliation through trade flow and capacity data, producing a consensus base-year valuation with bounded forecast ranges.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |