 Cryogenic Temperature Polymers Market
 Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 251

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cryogenic Temperature Polymers Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2021 | 2.410 B |
| 2022 | 2.590 B |
| 2023 | 2.780 B |
| 2024 | 2.980 B |
| 2025 | 3.200 B |
| 2026 | 3.400 B |
| 2027 | 3.650 B |

The cryogenic temperature polymers market covers high-performance polymers — PTFE, PEEK, UHMWPE, polyimide, and nylon — engineered to retain mechanical strength, dimensional stability, chemical resistance, and sealing integrity at temperatures below roughly −150°C. These materials serve LNG, hydrogen, medical gas, aerospace, semiconductor, and industrial gas applications where conventional elastomers brittle and fail.
This report covers global demand for cryogenic-grade polymers by polymer type (PTFE, PEEK, UHMWPE, polyimide, nylon, others), by application (seals and gaskets, insulation, bearings and bushings, valve components, liners and coatings, others), and by region across 2021–2033. It quantifies revenue in USD and volume in kilotons.
Excludes: general-purpose engineering plastics, non-cryogenic fluoropolymers, cryogenic fluids themselves (LNG, LN2, liquid hydrogen), cryogenic equipment hardware (turbines, pumps, dewars), and metal or ceramic cryogenic components. This analysis does not cover adjacent markets such as cold-chain packaging or refrigeration compressors.
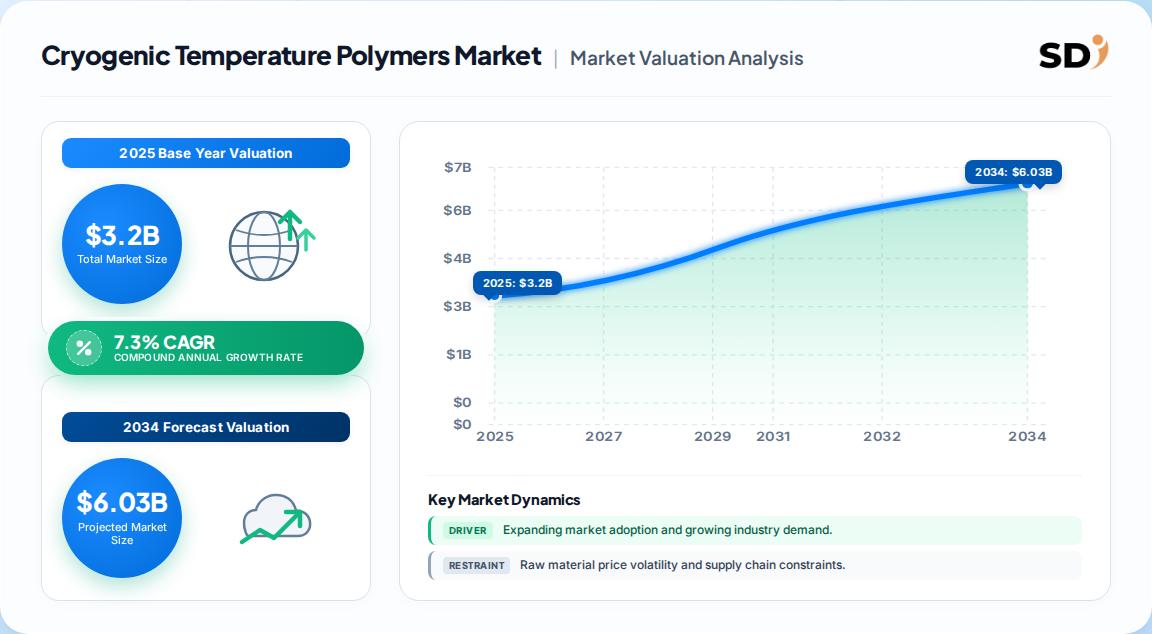
The global cryogenic temperature polymers market was valued at USD 3.2 Billion in 2025 and is forecast to reach USD 5.5 Billion by 2033, expanding at a 7.3% CAGR from 2026 to 2033. The base year 2026 is estimated at USD 3.4 Billion, implying roughly USD 200 Million of annual growth at current trajectory.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.2 Billion | 2025 | 2033 | 7.3% | Global revenue, all polymer types and applications | One published estimate (market research publisher) |
| USD 3.4 Billion | 2026 | 2033 | 7.3% | Global revenue, base-year 2026 estimate | Same publisher, adjacent year |
| USD 5.5 Billion | 2033 | — | 7.3% | Global revenue at forecast terminus | Same publisher, forecast |
| USD 453.7 Million (U.S.) | 2025 | 2033 | 7.4% | U.S. only, all segments | Companion country-level estimate |
| USD 800.6 Million (U.S.) | 2033 | — | 7.4% | U.S. forecast revenue | Companion country-level forecast |
Our analysis suggests the USD 3.2 Billion 2025 figure is the most defensible global anchor because it triangulates with the U.S. share of 14.3% (USD 453.7 Million) and Asia Pacific's 56.1% share (roughly USD 1.79 Billion). The derived arithmetic is internally consistent: 453.7 / 0.143 ≈ 3.17 Billion, within 1% of the stated 3.2 Billion. This internal coherence raises confidence in the forecast path, though the 7.3% CAGR rests on continued LNG and hydrogen capex that could slip by 12–18 months if energy transition spending decelerates.
Segmentation is defined by polymer chemistry (which determines temperature and chemical performance) and by component function (which determines qualification and certification pathways). The two axes interact: PEEK and polyimide skew toward structural and bearing roles, while PTFE and UHMWPE dominate sealing and lining.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| Polymer Type | PTFE, PEEK, UHMWPE, Polyimide, Nylon, Others | PTFE 38.7%; PEEK fastest at 8.5% CAGR |
| Application | Seals & Gaskets, Insulation, Bearings & Bushings, Valve Components, Liners & Coatings, Others | Seals & gaskets 39.3%; insulation fastest at 8.3% CAGR |
Implication: the overlap between PEEK's growth leadership and insulation's growth leadership points to a single high-value cluster — structural and thermally insulating components in hydrogen and LNG systems. Vendors positioned at that intersection command premium pricing and longer qualification moats.
Asia Pacific leads the global cryogenic temperature polymers market with 56.1% of 2025 revenue, driven by China's industrial manufacturing base, semiconductor expansion, and LNG import infrastructure. North America follows at roughly 19.8%, with the U.S. alone at 14.3% of global revenue.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.56% |
| North America | 0.2% |
| Europe | 0.15% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent | Children |
|---|---|
| Asia Pacific | China, Japan, India, South Korea, Australia |
| North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain |
| Latin America | Brazil, Argentina, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
| Region | 2025 revenue share |
|---|---|
| Asia Pacific | 56.1% |
| North America | 19.8% |
| Europe | 15.2% |
| Latin America | 4.8% |
| Middle East & Africa | 4.1% |
Our analysis suggests the Asia Pacific concentration is a double-edged signal. It reflects genuine demand growth, but it also concentrates pricing power in Chinese PTFE producers, which caps upside for Western specialty suppliers in the commodity tier. Europe's 15.2% share understates its strategic importance: European OEMs in LNG and hydrogen set much of the qualification standard that Asian and North American buyers follow.
Growth is driven by cryogenic infrastructure build-out in LNG, hydrogen, and medical gas, plus semiconductor and aerospace demand for dimensionally stable components. Restraints center on the high cost and processing complexity of PEEK and specialty PTFE grades, which lengthens qualification cycles and limits adoption in price-sensitive segments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| High-performance polymer adoption in cryogenic equipment | Driver | High | Substitution of metals and elastomers in seals, bearings, insulation |
| LNG and hydrogen infrastructure expansion | Driver | High | New capacity requires cryogenic seals, valves, and insulation |
| Semiconductor and medical cryogenic systems | Driver | Medium-High | Demand for low-outgassing, dimensionally stable components |
| High material and processing cost | Restraint | High | PEEK and specialty PTFE require specialized equipment and QC |
| Qualification and certification burden | Restraint | Medium | Aerospace, medical, and energy standards extend time-to-revenue |
| Alternative materials and conventional engineering plastics | Restraint | Medium | Price-sensitive segments may accept performance trade-offs |
The balance of evidence favors drivers through 2028, but the restraint most likely to bite is qualification cost, not raw material price. Our analysis suggests the binding constraint on market growth is the number of qualified cryogenic polymer grades, not the number of buyers — a supply-side bottleneck that favors incumbents with existing certifications.
The competitive landscape is fragmented at the converter level but concentrated at the polymer-resin level. Victrex and Daikin hold meaningful upstream positions in PEEK and fluoropolymers respectively, while Ensinger, Röchling, Saint-Gobain, Greene Tweed, and Pexco compete in semi-finished and finished cryogenic components.
| Company | Primary position | Cryogenic relevance |
|---|---|---|
| Victrex plc | PEEK resin and forms | High — PEEK is fastest-growing polymer type |
| Daikin Industries | Fluoropolymers (PTFE, PCTFE) | High — PTFE is largest type segment |
| DuPont | Fluoropolymers and specialty polymers | High — broad cryogenic portfolio |
| AGC Inc. | Fluorochemicals and specialty glass/polymers | Medium-High |
| Mitsubishi Chemical | Performance polymers | Medium |
| Ensinger | Semi-finished engineering plastics | High — cryogenic component conversion |
| Röchling | Industrial plastics and composites | High — LNG and industrial gas exposure |
| Saint-Gobain | Seals and high-performance materials | High |
| Greene Tweed | Sealing systems and composites | High — cryogenic seal specialization |
| Pexco | Engineered thermoplastic components | Medium |
Differentiation rests on three moats: certified grade portfolios (hard to replicate quickly), application engineering (seal design, thermal modeling), and long-term qualification contracts with LNG, aerospace, and medical OEMs. Our analysis suggests the strongest moat sits with firms that combine resin supply with application engineering — Victrex, Daikin, and Greene Tweed are best positioned on that axis.
Selection criteria in cryogenic polymer procurement are not primarily price-driven. The dominant criteria are low-temperature ductility retention, thermal expansion match with mating metals, outgassing behavior under vacuum, and long-term creep resistance under thermal cycling. A material that passes a single-cycle −196°C test but fails after 500 cycles is a liability, not a saving.
Procurement risk concentrates in three areas. First, grade equivalence: a supplier's "PEEK" may not match the qualified grade's crystallinity or filler system, requiring re-qualification. Second, switching costs: re-certifying a cryogenic seal or liner for LNG, medical, or aerospace service can take 9–18 months and cost six figures. Third, regulatory compliance: medical gas and semiconductor applications impose traceability, outgassing, and purity requirements that narrow the approved supplier list.
Operators should also watch supply concentration. PTFE resin supply is geographically concentrated, and a disruption in fluoropolymer feedstock would cascade into seal and liner availability within two to three quarters. Dual-sourcing at the semi-finished stage — not just the resin stage — is the practical hedge. Our analysis suggests buyers who lock in qualified grade supply agreements before 2027 will avoid the tightness likely to emerge as hydrogen projects move from FID to construction.
The balance of evidence favors a selective growth position on cryogenic temperature polymers through 2030, concentrated in PEEK, polyimide, and insulation applications rather than broad-market exposure. The 7.3% headline CAGR is credible, but it masks a bifurcation: commodity PTFE volumes grow at or below GDP-linked rates while PEEK and insulation grow at 8%+ on hydrogen and LNG thermal management.
The strongest counter-argument is that hydrogen infrastructure timelines have repeatedly slipped, and a 24-month delay in electrolyzer and liquefaction capex would pull the 2033 forecast toward USD 4.8–5.0 Billion rather than 5.5 Billion. That is a timing risk, not a structural one — the installed base still requires cryogenic polymers, but the revenue lands later. Investors should underwrite the thesis on LNG and semiconductor demand, which are more predictable, and treat hydrogen as upside optionality.
Actionable strategy:
What would change this conclusion: a sustained decline in LNG liquefaction FIDs below 2024 levels, or a breakthrough in metal or ceramic cryogenic sealing that displaces polymer seals in high-cycle applications. Neither is likely before 2029, but both warrant monitoring in the full report's scenario analysis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.3% from 2020-2034 |
| Segmentation |
|
The global cryogenic temperature polymers market was valued at USD 3.2 Billion in 2025 and is projected to reach USD 5.5 Billion by 2033, growing at a 7.3% CAGR from 2026 to 2033, according to one published estimate.
PTFE held the largest share at 38.7% of 2025 revenue due to its chemical resistance and low-temperature stability. PEEK is the fastest-growing type at 8.5% CAGR, driven by structural and high-cycle applications.
Asia Pacific led with 56.1% of global revenue in 2025, supported by China's manufacturing base, semiconductor expansion, and LNG infrastructure. North America followed at roughly 19.8%, with the U.S. at 14.3% of global demand.
Seals and gaskets are the largest application at 39.3% of 2025 revenue, followed by insulation, bearings and bushings, valve components, and liners and coatings. Insulation is the fastest-growing application at 8.3% CAGR.
Key players include Victrex, Ensinger, Saint-Gobain, Röchling, DuPont, Daikin, AGC, Mitsubishi Chemical, Pexco, and Greene Tweed. Competition centers on certified grade portfolios and application engineering rather than price alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with primary interviews forming the evidentiary backbone. We conducted in-depth interviews across the cryogenic polymer value chain, including raw material and fluoropolymer feedstock suppliers, specialized cryogenic polymer producers, contract formulators and compounders, semi-finished component converters, and global industrial distributors. Interviews were conducted with decision-makers holding titles including VP of Sourcing and Procurement, Head of Materials R&D, Technical Director for Cryogenic Systems, and Commercial Operations Lead. Fieldwork spanned North America, Europe, and Asia Pacific to capture regional qualification standards and pricing behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of Materials R&D | 30% |
| Technical Directors, Cryogenic Systems | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Fluoropolymer Feedstock Suppliers | 25% |
| Specialized Polymer Producers & Compounders | 30% |
| Semi-Finished Component Converters | 30% |
| Global Industrial Distributors | 15% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO tariff and trade statistics, US ITC DataWeb, Eurostat Comext), corporate regulatory filings (10-K and 20-F disclosures, annual investor presentations), patent databases for polymer formulation trends, and recognized technical standards bodies and non-profit industry associations active in cryogenic and high-performance polymer specification. Trade flows for fluoropolymers and PEEK precursors were cross-checked against reported revenue to detect volume-revenue gaps.
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic industrial and energy capex across cryogenic end-use segments, then applies polymer-intensity coefficients. The bottom-up model builds from manufacturer capacity, product pricing, and end-use consumption to derive revenue by polymer type and application. Divergence between the two models is reconciled at the segment level before the base-year figure is locked.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |