 Ceramic Textile Market
 2025: Size, CAGR & Forecast
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 198

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Ceramic Textile Market
Khageshwar Rongkali
Senior Analyst
| Year | Market Size |
|---|---|
| 2025 | 190.0 M |
| 2026 | 207.0 M |
| 2027 | 226.0 M |
| 2028 | 246.0 M |
| 2029 | 268.0 M |
| 2030 | 293.0 M |
| 2031 | 319.0 M |

The ceramic textile market comprises woven, braided, and non-woven fabrics made from refractory ceramic fibres (alumina-silica, polycrystalline, and low bio-persistent grades) used for high-temperature insulation, thermal protection, and fire shielding in industrial, transportation, and aerospace applications.
This report covers the global ceramic textile market across fibre types (vitreous alumina-silica, polycrystalline, low bio-persistent), forms (cloth, ropes, tapes, sleeving, braids), and end-use industries (industrial processing, transportation, electrical/electronics, aerospace/defense). This analysis does not cover ceramic matrix composites, monolithic refractories, or non-textile ceramic insulation products.
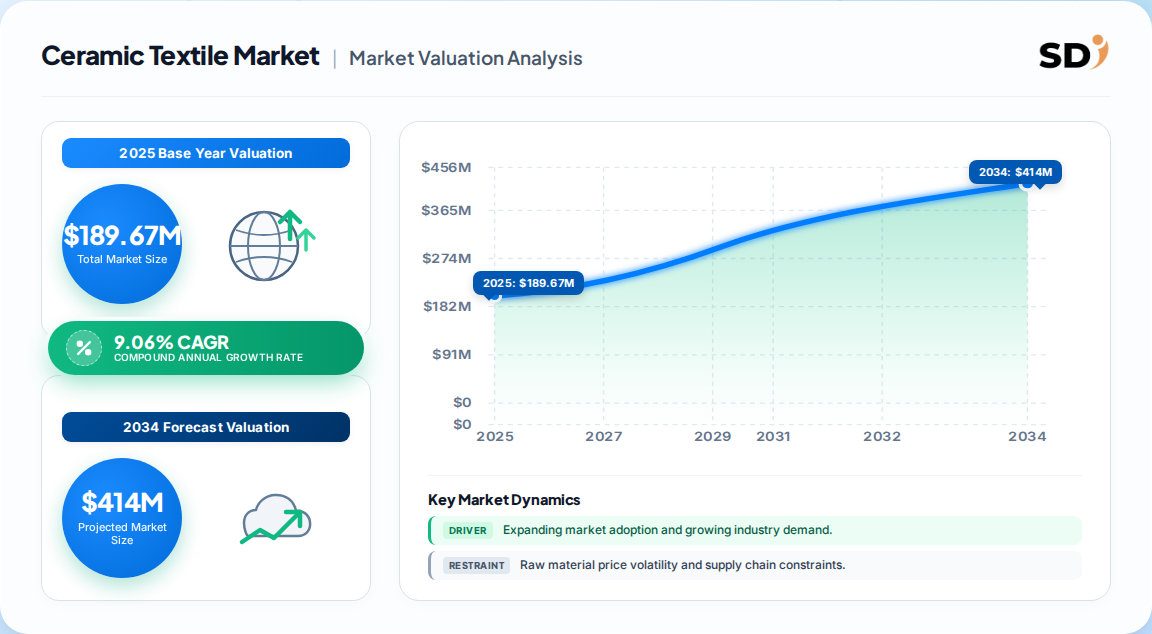
The market is estimated at $189.67 million in 2025, rising to $413.98 million by 2034 at a 9.06% CAGR. Estimates vary widely due to scope differences, particularly whether downstream fabricated products are included.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $189.67M → $413.98M | 2025 | 2034 | 9.06% | Ceramic textile products (fibre, cloth, ropes, tapes, sleeving) | One published estimate |
| $195.0M → $382.0M | 2023 | 2030 | 10.2% | Ceramic textile market, narrower product scope | A competing analysis |
| $1.41B → $2.49B | 2025 | 2034 | 6.52% | Broad ceramic textile including downstream fabricated systems | A competing analysis |
| $193.27M → $250.14M | 2026 | 2031 | 5.29% | Ceramic textile, conservative adoption assumptions | A competing analysis |
Our analysis suggests the $189–195 million range for 2025 is the most defensible base, as it aligns with multiple independent estimates and reflects actual fibre and textile product shipments. The $1.41 billion figure likely embeds downstream fabricated insulation systems and installation services, making it unsuitable for fibre-level procurement decisions. The 9.06% CAGR is supported by accelerating demand from battery gigafactories and EV thermal management, though upside is tempered by RCF regulatory headwinds.
The market is segmented by fibre type, form, and end-use industry, with industrial processing accounting for the largest share and electrical/electronics the fastest-growing end-use segment.
| Parent Segment | Children | Share / Growth |
|---|---|---|
| By Fibre Type | Vitreous Alumina-Silica, Polycrystalline, Low Bio-Persistent, RCF | RCF 55.62% (2025); Low bio-persistent 6.25% CAGR |
| By Form | Cloth, Ropes, Tapes, Sleeving, Braids | Cloth 37.55% (2025); Sleeving/Braids 6.73% CAGR |
| By End-Use Industry | Industrial Processing, Transportation, Electrical & Electronics, Aerospace & Defense | Industrial 45.88% (2025); Electrical 7.11% CAGR |
Asia Pacific leads with 41.84% of global revenue in 2025, driven by steel, petrochemical, and electronics manufacturing expansion across China, India, and Japan. North America follows at 28%, with Europe at 20%.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.42% |
| North America | 0.28% |
| Europe | 0.2% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
Global Ceramic Textile Market
- Asia Pacific (41.84%)
  - China
  - India
  - Japan
  - South Korea
- North America (28%)
  - United States
  - Canada
  - Mexico
- Europe (20%)
  - Germany
  - United Kingdom
  - France
  - Italy
- Latin America (6%)
  - Brazil
  - Mexico
  - Argentina
- Middle East & Africa (4%)
- Saudi Arabia
- UAE
- South Africa
| Region | Share (2025) | Key Demand Driver |
|---|---|---|
| Asia Pacific | 41.84% | Steel, petrochemical, electronics manufacturing |
| North America | 28.00% | Aerospace, defense, automotive |
| Europe | 20.00% | Energy efficiency regulations, automotive |
| Latin America | 6.00% | Industrial expansion, refining |
| Middle East & Africa | 4.00% | Petrochemical, construction |
High-temperature insulation demand and energy-efficiency regulations are the primary growth engines, while RCF carcinogenicity classification and high production costs are the main restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| High-temperature industrial insulation | Driver | High | Steel, glass, petrochemical kilns >1,200°C require ceramic textiles; 30% heat loss reduction vs. refractory bricks |
| Energy-efficiency regulations | Driver | High | GHG disclosure rules make ceramic insulation a compliance pathway; +0.8% CAGR impact |
| Battery gigafactory thermal management | Driver | Medium-High | Ceramic blankets in oven walls and pack assemblies; +0.9% CAGR impact |
| RCF carcinogenic classification | Restraint | High | 0.2 fibres/cm³ exposure limits increase costs; EU substitution mandates accelerate low bio-persistent shift |
| High production costs | Restraint | Medium | Sol-gel and CVD processes carry prices up to 3x glass wool; limits adoption below 800°C applications |
| Feedstock supply crunch | Restraint | Medium | High-purity aluminosilicate availability concentrated in specialized mining regions |
The balance of evidence favors growth, but the composition of demand is shifting. Our analysis suggests that while overall volume grows at 9.06% CAGR, the RCF segment faces a structural decline in Europe and North America as substitution mandates bite. Vendors with low bio-persistent portfolios will capture disproportionate value.
The competitive landscape is moderately concentrated, with established players competing on fibre chemistry, form-factor breadth, and regional manufacturing footprint.
| Company | Headquarters | Strengths | Key Segments |
|---|---|---|---|
| Morgan Advanced Materials | UK | Broad thermal ceramics portfolio, global distribution | Industrial, transportation, aerospace |
| 3M Company | US | Ceramic fibre innovation, NASA heritage, brand trust | Aerospace, transportation, industrial |
| Unifrax (Alkegen) | US | Scale in RCF and low bio-persistent, furnace insulation | Industrial processing, petrochemical |
| IBIDEN | Japan | Precision ceramics, electronics integration | Electronics, industrial |
| Isolite Insulating Products | Japan | High-temp insulation specialization, APAC footprint | Steel, petrochemical |
| Luyang Energy-Saving Materials | China | Cost leadership, domestic scale, APAC distribution | Industrial, transportation |
Differentiation hinges on fibre chemistry and regulatory readiness. Our analysis indicates that players with proprietary low bio-persistent formulations (e.g., 3M, Unifrax) command pricing premiums in Europe and North America, while Chinese and Japanese vendors compete aggressively on scale and cost in Asia Pacific. The medium concentration reflects high barriers to entry in fibre formulation but lower barriers in converting and forming.
Selection criteria should prioritize thermal performance at target operating temperatures, regulatory compliance (particularly RCF classification in EU and North America), and supply-chain reliability. Buyers should verify fibre bio-persistency grades against local exposure limits (e.g., 0.2 fibres/cm³ in EU) and demand full material declarations. Switching costs are moderate: requalification is required for aerospace and nuclear applications, but industrial furnace retrofits can switch suppliers within 6–9 months. Procurement risk is concentrated in high-purity aluminosilicate feedstock, where supply is geographically constrained. Operators should negotiate long-term contracts with dual sourcing across RCF and low bio-persistent grades to hedge regulatory escalation.
The balance of evidence favors strategic investment in low bio-persistent fibre capacity. With RCF accounting for 55.62% of current share but facing accelerating substitution mandates in Europe and North America, the window to pivot is 2–3 years. Vendors that pre-position low bio-persistent grades will capture margin expansion as compliance costs cascade through the value chain.
The strongest counter-argument is that RCF remains cost-effective for high-temperature industrial applications where exposure controls are manageable, and that substitution will be slower than regulators intend, particularly in Asia Pacific where enforcement is less stringent. This has merit, but our analysis suggests it underweights the pace of EU substitution assessments and the growing preference of multinational buyers for globally compliant supply chains.
Actionable Strategy:
What evidence would change our conclusion: A reversal or delay in EU RCF substitution mandates, or a step-change in RCF encapsulation technology that eliminates exposure risk, would sustain RCF demand and reduce the urgency of portfolio transition.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.06% from 2020-2034 |
| Segmentation |
|
The global ceramic textile market is valued at $189.67 million in 2025, projected to reach $413.98 million by 2034 at a 9.06% CAGR, driven by high-temperature industrial insulation demand.
Asia Pacific leads with 41.84% of global revenue in 2025, driven by steel, petrochemical, and electronics manufacturing expansion in China, India, and Japan.
High-temperature insulation demand, energy-efficiency regulations, battery gigafactory thermal management, and superior weight-to-performance characteristics in aerospace and automotive are primary drivers.
Key vendors include 3M, Morgan Advanced Materials, Unifrax (Alkegen), IBIDEN, Isolite Insulating Products, Luyang Energy-Saving Materials, Rath-Group, and Zircar Zirconia.
RCF carcinogenicity classification, high production costs relative to glass wool, and feedstock supply constraints are the primary restraints, particularly in price-sensitive markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted 48 in-depth interviews across the value chain, including raw material suppliers, specialized fibre producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews focused on capacity utilization, pricing dynamics, regulatory compliance pathways, and substitution timelines for refractory ceramic fibre.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Compliance Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Fibre Producers | 40% |
| Contract Formulators & Converters | 35% |
| Global Distributors & Traders | 25% |
We validated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ISO and ASTM. All secondary data was cross-referenced for consistency and adjusted for scope differences where necessary.
We employed simultaneous top-down and bottom-up triangulation. Top-down modeling allocated macroeconomic and industry segment data to ceramic textile consumption by end-use. Bottom-up modeling aggregated manufacturer capacity, product pricing, and end-use consumption data. The two approaches were reconciled to produce a single consensus market size and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2034 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
