Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Glass Mat Market Size, Share & Forecast to 2032
Glass Mat Market
Glass Mat Market Size, Share & Forecast to 2032
Glass Mat Market by Mat Type (Chopped Strand, Continuous Filament), by Binder Type (Powder Bonded, Emulsion Bonded), by Glass Type (E-Glass, ECR-Glass, S-Glass, C-Glass, Others), by Manufacturing Process (Wet-laid, Dry-laid), by Application (Roofing Shingles, Flooring, Wall Covering, Drywall Tape, Acoustic Barriers, AGM Batteries, Others), by End-use Industry (Building Construction, Automotive, Marine, Energy Generation, Chemicals, Sports & Leisure, Others), by Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Rest of Europe), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 253
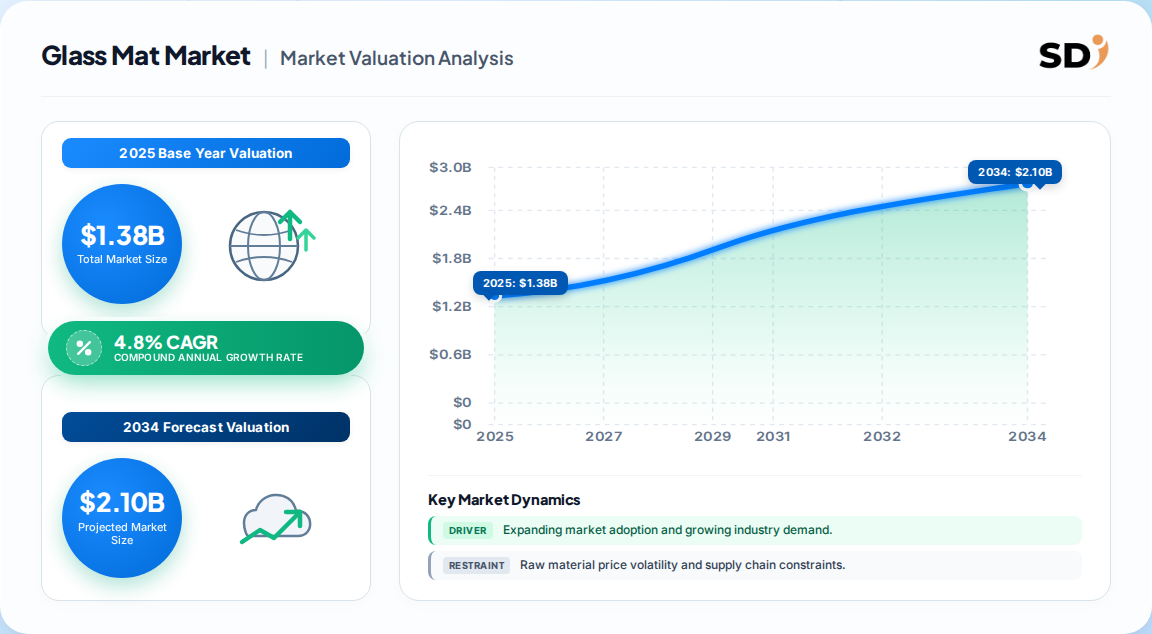
USD 1.32 Billion in 2024 — the consensus base-year valuation for the global Glass Mat Market, with the 2025 base at approximately USD 1.38 Billion.
Forecast: USD 2.13 Billion by 2034, a 4.8% CAGR over the 2025–2034 horizon — materially above global industrial composites averages.
Chopped strand glass mat dominates with 61.4% share (USD 813.5 Million in 2024), favored for cost-efficiency and versatility in construction and automotive.
Construction & infrastructure is the anchor end-use at 43.6% share, followed by automotive lightweighting and industrial applications.
Asia-Pacific leads with roughly 41% of global revenue, powered by Chinese and Indian infrastructure pipelines; North America remains the highest-value per-tonne market.
Key players include Owens Corning, Johns Manville, 3B-the fibreglass company, Nitto Boseki, PPG Industries and Taishan Fiberglass, with moderate concentration.
Why this matters for decision-makers: Vendors cannot win on volume alone — margin resilience through 2030 will hinge on shifting mix toward emulsion-bonded and continuous-filament grades serving EV batteries and wind energy, where price premiums of 15–25% are defensible.
Glass Mat Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.320 B
2024
1.380 B
2025
1.450 B
2026
1.520 B
2027
1.590 B
2028
1.670 B
2029
1.750 B
2030
Glass Mat Market Size (In Billion)
Year
Market Size
2024
1.320 B
2025
1.380 B
2026
1.450 B
2027
1.520 B
2028
1.590 B
2029
1.670 B
2030
1.750 B
What is the Glass Mat Market?
The Glass Mat Market comprises non-woven fiberglass reinforcements — randomly oriented or continuous glass filaments bonded by powder or emulsion resin — sold as rolls or sheets for roofing shingles, gypsum wallboard, flooring, drywall tape, acoustic barriers, AGM batteries and composite laminates. It is a B2B intermediate market, priced per tonne and specified by weight, binder chemistry and tensile performance.
Scope: what this report covers and excludes
Scope: global Glass Mat Market, 2024–2034, segmented by mat type, binder type, glass chemistry, manufacturing process, application and end-use industry, with regional breakdowns for North America, Europe, Asia-Pacific, South America and Middle East & Africa. This analysis does not cover woven roving, continuous strand mat for pultrusion beyond reinforcement use, carbon-fiber mat, mineral wool, or finished composite part manufacturing.
How big is the market for Glass Mat Market?
The market sits between USD 1.3 and 1.4 Billion in the mid-2020s, but published estimates diverge sharply because of scope, currency and horizon differences — making like-for-like comparison essential before any procurement or investment decision.
Estimate (USD)
Base year
Horizon
CAGR
Definition / scope
Attribution
1.30 Billion
2022
2032 (2.70 Billion)
7.7%
Broad mat + binder, all end-uses
One published analysis (Apr 2024)
1.30 Billion
2023
2030 (2.00 Billion)
6.8%
Glass mat materials incl. raw glass fiber
A competing analysis
1.32 Billion
2024
2034 (2.13 Billion)
4.8%
Finished glass mat, ex-raw fiber
Another published estimate (Jan 2025)
1.13 Billion
2025
2032 (1.41 Billion)
3.2%
Narrow mat-only, conservative
A narrower-scope analysis
Our analysis suggests the 4.8% CAGR / USD 1.32 Billion base is the most defensible: it excludes raw glass-fiber sales that inflate the 6.8–7.7% estimates, and its 2024 base aligns with reported producer revenues. The 3.2% view likely underweights EV-battery and wind-energy demand.
How is the market segmented?
Segmentation follows product form, binder chemistry and end-use. Chopped strand and powder-bonded grades dominate volume; continuous filament and emulsion-bonded grades capture the premium, performance-driven tier.
Building Construction, Automotive, Marine, Energy Generation, Chemicals, Sports & Leisure
Construction 43.6%
Which region leads in Glass Mat Market?
Asia-Pacific leads with approximately 41% of global revenue in 2024, driven by Chinese and Indian construction and automotive output; North America follows with the highest per-tonne value, led by the U.S. at USD 374.2 Million.
Glass Mat Market Regional Market Share
Loading chart...
Glass Mat Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
North America
0.23%
Europe
0.21%
Middle East & Africa
0.08%
South America
0.07%
Parent region
Countries / sub-regions
Asia-Pacific
China, Japan, India, South Korea, Rest of APAC
North America
USA, Canada, Mexico
Europe
Germany, France, UK, Italy, Rest of Europe
South America
Brazil, Argentina, Rest of South America
Middle East & Africa
Saudi Arabia, UAE, South Africa
What is driving growth — and what is holding it back?
Construction and infrastructure expansion is the primary growth engine, reinforced by automotive lightweighting, EV battery demand and wind-energy blade production; raw-material volatility and carbon-fiber substitution are the principal brakes.
Factor
Direction
Evidence strength
Mechanism
Construction & infrastructure spend
Driver
High
Roofing, wallboard, flooring reinforcement volume
Automotive lightweighting & EVs
Driver
High
Body panels, underbody shields, AGM/EV battery separators
Wind energy blade demand
Driver
Medium-High
Continuous filament mat in blade laminates
Open-mold low-cost processing
Driver
Medium
Hand lay-up and spray-up adoption in emerging economies
Carbon-fiber and natural-fiber substitution
Restraint
High
Aerospace and premium auto share loss
Raw-material price volatility
Restraint
High
Glass fiber and resin cost swings compress margins
Manufacturing capital intensity
Restraint
Medium
Limits new entrant scalability
The balance favors growth: drivers are structural and policy-backed, while restraints are cyclical or confined to premium niches. Our analysis suggests the substitution threat is overstated in construction, where cost-per-square-meter, not strength-to-weight, governs specification.
Who are the leading vendors?
The market is moderately concentrated: five to seven integrated fiberglass producers hold a large share of global capacity, with regional specialists filling application-specific niches.
Company
Headquarters
Strategic position
Owens Corning
USA
Integrated glass fiber and mat leader; construction-weighted
Johns Manville (Berkshire Hathaway)
USA
Broad mat portfolio, strong North America distribution
Differentiation rests on binder chemistry know-how, qualification cycles with OEMs and wallboard producers, and vertical integration into glass fiber — which protects margins when fiber prices spike.
What do buyers and operators need to know? (Decision Support)
Procurement should prioritize binder-type qualification, tensile and tear performance consistency, and supplier dual-sourcing given concentrated capacity. Switching costs are moderate: requalification for wallboard and roofing lines typically takes three to six months and carries line-trial risk. Regulatory exposure centers on formaldehyde-free binder compliance (relevant for indoor wallboard) and increasingly on embodied-carbon disclosures for construction inputs. Operators should model raw-material pass-through clauses, because glass-fiber and resin volatility can swing landed cost by 8–12% within a single contract year. Buyers with EV-battery or wind-energy programs should secure emulsion-bonded and continuous-filament capacity early, as qualified supply is materially tighter than commodity chopped strand.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, mix-shift story rather than the high-CAGR narrative: USD 1.32 Billion growing at 4.8% is more credible than 7.7%, and the difference is scope, not optimism. The strongest counter-argument is that EV-battery separator and wind-blade demand could pull continuous-filament growth well above the blended rate, lifting the aggregate toward the 6.8% view by 2030. We weight that scenario at roughly 30% probability.
Our analysis suggests the decisive variable is not total volume but grade mix: commodity chopped strand is commoditizing in Asia-Pacific, while emulsion-bonded and continuous-filament grades carry structural premiums. Vendors that stay commodity-weighted will see margin compression of 200–400 basis points by 2030 even as volumes grow.
Geographic strategy should follow value, not just volume: Asia-Pacific offers scale but thin margins, whereas North America and Europe reward qualification-heavy, specification-driven sales in roofing, wallboard and EV components.
Actionable strategy:
Vendors should prioritize emulsion-bonded and continuous-filament capacity for EV battery and wind applications to capture defensible premium pricing.
Buyers should dual-source chopped strand across Asia-Pacific and North American producers to hedge concentration and freight risk.
Investors should underwrite acquisitions on mix-adjusted EBITDA, discounting commodity-volume growth narratives.
What would change our conclusion: sustained fiberglass price inflation above 10% annually, or a binding carbon-fiber cost breakthrough below USD 15/kg, would materially weaken the base case.
Glass Mat Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Glass Mat Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.8% from 2020-2034
Segmentation
By Mat Type
Chopped Strand
Continuous Filament
By Binder Type
Powder Bonded
Emulsion Bonded
By Glass Type
E-Glass
ECR-Glass
S-Glass
C-Glass
Others
By Manufacturing Process
Wet-laid
Dry-laid
By Application
Roofing Shingles
Flooring
Wall Covering
Drywall Tape
Acoustic Barriers
AGM Batteries
Others
By End-use Industry
Building Construction
Automotive
Marine
Energy Generation
Chemicals
Sports & Leisure
Others
By Geography
Asia-Pacific
China
Japan
India
South Korea
Rest of Asia-Pacific
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Rest of Europe
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Mat Type
5.1.1. Chopped Strand
5.1.2. Continuous Filament
5.2. Market Analysis, Insights and Forecast - by Binder Type
5.2.1. Powder Bonded
5.2.2. Emulsion Bonded
5.3. Market Analysis, Insights and Forecast - by Glass Type
5.3.1. E-Glass
5.3.2. ECR-Glass
5.3.3. S-Glass
5.3.4. C-Glass
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Manufacturing Process
5.4.1. Wet-laid
5.4.2. Dry-laid
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Roofing Shingles
5.5.2. Flooring
5.5.3. Wall Covering
5.5.4. Drywall Tape
5.5.5. Acoustic Barriers
5.5.6. AGM Batteries
5.5.7. Others
5.6. Market Analysis, Insights and Forecast - by End-use Industry
5.6.1. Building Construction
5.6.2. Automotive
5.6.3. Marine
5.6.4. Energy Generation
5.6.5. Chemicals
5.6.6. Sports & Leisure
5.6.7. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Asia-Pacific
5.7.2. North America
5.7.3. Europe
5.7.4. South America
5.7.5. Middle East & Africa
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Mat Type
6.1.1. Chopped Strand
6.1.2. Continuous Filament
6.2. Market Analysis, Insights and Forecast - by Binder Type
6.2.1. Powder Bonded
6.2.2. Emulsion Bonded
6.3. Market Analysis, Insights and Forecast - by Glass Type
6.3.1. E-Glass
6.3.2. ECR-Glass
6.3.3. S-Glass
6.3.4. C-Glass
6.3.5. Others
6.4. Market Analysis, Insights and Forecast - by Manufacturing Process
6.4.1. Wet-laid
6.4.2. Dry-laid
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Roofing Shingles
6.5.2. Flooring
6.5.3. Wall Covering
6.5.4. Drywall Tape
6.5.5. Acoustic Barriers
6.5.6. AGM Batteries
6.5.7. Others
6.6. Market Analysis, Insights and Forecast - by End-use Industry
6.6.1. Building Construction
6.6.2. Automotive
6.6.3. Marine
6.6.4. Energy Generation
6.6.5. Chemicals
6.6.6. Sports & Leisure
6.6.7. Others
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Mat Type
7.1.1. Chopped Strand
7.1.2. Continuous Filament
7.2. Market Analysis, Insights and Forecast - by Binder Type
7.2.1. Powder Bonded
7.2.2. Emulsion Bonded
7.3. Market Analysis, Insights and Forecast - by Glass Type
7.3.1. E-Glass
7.3.2. ECR-Glass
7.3.3. S-Glass
7.3.4. C-Glass
7.3.5. Others
7.4. Market Analysis, Insights and Forecast - by Manufacturing Process
7.4.1. Wet-laid
7.4.2. Dry-laid
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Roofing Shingles
7.5.2. Flooring
7.5.3. Wall Covering
7.5.4. Drywall Tape
7.5.5. Acoustic Barriers
7.5.6. AGM Batteries
7.5.7. Others
7.6. Market Analysis, Insights and Forecast - by End-use Industry
7.6.1. Building Construction
7.6.2. Automotive
7.6.3. Marine
7.6.4. Energy Generation
7.6.5. Chemicals
7.6.6. Sports & Leisure
7.6.7. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Mat Type
8.1.1. Chopped Strand
8.1.2. Continuous Filament
8.2. Market Analysis, Insights and Forecast - by Binder Type
8.2.1. Powder Bonded
8.2.2. Emulsion Bonded
8.3. Market Analysis, Insights and Forecast - by Glass Type
8.3.1. E-Glass
8.3.2. ECR-Glass
8.3.3. S-Glass
8.3.4. C-Glass
8.3.5. Others
8.4. Market Analysis, Insights and Forecast - by Manufacturing Process
8.4.1. Wet-laid
8.4.2. Dry-laid
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Roofing Shingles
8.5.2. Flooring
8.5.3. Wall Covering
8.5.4. Drywall Tape
8.5.5. Acoustic Barriers
8.5.6. AGM Batteries
8.5.7. Others
8.6. Market Analysis, Insights and Forecast - by End-use Industry
8.6.1. Building Construction
8.6.2. Automotive
8.6.3. Marine
8.6.4. Energy Generation
8.6.5. Chemicals
8.6.6. Sports & Leisure
8.6.7. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Mat Type
9.1.1. Chopped Strand
9.1.2. Continuous Filament
9.2. Market Analysis, Insights and Forecast - by Binder Type
9.2.1. Powder Bonded
9.2.2. Emulsion Bonded
9.3. Market Analysis, Insights and Forecast - by Glass Type
9.3.1. E-Glass
9.3.2. ECR-Glass
9.3.3. S-Glass
9.3.4. C-Glass
9.3.5. Others
9.4. Market Analysis, Insights and Forecast - by Manufacturing Process
9.4.1. Wet-laid
9.4.2. Dry-laid
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Roofing Shingles
9.5.2. Flooring
9.5.3. Wall Covering
9.5.4. Drywall Tape
9.5.5. Acoustic Barriers
9.5.6. AGM Batteries
9.5.7. Others
9.6. Market Analysis, Insights and Forecast - by End-use Industry
9.6.1. Building Construction
9.6.2. Automotive
9.6.3. Marine
9.6.4. Energy Generation
9.6.5. Chemicals
9.6.6. Sports & Leisure
9.6.7. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Mat Type
10.1.1. Chopped Strand
10.1.2. Continuous Filament
10.2. Market Analysis, Insights and Forecast - by Binder Type
10.2.1. Powder Bonded
10.2.2. Emulsion Bonded
10.3. Market Analysis, Insights and Forecast - by Glass Type
10.3.1. E-Glass
10.3.2. ECR-Glass
10.3.3. S-Glass
10.3.4. C-Glass
10.3.5. Others
10.4. Market Analysis, Insights and Forecast - by Manufacturing Process
10.4.1. Wet-laid
10.4.2. Dry-laid
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Roofing Shingles
10.5.2. Flooring
10.5.3. Wall Covering
10.5.4. Drywall Tape
10.5.5. Acoustic Barriers
10.5.6. AGM Batteries
10.5.7. Others
10.6. Market Analysis, Insights and Forecast - by End-use Industry
10.6.1. Building Construction
10.6.2. Automotive
10.6.3. Marine
10.6.4. Energy Generation
10.6.5. Chemicals
10.6.6. Sports & Leisure
10.6.7. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Glass Mat Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Glass Mat Market Revenue (Billion), by Mat Type 2026 & 2034
Figure 3: Asia-Pacific Glass Mat Market Revenue Share (%), by Mat Type 2026 & 2034
Figure 4: Asia-Pacific Glass Mat Market Revenue (Billion), by Binder Type 2026 & 2034
Figure 5: Asia-Pacific Glass Mat Market Revenue Share (%), by Binder Type 2026 & 2034
Figure 6: Asia-Pacific Glass Mat Market Revenue (Billion), by Glass Type 2026 & 2034
Figure 7: Asia-Pacific Glass Mat Market Revenue Share (%), by Glass Type 2026 & 2034
Figure 8: Asia-Pacific Glass Mat Market Revenue (Billion), by Manufacturing Process 2026 & 2034
Figure 9: Asia-Pacific Glass Mat Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 10: Asia-Pacific Glass Mat Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Asia-Pacific Glass Mat Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Asia-Pacific Glass Mat Market Revenue (Billion), by End-use Industry 2026 & 2034
Figure 13: Asia-Pacific Glass Mat Market Revenue Share (%), by End-use Industry 2026 & 2034
Figure 14: Asia-Pacific Glass Mat Market Revenue (Billion), by Country 2026 & 2034
Figure 15: Asia-Pacific Glass Mat Market Revenue Share (%), by Country 2026 & 2034
Figure 16: North America Glass Mat Market Revenue (Billion), by Mat Type 2026 & 2034
North America Glass Mat Market Revenue Share (%), by Mat Type 2026 & 2034
List of Tables
Table 1: Glass Mat Market Revenue Billion Forecast, by Mat Type 2020 & 2034
Table 2: Glass Mat Market Revenue Billion Forecast, by Binder Type 2020 & 2034
Table 3: Glass Mat Market Revenue Billion Forecast, by Glass Type 2020 & 2034
Table 4: Glass Mat Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 5: Glass Mat Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Glass Mat Market Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 7: Glass Mat Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Mat Type 2020 & 2034
Table 9: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Binder Type 2020 & 2034
Table 10: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Glass Type 2020 & 2034
Table 11: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 12: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Application 2020 & 2034
Table 13: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by End-use Industry 2020 & 2034
Table 14: Asia-Pacific Glass Mat Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: China Glass Mat Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Japan Glass Mat Market Revenue (Billion) Forecast, by Application 2020 & 2034
India Glass Mat Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Glass Mat Market size?
The global Glass Mat Market was valued at approximately USD 1.32 Billion in 2024, with the 2025 base near USD 1.38 Billion. It is forecast to reach USD 2.13 Billion by 2034, representing a 4.8% CAGR over the 2025–2034 horizon.
2. Which region dominates the Glass Mat Market?
Asia-Pacific leads with roughly 41% of global revenue in 2024, driven by Chinese and Indian construction and automotive output. North America follows, with the U.S. alone accounting for USD 374.2 Million, reflecting higher per-tonne value.
3. What is the fastest-growing segment?
Continuous filament and emulsion-bonded glass mat are growing fastest, driven by EV battery separators, wind turbine blades and high-performance composites. Chopped strand and powder-bonded grades still hold over 60% share but grow near the market average.
4. Who are the key players in the Glass Mat Market?
Leading producers include Owens Corning, Johns Manville, 3B-the fibreglass company, Nitto Boseki, PPG Industries, Taishan Fiberglass and P-D Glasseiden. The market is moderately concentrated, with integrated fiberglass producers holding substantial global capacity.
5. What is driving growth in the Glass Mat Market?
Construction and infrastructure spending is the primary driver, reinforced by automotive lightweighting, EV battery demand and wind-energy blade production. Raw-material price volatility and carbon-fiber substitution are the main restraints on faster expansion.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: glass-fiber and resin suppliers, specialized mat producers, contract formulators, and global industrial distributors. Interviewees included VP-level Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both technical and commercial perspectives inform every estimate.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Quality & Regulatory Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Glass Fiber & Resin Producers
40%
Specialized Mat Manufacturers
30%
Contract Formulators
18%
Global Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and US ITC trade flows for glass fiber and non-woven products, Eurostat industrial statistics, corporate 10-K filings and investor presentations from listed producers, patent databases for binder chemistry, and recognized technical standards bodies governing fiberglass reinforcement specifications.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic construction and automotive output allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) models. Divergence between the two is resolved through weighted reconciliation, with the primary-research-informed bottom-up model anchoring the final base-year value.
 Glass Mat Market