 Natural Fiber Composites Market
 Outlook 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 197

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Natural Fiber Composites Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 10.60 B |
| 2026 | 11.80 B |
| 2027 | 13.20 B |
| 2028 | 14.80 B |
| 2029 | 16.60 B |
| 2030 | 18.60 B |
| 2031 | 20.90 B |

The natural fiber composites market covers engineered materials that bind plant-derived fibers — wood, flax, hemp, jute, kenaf, sisal, cotton or bamboo — in a polymer or inorganic matrix to form structural and semi-structural parts. Products serve automotive interiors, decking, panels, packaging and consumer goods as lower-carbon substitutes for glass-fiber composites.
This analysis covers fiber supply, matrix chemistry, processing technology, application demand and regional trade for plant-fiber-reinforced composites in the Global market. Coverage spans wood-plastic and natural-fiber composite formulations sold as finished compounds, profiles and molded parts. This analysis does not cover glass-fiber or carbon-fiber composites, virgin polymer resin markets, pulp and paper production, or biomass energy feedstocks except where they directly price-shift composite inputs.
Estimates diverge by more than an order of magnitude because publishers disagree on whether wood-plastic decking counts. The most defensible planning figure depends on whether your procurement sits in building products or engineered automotive parts.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 10.6 Billion | 2025 | 2033 | 12.1% | Broad: includes wood-plastic decking, panels and profiles | One published estimate |
| USD 26.3 Billion | 2033 | 2033 | 12.1% | Same broad perimeter as above | Same publisher, forecast year |
| USD 328 Million | 2024 | 2034 | 5.4% | Narrow: engineered natural-fiber composites, excludes most wood-plastic | A competing analysis |
| USD 360 Million | 2025 | 2034 | 5.3% | Narrow: composite parts, automotive-weighted | A competing analysis |
Our analysis suggests the broad figure is the correct addressable pool for suppliers selling into decking, railing and panel channels, while the narrow figure better describes the engineered-parts trade that automotive tier suppliers actually bid on. The 5.3–5.4% and 12.1% CAGR gap is not a forecast disagreement so much as a perimeter disagreement: wood-plastic decking is a mature, low-single-digit business, whereas natural-fiber automotive components are compounding from a small base.
The implication: a buyer sizing a flax or hemp composite line should use the narrow series; a buyer sizing a wood-plastic extrusion line should use the broad one. Mixing them overstates growth by roughly six percentage points.
Raw material and matrix segmentation reveals where value concentrates; wood fibers and inorganic or synthetic matrices dominate volume while injection and compression molding dominate conversion.
| Parent segment | Children | Share signal |
|---|---|---|
| By Raw Material | Wood, Cotton, Flax, Kenaf, Hemp, Jute, Sisal, Bamboo, Others | Wood ~58% (broad scope); flax leads engineered parts |
| By Matrix | Inorganic Compound, Natural Polymer, Synthetic Polymer | Inorganic ~42% (broad); synthetic polymer ~59% (narrow scope) |
| By Technology | Compression Molding, Injection Molding, Pultrusion, Others | Compression ~76% (broad); injection ~44% (narrow) |
| By Application | Automotive, Construction, Consumer Goods & Packaging, Aerospace, Marine, Others | Construction leads broad scope; automotive ~47% on narrow scope |
Note the directional conflict: compression molding and inorganic matrices dominate the broad perimeter, while injection molding and synthetic polymers dominate the narrow one. Our analysis suggests this reflects tooling economics — decking profiles favor compression and pultrusion, whereas interior trim favors injection at automotive volumes.
Hemp is repeatedly flagged as the fastest-growing fiber type, aided by low-input agronomy and favorable policy in Europe and Canada. Wood remains the cost floor that every alternative fiber must beat on landed price.
North America leads with roughly 44% of global revenue, supported by a mature wood-plastic building-products channel and early bio-composite adoption. Europe is second and is the technology leader in flax-based automotive composites.
| Region | Market Share (%) |
|---|---|
| North America | 0.44% |
| Europe | 0.27% |
| Asia-Pacific | 0.21% |
| Latin America | 0.04% |
| Middle East & Africa | 0.04% |
| Parent region | Countries covered |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Nordics |
| Asia Pacific | China, Japan, India, South Korea, ASEAN |
| Latin America | Brazil, Argentina, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Asia Pacific is the fastest-compounding region at roughly 13.9% annually, driven by Chinese automotive production and construction activity. Europe's position is more nuanced than headline share implies: European OEM specification of flax-reinforced interior panels gives the region disproportionate influence over material standards, even where revenue is booked elsewhere. The competing analysis places Europe first on the narrow perimeter — a reversal that confirms the perimeter issue rather than contradicting it.
Sustainability mandates and lightweighting targets are the dominant demand pull, while mechanical-performance gaps versus glass fiber cap penetration into structural applications.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Sustainability and decarbonization mandates | Driver | Strong | Specification pressure in automotive and construction procurement |
| Lightweighting and EV range economics | Driver | Strong | Lower density reduces mass and emissions compliance cost |
| Cost advantage versus glass fiber | Driver | Moderate | Fiber input cost lower; processing offsets vary |
| Bio-resin and fiber-treatment innovation | Driver | Moderate | Widens performance envelope for moisture and bonding |
| Moisture sensitivity and durability limits | Restraint | Strong | Excludes exterior structural and high-load uses |
| Fiber quality variability | Restraint | Strong | Raises scrap rates and complicates certification |
| Limited large-scale processing infrastructure | Restraint | Moderate | Constrains supply response to large contracts |
| Competition from low-cost synthetic composites | Restraint | Strong | Caps price premium in performance-led segments |
Our analysis suggests the balance is tipping: fiber-treatment and bio-resin advances are steadily eroding the performance restraint, but quality consistency — not mechanical ceiling — is now the binding constraint. That reframes the investment case from material science toward agricultural supply-chain control.
The competitive field is moderately concentrated, with a handful of scaled players in wood-plastic and thermoplastic composites and a fragmented tail of fiber specialists.
| Company | Positioning | Perceived moat |
|---|---|---|
| FlexForm | Thermoplastic natural-fiber composites | Automotive qualification record |
| UPM | Bio-based materials and wood fiber | Feedstock integration and scale |
| TECNARO | Bio-plastic compounds | Formulation IP and brand |
| Trex | Wood-plastic decking | Distribution and consumer brand |
Differentiation rests on three axes: fiber supply control, OEM qualification status, and processing know-how for moisture management. Our analysis suggests qualification status is the stickiest moat, because automotive interior approval cycles run multiple years and switching suppliers mid-program is rarely economic. Brand-led decking players compete on warranty duration instead, which transfers risk to the manufacturer.
Purchasing natural fiber composites requires qualifying on moisture performance, fiber consistency and process compatibility simultaneously, since a failure in any one offsets the sustainability benefit. Buyers should demand lot-level moisture content data, fiber-origin traceability and a documented treatment method before approving a supplier.
Switching costs are asymmetric. Moving from glass fiber to natural fiber requires re-tooling, re-validation and often re-certification, so the first program is expensive and subsequent ones are far cheaper. This argues for negotiating multi-program framework agreements at the point of first adoption.
Regulatory compliance is a live risk: bio-based content claims are increasingly audited, and end-of-life recyclability claims must survive scrutiny in European procurement. Operators should also stress-test for seasonal fiber availability, since harvest cycles create working-capital swings that synthetic supply chains do not.
The balance of evidence favors the narrow, engineered-composites perimeter as the genuine growth story, even though the broad estimate is the more widely quoted number. A 12.1% CAGR applied to decking-inclusive revenue strains credibility against the maturity of that channel; our judgment is that the 5–6% band better describes the addressable engineered-parts trade, with pockets of double-digit growth in automotive interiors.
The strongest counter-argument is that sustainability regulation could unlock step-change volume in construction — wall panels, insulation and siding — where the broad perimeter would then compound faster than history implies. If binding carbon-content rules land in European and North American building codes, the high-CAGR case becomes defensible.
What would change our conclusion: a verified, audited dataset showing compression-molded construction volumes compounding above 10% annually, or a major OEM platform award specifying natural-fiber structural (not interior) components.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
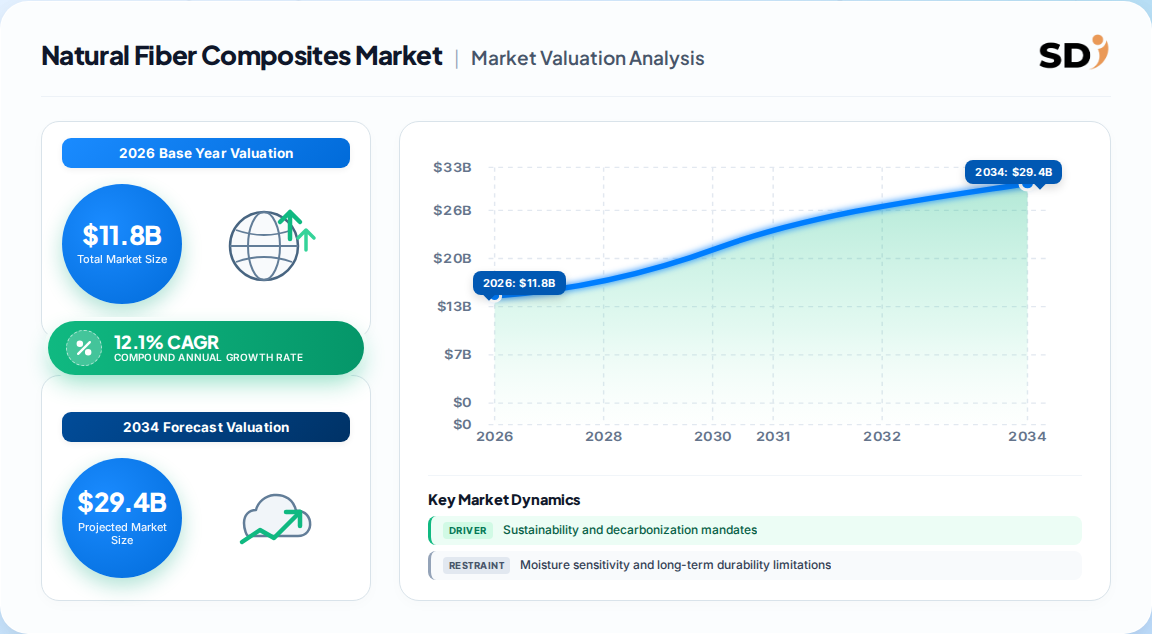
| Growth Rate | CAGR of 12.1% from 2020-2034 |
| Segmentation |
|
The global natural fiber composites market is estimated at USD 11.8 billion in 2026 on a broad perimeter that includes wood-plastic products. A narrower engineered-composites definition places the same year near USD 383 million, so scope must be fixed before comparing figures.
Published growth rates range from roughly 5.3% to 12.1% annually to the early 2030s. The spread reflects definitional perimeter differences rather than forecast disagreement, with engineered automotive parts growing faster than mature wood-plastic decking.
North America holds the largest revenue share, around 44%, on the strength of its wood-plastic building-products channel. Europe leads on engineered automotive composites, and Asia Pacific is the fastest-growing region at nearly 14% annually.
Wood fiber dominates broadly at roughly 58% of raw material share, driven by decking and panel applications. Flax leads engineered automotive parts, while hemp is the fastest-growing fiber type on low-input agronomy and supportive policy.
Moisture sensitivity, fiber quality variability and long-term durability concerns restrict use in structural and exterior applications. Limited large-scale processing infrastructure and competition from low-cost glass fiber further constrain penetration into high-performance segments.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program maintains a deliberate 70/30 primary-to-secondary split, prioritizing direct validation over desk aggregation. Fieldwork comprises in-depth interviews with stakeholders across the natural fiber composites value chain, including natural fiber growers and processors, compound formulators, molded-parts manufacturers, and global distributors serving automotive and construction channels. Interviews target decision-makers holding direct specification or purchasing authority — VP-level sourcing executives, heads of materials R&D, technical directors responsible for qualification, and commercial operations leads managing multi-region supply. This structure ensures demand signals are validated by the parties who actually commit capital and approve specifications.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Natural Fiber Growers & Processors | 30% |
| Compound Formulators | 35% |
| Molded Parts Manufacturers | 25% |
| Distributors & Traders | 10% |
Secondary validation draws on multilateral trade databases including UN Comtrade and Eurostat for fiber and composite flow analysis, national customs and statistics agencies, corporate annual filings and investor presentations, patent landscapes covering fiber treatment and bio-resin formulation, and technical standards published by recognized industry associations. Every quantitative benchmark is cross-checked against at least two independent public sources before entering the model.
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic output across end-use segments and applies substitution ratios for natural versus synthetic composites. The bottom-up model builds from manufacturer capacity, realized pricing and end-use consumption volumes. Divergence between the two is investigated at segment level rather than averaged away, which is how perimeter differences between estimates are identified and resolved.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |