Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Barrier Systems Market Size, CAGR & Forecast to 2035
Barrier Systems Market
Barrier Systems Market Size, CAGR & Forecast to 2035
Barrier Systems Market by Product Type (Bollards, Fences, Crash Barrier Systems, Crash Barrier Devices, Drop Arms, Others), by Material (Metal, Plastic, Concrete, Wood, Others), by Technology (Rigid, Semi-Rigid, Flexible), by Function (Passive Barriers, Active Barriers), by Application (Roadways, Railways, Commercial, Residential, Industrial, Military & Defense), by Access Control (Token & Reader, Biometric Systems, Turnstiles, Perimeter Security & Alarms), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 279
Khageshwar Rongkali
Senior Analyst
Key Takeaways
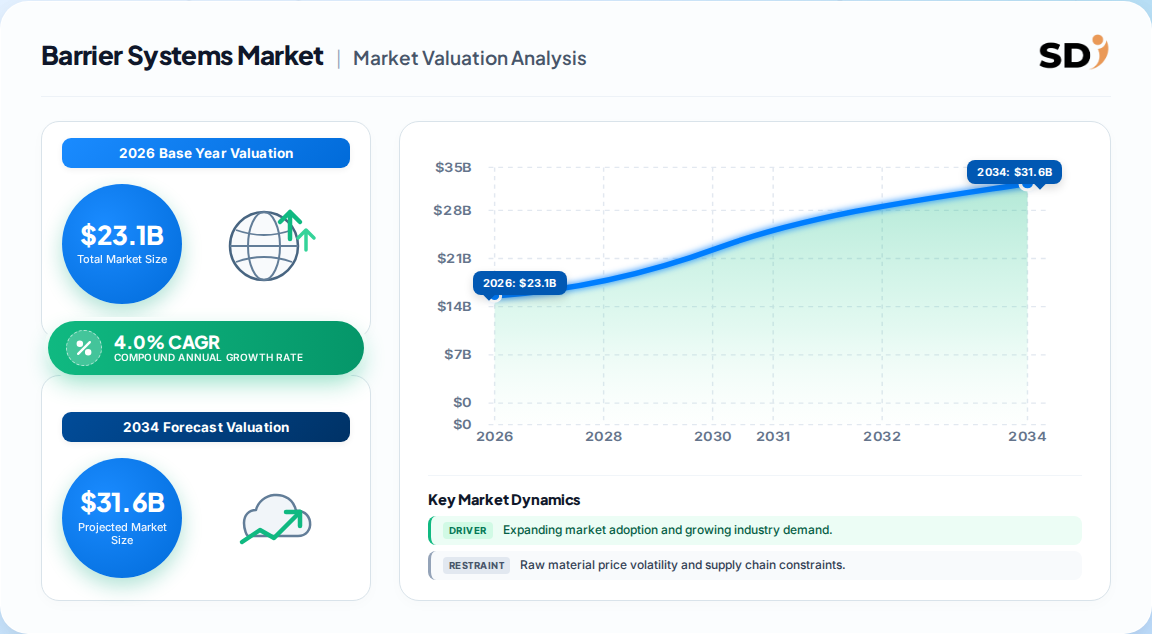
The global barrier systems market was valued at USD 23.1 billion in 2026 and is forecast to reach USD 33.0 billion by 2035, expanding at a 4.0% CAGR, according to one consolidated published estimate.
Crash barrier systems remain the largest product segment, capturing roughly 35.6% of 2024 revenue, driven by recurring highway safety replacement cycles across national road networks.
Asia Pacific holds the largest regional share at approximately 34%, while the Middle East & Africa is the fastest-growing region, supported by GCC-hosted event and critical-infrastructure security programs.
The top five vendors—Valtir, Hill & Smith, Lindsay, Forterra and Nippon Steel Metal Products—collectively hold only about 5.5% share, signaling a highly fragmented, tender-driven competitive field.
Hostile vehicle mitigation (HVM) specifications, anchored by ISO 22343-1:2023, ASTM F2656 and IWA 14-1, are expanding demand beyond conventional roadside hardware into rated bollards and automated access barriers.
Why this matters for decision-makers: The market's 4% baseline growth masks a bifurcation—commodity guardrail demand tracks flat public budgets, while certified HVM and smart-access systems command premium margins; vendors that delay certification investment risk structural margin compression.
Barrier Systems Market Size (In Billion)
30.0B
20.0B
10.0B
0
22.00 B
2025
23.10 B
2026
24.00 B
2027
25.00 B
2028
26.00 B
2029
27.00 B
2030
28.10 B
2031
Barrier Systems Market Size (In Billion)
Year
Market Size
2025
22.00 B
2026
23.10 B
2027
24.00 B
2028
25.00 B
2029
26.00 B
2030
27.00 B
2031
28.10 B
What is the Barrier Systems Market?
The barrier systems market encompasses physical products—guardrails, crash attenuators, bollards, fences, drop arms and automated gates—designed to redirect vehicles, control access and protect people and assets. It spans passive roadside safety hardware, perimeter security and integrated access-control systems deployed across highways, transport nodes, industrial sites and public venues.
Scope: what this report covers and excludes
This analysis covers the global barrier systems market across product type, material, technology, function and end-use, with a base year of 2025 and forecast horizon to 2035. This analysis does not cover adjacent markets such as standalone video surveillance, physical access-control software, or general construction fencing, except where integrated into barrier procurement.
How big is the market for Barrier Systems Market?
Published estimates for the barrier systems market diverge sharply—CAGRs range from 3.5% to 10.3%—reflecting inconsistent scope definitions rather than genuine demand disagreement. The most defensible baseline anchors global crash-barrier and perimeter-hardware revenue near USD 23 billion in 2025–2026.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 22.0 B → 33.0 B
2025
2035
4.0%
Road safety hardware plus perimeter/access barriers
One published estimate (GMI)
USD 22.99 B → 50.38 B
2024
2032
10.30%
Broad barrier systems incl. fences, turnstiles, access control
Competing analysis (Data Bridge)
USD 39.23 B by 2034
2026
2034
5.8%
Passive and active barriers, multi-end-use
Competing analysis (Polaris)
USD 2.6 B → 4.4 B
2025
2033
6.8%
Industrial barriers only (guardrails, bollards, safety fences)
Competing analysis (Grand View)
Our analysis suggests the 4.0% figure is most defensible for the core road-safety hardware market, because it aligns with demonstrated public capital allocation and replacement-cycle mechanics. The 10.3% figure likely folds access-control electronics and perimeter fencing into scope, inflating the growth rate.
The industrial barrier sub-segment, at USD 2.6 billion, is a distinct opportunity: its 6.8% CAGR reflects warehouse automation and machinery-safeguarding demand, not highway procurement.
How is the market segmented?
Segmentation follows product, material, technology, function and application. Crash barrier systems dominate revenue, while active access barriers grow fastest on security spending.
Crash barrier systems held 35.6% of 2024 revenue, while passive barriers accounted for over 70% of industrial installations. Active systems—drop arms, retractable bollards, swing gates—are gaining share as venues automate vehicle access.
Which region leads in Barrier Systems Market?
Asia Pacific leads the global barrier systems market with approximately 34% revenue share, driven by vehicle penetration growth, accident-reduction mandates and expansive transport infrastructure programs. North America follows at roughly 30%, with Europe at 23%.
Barrier Systems Market Regional Market Share
Loading chart...
Barrier Systems Market Regional Market Share
Region
Market Share (%)
North America
0.3%
Europe
0.23%
Asia-Pacific
0.34%
South America
0.06%
Middle East & Africa
0.07%
Global
Asia Pacific — China, Japan, India, South Korea, Indonesia, Australia
North America — United States, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Netherlands
Middle East & Africa — Saudi Arabia, UAE, South Africa, Israel
Latin America — Brazil, Argentina, Mexico
Asia Pacific's lead is volume-driven: high vehicle populations and greenfield highway construction favor low-cost rigid and semi-rigid barrier installations. North America's share is value-driven, with certified HVM and grant-funded safety programs elevating per-unit spend.
What is driving growth — and what is holding it back?
Growth is anchored by road-safety mandates—approximately 1.19 million annual road traffic deaths per WHO—and dedicated funding such as the USD 5 billion U.S. SS4A program. Restraints center on public funding shortfalls and maintenance backlogs.
Factor
Direction
Evidence strength
Mechanism
Road safety mandates
Driver
High (WHO)
Mandatory crash barrier installation and replacement
Dedicated safety funding
Driver
High (US DOT)
SS4A grants accelerate attenuator and bollard procurement
HVM certification mandates
Driver
High (NPSA)
Certified bollards, drop arms at venues and critical sites
Highway Trust Fund deficit
Restraint
High (Eno Center)
USD 21 B deficit delays secondary-network barrier spend
Maintenance backlogs
Restraint
Medium (ALARM)
USD 20.7 B England/Wales backlog prioritizes pavement
Fragmented certification
Restraint
Medium
Multiple regimes raise market-entry cost
The balance favors sustained but uneven growth. Mandates create non-discretionary demand, yet funding pressure reshapes order of execution rather than eliminating it. Procurement concentrates in grant-funded and concession-road programs, creating lumpy annual cadences.
Who are the leading vendors?
The market is highly fragmented: the top five players held just 5.5% combined share in 2025, with Valtir LLC leading at 2.7%. No single vendor exercises pricing power across the global field.
Differentiation rests on certification breadth (ISO 22343-1, ASTM F2656, PAS 68) and integration capability. Vendors that pair tested hardware with installation, access-control integration and engineering services create stickier, higher-margin positions than pure product suppliers.
What do buyers and operators need to know? (Decision Support)
Buyers must prioritize certified product performance over unit price, because HVM barriers failing independent testing expose operators to liability and retrofitting costs. Certification under ISO 22343-1:2023 or ASTM F2656 should be verified per jurisdiction, as cross-border recognition is not automatic.
Procurement risk concentrates in public funding timing: grant-dependent projects may be deferred, while concession-road programs proceed. Operators should design barrier specifications that allow phased deployment, avoiding single-vendor lock-in for access-control electronics. Switching costs rise sharply once automated barriers integrate with surveillance and access software, so integration architecture should be specified upfront. Sustainability requirements are also entering tenders, favoring vendors with lower-carbon materials and modular designs.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, bifurcating market: commodity roadside hardware grows near GDP, while certified security barriers outpace it. The 4.0% CAGR is credible for the aggregate, but averages obscure the HVM premium that vendors should chase.
The strongest counter-argument is that fragmented certification and public funding shortfalls could suppress adoption of premium rated barriers, keeping the market anchored to low-margin guardrail replacement. If infrastructure budgets tighten materially, this scenario gains weight.
Investors: Prioritize vendors with multi-jurisdiction certification portfolios and service-led revenue, not pure steel product exposure.
Operators: Lock in certification compliance early and specify open integration architecture to limit switching costs.
Vendors: Target Asia Pacific highway programs for volume and GCC/NATO HVM programs for margin.
Our conclusion would change if sustained Highway Trust Fund reform materially expanded secondary-network spending, which would lift volume growth beyond 4% across the aggregate market.
Barrier Systems Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Barrier Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.0% from 2020-2034
Segmentation
By Product Type
Bollards
Fences
Crash Barrier Systems
Crash Barrier Devices
Drop Arms
Others
By Material
Metal
Plastic
Concrete
Wood
Others
By Technology
Rigid
Semi-Rigid
Flexible
By Function
Passive Barriers
Active Barriers
By Application
Roadways
Railways
Commercial
Residential
Industrial
Military & Defense
By Access Control
Token & Reader
Biometric Systems
Turnstiles
Perimeter Security & Alarms
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Indonesia
Australia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Israel
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Bollards
5.1.2. Fences
5.1.3. Crash Barrier Systems
5.1.4. Crash Barrier Devices
5.1.5. Drop Arms
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Metal
5.2.2. Plastic
5.2.3. Concrete
5.2.4. Wood
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Rigid
5.3.2. Semi-Rigid
5.3.3. Flexible
5.4. Market Analysis, Insights and Forecast - by Function
5.4.1. Passive Barriers
5.4.2. Active Barriers
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Roadways
5.5.2. Railways
5.5.3. Commercial
5.5.4. Residential
5.5.5. Industrial
5.5.6. Military & Defense
5.6. Market Analysis, Insights and Forecast - by Access Control
5.6.1. Token & Reader
5.6.2. Biometric Systems
5.6.3. Turnstiles
5.6.4. Perimeter Security & Alarms
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Bollards
6.1.2. Fences
6.1.3. Crash Barrier Systems
6.1.4. Crash Barrier Devices
6.1.5. Drop Arms
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Metal
6.2.2. Plastic
6.2.3. Concrete
6.2.4. Wood
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Rigid
6.3.2. Semi-Rigid
6.3.3. Flexible
6.4. Market Analysis, Insights and Forecast - by Function
6.4.1. Passive Barriers
6.4.2. Active Barriers
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Roadways
6.5.2. Railways
6.5.3. Commercial
6.5.4. Residential
6.5.5. Industrial
6.5.6. Military & Defense
6.6. Market Analysis, Insights and Forecast - by Access Control
6.6.1. Token & Reader
6.6.2. Biometric Systems
6.6.3. Turnstiles
6.6.4. Perimeter Security & Alarms
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Bollards
7.1.2. Fences
7.1.3. Crash Barrier Systems
7.1.4. Crash Barrier Devices
7.1.5. Drop Arms
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Metal
7.2.2. Plastic
7.2.3. Concrete
7.2.4. Wood
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Rigid
7.3.2. Semi-Rigid
7.3.3. Flexible
7.4. Market Analysis, Insights and Forecast - by Function
7.4.1. Passive Barriers
7.4.2. Active Barriers
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Roadways
7.5.2. Railways
7.5.3. Commercial
7.5.4. Residential
7.5.5. Industrial
7.5.6. Military & Defense
7.6. Market Analysis, Insights and Forecast - by Access Control
7.6.1. Token & Reader
7.6.2. Biometric Systems
7.6.3. Turnstiles
7.6.4. Perimeter Security & Alarms
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Bollards
8.1.2. Fences
8.1.3. Crash Barrier Systems
8.1.4. Crash Barrier Devices
8.1.5. Drop Arms
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Metal
8.2.2. Plastic
8.2.3. Concrete
8.2.4. Wood
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Rigid
8.3.2. Semi-Rigid
8.3.3. Flexible
8.4. Market Analysis, Insights and Forecast - by Function
8.4.1. Passive Barriers
8.4.2. Active Barriers
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Roadways
8.5.2. Railways
8.5.3. Commercial
8.5.4. Residential
8.5.5. Industrial
8.5.6. Military & Defense
8.6. Market Analysis, Insights and Forecast - by Access Control
8.6.1. Token & Reader
8.6.2. Biometric Systems
8.6.3. Turnstiles
8.6.4. Perimeter Security & Alarms
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Bollards
9.1.2. Fences
9.1.3. Crash Barrier Systems
9.1.4. Crash Barrier Devices
9.1.5. Drop Arms
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Metal
9.2.2. Plastic
9.2.3. Concrete
9.2.4. Wood
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Rigid
9.3.2. Semi-Rigid
9.3.3. Flexible
9.4. Market Analysis, Insights and Forecast - by Function
9.4.1. Passive Barriers
9.4.2. Active Barriers
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Roadways
9.5.2. Railways
9.5.3. Commercial
9.5.4. Residential
9.5.5. Industrial
9.5.6. Military & Defense
9.6. Market Analysis, Insights and Forecast - by Access Control
9.6.1. Token & Reader
9.6.2. Biometric Systems
9.6.3. Turnstiles
9.6.4. Perimeter Security & Alarms
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Bollards
10.1.2. Fences
10.1.3. Crash Barrier Systems
10.1.4. Crash Barrier Devices
10.1.5. Drop Arms
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Metal
10.2.2. Plastic
10.2.3. Concrete
10.2.4. Wood
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Rigid
10.3.2. Semi-Rigid
10.3.3. Flexible
10.4. Market Analysis, Insights and Forecast - by Function
10.4.1. Passive Barriers
10.4.2. Active Barriers
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Roadways
10.5.2. Railways
10.5.3. Commercial
10.5.4. Residential
10.5.5. Industrial
10.5.6. Military & Defense
10.6. Market Analysis, Insights and Forecast - by Access Control
10.6.1. Token & Reader
10.6.2. Biometric Systems
10.6.3. Turnstiles
10.6.4. Perimeter Security & Alarms
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Barrier Systems Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Barrier Systems Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Barrier Systems Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Barrier Systems Market Revenue (Billion), by Material 2026 & 2034
Figure 5: North America Barrier Systems Market Revenue Share (%), by Material 2026 & 2034
Figure 6: North America Barrier Systems Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America Barrier Systems Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Barrier Systems Market Revenue (Billion), by Function 2026 & 2034
Figure 9: North America Barrier Systems Market Revenue Share (%), by Function 2026 & 2034
Figure 10: North America Barrier Systems Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Barrier Systems Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Barrier Systems Market Revenue (Billion), by Access Control 2026 & 2034
Figure 13: North America Barrier Systems Market Revenue Share (%), by Access Control 2026 & 2034
Figure 14: North America Barrier Systems Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Barrier Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Barrier Systems Market Revenue (Billion), by Product Type 2026 & 2034
List of Tables
Table 1: Barrier Systems Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Barrier Systems Market Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Barrier Systems Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Barrier Systems Market Revenue Billion Forecast, by Function 2020 & 2034
Table 5: Barrier Systems Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Barrier Systems Market Revenue Billion Forecast, by Access Control 2020 & 2034
Table 7: Barrier Systems Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Barrier Systems Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Barrier Systems Market Revenue Billion Forecast, by Material 2020 & 2034
Table 10: North America Barrier Systems Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 11: North America Barrier Systems Market Revenue Billion Forecast, by Function 2020 & 2034
Table 12: North America Barrier Systems Market Revenue Billion Forecast, by Application 2020 & 2034
Table 13: North America Barrier Systems Market Revenue Billion Forecast, by Access Control 2020 & 2034
Table 14: North America Barrier Systems Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Barrier Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Barrier Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current barrier systems market size?
The global barrier systems market was valued at USD 23.1 billion in 2026 and is forecast to reach USD 33.0 billion by 2035 at a 4.0% CAGR, according to one consolidated published estimate.
2. Which region dominates the barrier systems market?
Asia Pacific dominates with approximately 34% revenue share, supported by vehicle penetration growth and large-scale highway construction, while the Middle East & Africa is the fastest-growing region.
3. What are the main types of barrier systems?
Barrier systems include crash barriers, bollards, fences, drop arms and crash attenuators, segmented by material into metal, plastic, concrete and wood, and by function into passive and active systems.
4. Who are the leading barrier systems companies?
Valtir LLC leads with about 2.7% share, followed by Hill & Smith Holdings, Lindsay Corporation, Forterra and Nippon Steel Metal Products; the top five hold only 5.5% combined.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split anchors this analysis in verified procurement reality. We conducted in-depth interviews with highway infrastructure procurement specialists, HVM product engineers, and access-control integrators across steel suppliers, barrier manufacturers, engineering contractors, and installation distributors. Decision-maker designations interviewed included VP-level sourcing leads, technical directors, commercial operations managers, and regulatory compliance heads across North America, Europe and Asia Pacific.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
Technical & Engineering Directors
30%
Commercial Operations Managers
20%
Regulatory & Compliance Heads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Barrier Manufacturers & OEMs
45%
Steel & Material Suppliers
25%
Engineering Contractors
20%
Distributors & Integrators
10%
Secondary Benchmarking & Public Trade Validation
We validated figures against UN Comtrade steel product trade flows, US ITC tariff schedules, Eurostat construction materials data, WHO road-safety statistics, U.S. DOT grant disclosures, and corporate 10-K filings from listed barrier manufacturers. Patent databases and certification frameworks (ISO 22343-1, ASTM F2656, PAS 68) provided technical validation of product capability claims.
Demand Modeling & Market Sizing Triangulation
We triangulated top-down macroeconomic allocation of infrastructure budgets against bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Regional trade flows were cross-checked against stated regional revenue to identify scope inconsistencies between published estimates.
 Barrier Systems Market