Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Cell Culture Protein Surface Coating Market 2026 Analysis
Cell Culture Protein Surface Coating Market 2026 Analysis
Cell Culture Protein Surface Coating Market
Cell Culture Protein Surface Coating Market 2026 Analysis
Cell Culture Protein Surface Coating Market by Coating Type (Self-coating, Pre-coating), by Protein Source (Animal-derived, Human-derived, Synthetic, Plant-derived), by Protein Type (Basement Membrane Extracts, Collagen, Laminin, Fibronectin, Vitronectin, Others), by Application (Drug Discovery & Development, Stem Cell Research, Regenerative Medicine, Cancer Research, Tissue Engineering), by End User (Pharmaceutical & Biotechnology Companies, Academic & Research Institutes, CROs & CMOs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 211
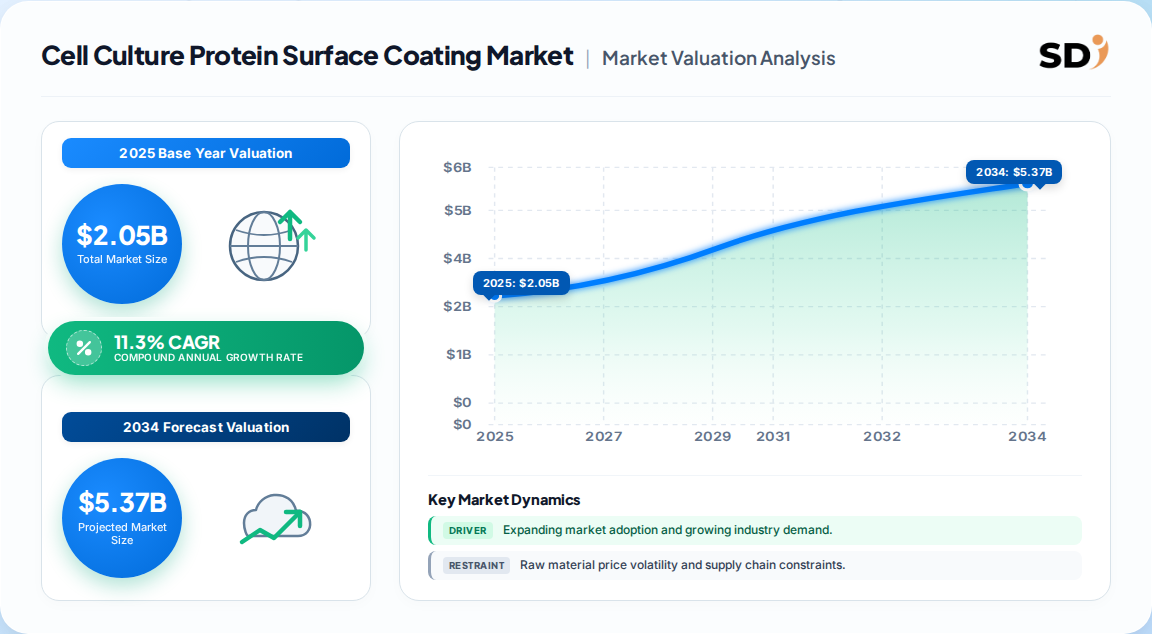
The global Cell Culture Protein Surface Coating Market was valued at 2.05 Billion in 2025 and is projected to reach 5.98 Billion by 2035, registering a 11.3% CAGR (2026–2035).
Pre-coated cultureware dominates the coating type segment, accounting for 58% of 2025 revenue, driven by convenience and reproducibility in high-throughput screening.
Animal-derived proteins remain the largest source (50% share), but recombinant and synthetic alternatives are the fastest-growing, propelled by cell therapy manufacturing demands.
North America leads with 40% revenue share, while Asia-Pacific is the fastest-growing region at a 12.8% CAGR, fueled by expanding biotech R&D and clinical trial activity.
Leading vendors include Corning, Thermo Fisher Scientific, Merck KGaA, Sartorius, and Greiner Bio-One, competing on portfolio breadth, GMP-grade offerings, and regional expansion.
Why this matters for decision-makers: Buyers must prioritize suppliers with documented lot-to-lot consistency and regulatory support for animal-free coatings, as the shift toward defined, GMP-grade matrices will differentiate successful cell therapy workflows and mitigate sourcing risks.
Cell Culture Protein Surface Coating Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.050 B
2025
2.280 B
2026
2.540 B
2027
2.830 B
2028
3.150 B
2029
3.500 B
2030
3.900 B
2031
Cell Culture Protein Surface Coating Market Size (In Billion)
Year
Market Size
2025
2.050 B
2026
2.280 B
2027
2.540 B
2028
2.830 B
2029
3.150 B
2030
3.500 B
2031
3.900 B
What is the Cell Culture Protein Surface Coating Market?
The cell culture protein surface coating market encompasses proteins and protein-based matrices—such as collagen, laminin, fibronectin, and basement membrane extracts—applied to culture vessels to enhance cell attachment, proliferation, and differentiation. These products are essential for stem cell research, 3D culture, drug discovery, and cell therapy manufacturing, available as self-coating reagents or pre-coated labware.
Scope: what this report covers and excludes
This report provides a comprehensive analysis of the global cell culture protein surface coating market, covering coating types (self-coating, pre-coating), protein sources (animal-derived, human-derived, synthetic, plant-derived), protein types (basement membrane extracts, collagen, laminin, fibronectin, vitronectin, others), applications (drug discovery, stem cell research, regenerative medicine, cancer research, tissue engineering), and end users (pharma & biotech, academic institutes, CROs/CMOs). It includes market sizing, segmentation, regional forecasts to 2035, competitive landscape, and strategic insights. This analysis does not cover adjacent markets such as cell culture media, sera, or plastic consumables without protein coatings, nor does it address equipment like bioreactors or analytical instruments.
How big is the market for Cell Culture Protein Surface Coating Market?
Estimates for the cell culture protein surface coating market vary due to differing scope definitions and base years. One published analysis values the market at 2.05 Billion in 2025, growing to 5.98 Billion by 2035 at an 11.3% CAGR. A competing estimate cites 1.3 Billion in 2025 with a 15.9% CAGR to 4.2 Billion by 2033. A third source projects a 9.5% CAGR (2025–2030). Our analysis suggests the 2.05 Billion base is most defensible, as it aligns with bottom-up volume estimates across pre-coated cultureware and reagent sales, and its 11.3% CAGR reflects a balance between robust demand from cell therapy manufacturing and pricing pressure from recombinant alternatives. The divergence underscores the importance of clearly defined scope: narrower definitions (e.g., excluding microcarriers) yield lower valuations.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
2.05 Billion
2025
2035
11.3%
Full market incl. pre-coated cultureware and reagents
One published analysis
1.3 Billion
2025
2033
15.9%
Core coatings, possibly excluding microcarriers
A competing estimate
9.5% CAGR
2025
2030
9.5%
Broad market, conservative growth
A third source
How is the market segmented?
The market is segmented by coating type, protein source, protein type, application, and end user. Pre-coating dominates, while self-coating reagents are gaining traction for scalability and cost efficiency in cell therapy manufacturing. Animal-derived proteins hold the largest share but face regulatory and ethical pressures, accelerating the adoption of recombinant and synthetic alternatives.
Which region leads in Cell Culture Protein Surface Coating Market?
North America leads the global cell culture protein surface coating market with a 40% revenue share in 2025, estimated at 0.82 Billion, driven by advanced research infrastructure and high R&D spending. Europe follows with 29% (0.59 Billion), while Asia-Pacific accounts for 24% (0.49 Billion) and is the fastest-growing region at a 12.8% CAGR. The region's growth is fueled by expanding biotech sectors, increasing clinical trials, and government initiatives to boost life sciences research.
Cell Culture Protein Surface Coating Market Regional Market Share
Loading chart...
Cell Culture Protein Surface Coating Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.28%
Asia-Pacific
0.26%
South America
0.04%
Middle East & Africa
0.04%
Region
Share (2025)
Value (2025)
North America
40%
0.82 Billion
Europe
29%
0.59 Billion
Asia-Pacific
24%
0.49 Billion
South America
4%
0.08 Billion
Middle East & Africa
3%
0.06 Billion
What is driving growth — and what is holding it back?
Growth is primarily driven by the expansion of stem cell research, the rise of 3D cell culture and organoid models, and the scaling of cell and gene therapy manufacturing. These factors are amplified by regulatory preferences for defined, animal-free matrices. However, high costs of recombinant proteins, lot-to-lot variability in animal-derived matrices, and limited awareness in emerging markets restrain broader adoption.
Factor
Direction
Evidence Strength
Mechanism
Stem cell research expansion
Driver
High
Requires specialized matrices for attachment and differentiation
Cell therapy manufacturing scale-up
Driver
High
Demands GMP-grade, consistent coatings for reproducibility
Regulatory push for defined materials
Driver
Medium
Favors recombinant and synthetic coatings over animal-derived
High cost of recombinant proteins
Restraint
High
Limits adoption in price-sensitive research settings
Lot-to-lot variability
Restraint
Medium
Undermines reproducibility, especially in animal-derived matrices
Limited awareness in emerging markets
Restraint
Low
Slows penetration of advanced coatings
Who are the leading vendors?
The market is moderately fragmented, with key players including Corning Incorporated, Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, and Greiner Bio-One International GmbH. These companies compete on portfolio breadth, technological innovation, and geographic reach, with a strong focus on recombinant and GMP-grade coatings for cell therapy applications.
Company
Headquarters
Key Differentiators
Corning Incorporated
USA
Broad portfolio of pre-coated cultureware; BioCoat line
Thermo Fisher Scientific Inc.
USA
Extensive life sciences portfolio; Gibco brand coatings
Merck KGaA
Germany
Strong in recombinant proteins and specialty matrices
Sartorius AG
Germany
Focus on bioprocessing and cell therapy workflows
Greiner Bio-One International GmbH
Germany
Specialized in advanced cell culture surfaces and labware
What do buyers and operators need to know?
Buyers must prioritize suppliers with documented lot-to-lot consistency and regulatory documentation (e.g., ISO 9001, GMP compliance) to ensure reproducible results. Switching costs are high due to validation requirements, so procurement should evaluate total cost of ownership, including technical support and supply chain reliability. Regulatory compliance, especially for animal-derived components, is critical; operators should seek suppliers offering traceability and animal-free alternatives to mitigate risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook, with the market poised to double by 2035, driven by cell therapy manufacturing and stem cell research. The strongest counter-argument is that high costs and limited awareness could slow adoption in price-sensitive segments, but the regulatory tailwind toward defined matrices is likely to overpower these restraints. Our analysis suggests that vendors focusing on GMP-grade, recombinant coatings will capture disproportionate value.
Actionable Strategy:
Investors: Allocate to suppliers with strong IP in recombinant laminins and GMP-grade coatings, as these will command premium pricing.
Operators: Transition to pre-coated cultureware or optimized self-coating protocols to reduce variability and scale cell therapy production.
Procurement: Negotiate long-term agreements with vendors offering dual sourcing and technical support to mitigate supply risks.
What would change our conclusion? A significant price collapse in recombinant proteins or a major regulatory shift favoring animal-derived materials would alter the growth trajectory; however, current evidence strongly supports the defined, animal-free trend.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook, with the market poised to double by 2035, driven by cell therapy manufacturing and stem cell research. The strongest counter-argument is that high costs and limited awareness could slow adoption in price-sensitive segments, but the regulatory tailwind toward defined matrices is likely to overpower these restraints. Our analysis suggests that vendors focusing on GMP-grade, recombinant coatings will capture disproportionate value.
Actionable Strategy:
Investors: Allocate to suppliers with strong IP in recombinant laminins and GMP-grade coatings, as these will command premium pricing.
Operators: Transition to pre-coated cultureware or optimized self-coating protocols to reduce variability and scale cell therapy production.
Procurement: Negotiate long-term agreements with vendors offering dual sourcing and technical support to mitigate supply risks.
What would change our conclusion? A significant price collapse in recombinant proteins or a major regulatory shift favoring animal-derived materials would alter the growth trajectory; however, current evidence strongly supports the defined, animal-free trend.
Cell Culture Protein Surface Coating Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Cell Culture Protein Surface Coating Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.3% from 2020-2034
Segmentation
By Coating Type
Self-coating
Pre-coating
By Protein Source
Animal-derived
Human-derived
Synthetic
Plant-derived
By Protein Type
Basement Membrane Extracts
Collagen
Laminin
Fibronectin
Vitronectin
Others
By Application
Drug Discovery & Development
Stem Cell Research
Regenerative Medicine
Cancer Research
Tissue Engineering
By End User
Pharmaceutical & Biotechnology Companies
Academic & Research Institutes
CROs & CMOs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Coating Type
5.1.1. Self-coating
5.1.2. Pre-coating
5.2. Market Analysis, Insights and Forecast - by Protein Source
5.2.1. Animal-derived
5.2.2. Human-derived
5.2.3. Synthetic
5.2.4. Plant-derived
5.3. Market Analysis, Insights and Forecast - by Protein Type
5.3.1. Basement Membrane Extracts
5.3.2. Collagen
5.3.3. Laminin
5.3.4. Fibronectin
5.3.5. Vitronectin
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Drug Discovery & Development
5.4.2. Stem Cell Research
5.4.3. Regenerative Medicine
5.4.4. Cancer Research
5.4.5. Tissue Engineering
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Pharmaceutical & Biotechnology Companies
5.5.2. Academic & Research Institutes
5.5.3. CROs & CMOs
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Coating Type
6.1.1. Self-coating
6.1.2. Pre-coating
6.2. Market Analysis, Insights and Forecast - by Protein Source
6.2.1. Animal-derived
6.2.2. Human-derived
6.2.3. Synthetic
6.2.4. Plant-derived
6.3. Market Analysis, Insights and Forecast - by Protein Type
6.3.1. Basement Membrane Extracts
6.3.2. Collagen
6.3.3. Laminin
6.3.4. Fibronectin
6.3.5. Vitronectin
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Drug Discovery & Development
6.4.2. Stem Cell Research
6.4.3. Regenerative Medicine
6.4.4. Cancer Research
6.4.5. Tissue Engineering
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Pharmaceutical & Biotechnology Companies
6.5.2. Academic & Research Institutes
6.5.3. CROs & CMOs
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Coating Type
7.1.1. Self-coating
7.1.2. Pre-coating
7.2. Market Analysis, Insights and Forecast - by Protein Source
7.2.1. Animal-derived
7.2.2. Human-derived
7.2.3. Synthetic
7.2.4. Plant-derived
7.3. Market Analysis, Insights and Forecast - by Protein Type
7.3.1. Basement Membrane Extracts
7.3.2. Collagen
7.3.3. Laminin
7.3.4. Fibronectin
7.3.5. Vitronectin
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Drug Discovery & Development
7.4.2. Stem Cell Research
7.4.3. Regenerative Medicine
7.4.4. Cancer Research
7.4.5. Tissue Engineering
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Pharmaceutical & Biotechnology Companies
7.5.2. Academic & Research Institutes
7.5.3. CROs & CMOs
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Coating Type
8.1.1. Self-coating
8.1.2. Pre-coating
8.2. Market Analysis, Insights and Forecast - by Protein Source
8.2.1. Animal-derived
8.2.2. Human-derived
8.2.3. Synthetic
8.2.4. Plant-derived
8.3. Market Analysis, Insights and Forecast - by Protein Type
8.3.1. Basement Membrane Extracts
8.3.2. Collagen
8.3.3. Laminin
8.3.4. Fibronectin
8.3.5. Vitronectin
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Drug Discovery & Development
8.4.2. Stem Cell Research
8.4.3. Regenerative Medicine
8.4.4. Cancer Research
8.4.5. Tissue Engineering
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Pharmaceutical & Biotechnology Companies
8.5.2. Academic & Research Institutes
8.5.3. CROs & CMOs
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Coating Type
9.1.1. Self-coating
9.1.2. Pre-coating
9.2. Market Analysis, Insights and Forecast - by Protein Source
9.2.1. Animal-derived
9.2.2. Human-derived
9.2.3. Synthetic
9.2.4. Plant-derived
9.3. Market Analysis, Insights and Forecast - by Protein Type
9.3.1. Basement Membrane Extracts
9.3.2. Collagen
9.3.3. Laminin
9.3.4. Fibronectin
9.3.5. Vitronectin
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Drug Discovery & Development
9.4.2. Stem Cell Research
9.4.3. Regenerative Medicine
9.4.4. Cancer Research
9.4.5. Tissue Engineering
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Pharmaceutical & Biotechnology Companies
9.5.2. Academic & Research Institutes
9.5.3. CROs & CMOs
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Coating Type
10.1.1. Self-coating
10.1.2. Pre-coating
10.2. Market Analysis, Insights and Forecast - by Protein Source
10.2.1. Animal-derived
10.2.2. Human-derived
10.2.3. Synthetic
10.2.4. Plant-derived
10.3. Market Analysis, Insights and Forecast - by Protein Type
10.3.1. Basement Membrane Extracts
10.3.2. Collagen
10.3.3. Laminin
10.3.4. Fibronectin
10.3.5. Vitronectin
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Drug Discovery & Development
10.4.2. Stem Cell Research
10.4.3. Regenerative Medicine
10.4.4. Cancer Research
10.4.5. Tissue Engineering
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Pharmaceutical & Biotechnology Companies
10.5.2. Academic & Research Institutes
10.5.3. CROs & CMOs
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Cell Culture Protein Surface Coating Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by Coating Type 2026 & 2034
Figure 3: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by Coating Type 2026 & 2034
Figure 4: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by Protein Source 2026 & 2034
Figure 5: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by Protein Source 2026 & 2034
Figure 6: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by Protein Type 2026 & 2034
Figure 7: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by Protein Type 2026 & 2034
Figure 8: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by End User 2026 & 2034
Figure 11: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Cell Culture Protein Surface Coating Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Cell Culture Protein Surface Coating Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Cell Culture Protein Surface Coating Market Revenue (Billion), by Coating Type 2026 & 2034
Figure 15: Europe Cell Culture Protein Surface Coating Market Revenue Share (%), by Coating Type 2026 & 2034
List of Tables
Table 1: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Coating Type 2020 & 2034
Table 2: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Protein Source 2020 & 2034
Table 3: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Protein Type 2020 & 2034
Table 4: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by End User 2020 & 2034
Table 6: Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Coating Type 2020 & 2034
Table 8: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Protein Source 2020 & 2034
Table 9: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Protein Type 2020 & 2034
Table 10: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by End User 2020 & 2034
Table 12: North America Cell Culture Protein Surface Coating Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Cell Culture Protein Surface Coating Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Cell Culture Protein Surface Coating Market Revenue (Billion) Forecast, by Application 2020 & 2034
Mexico Cell Culture Protein Surface Coating Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current market size for cell culture protein surface coatings?
The market was valued at 2.05 Billion in 2025 and is projected to reach 5.98 Billion by 2035, growing at a CAGR of 11.3%.
2. Which region dominates the cell culture protein surface coating market?
North America leads with a 40% revenue share in 2025, followed by Europe at 29% and Asia-Pacific at 24%.
3. What are the key drivers of market growth?
Growth is driven by expanding stem cell research, 3D cell culture adoption, cell therapy manufacturing scale-up, and regulatory preference for defined matrices.
4. Who are the major players in the cell culture protein surface coating market?
Key players include Corning Incorporated, Thermo Fisher Scientific, Merck KGaA, Sartorius AG, and Greiner Bio-One International.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employed a 70/30 primary-to-secondary research split. We conducted in-depth interviews with key stakeholders across the value chain, including raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring comprehensive insights into market dynamics and procurement strategies. These interviews were instrumental in validating market size, growth drivers, and competitive positioning.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
30%
Heads of R&D
35%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers
40%
Specialized Producers
30%
Contract Formulators
15%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
We extensively referenced official multilateral trade databases such as UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This secondary benchmarking provided a robust foundation for cross-validating primary data and identifying macro-level trends.
Demand Modeling & Market Sizing Triangulation
Our demand modeling employed simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. This dual approach enabled us to reconcile market estimates and derive a reliable base-year valuation and forecast trajectory.
 Cell Culture Protein Surface Coating Market