 North America Geotextiles Market
 2025: Size, Share & Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 242

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Geotextiles Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 1.370 B |
| 2025 | 1.430 B |
| 2026 | 1.490 B |
| 2027 | 1.560 B |
| 2028 | 1.630 B |
| 2029 | 1.700 B |
| 2030 | 1.770 B |

The North America geotextiles market comprises permeable woven, non-woven and knitted fabrics made from synthetic or natural polymers, used in civil engineering to separate, filter, drain, reinforce and stabilize soil. It spans road, railway, landfill, coastal and agricultural applications across the U.S., Canada and Mexico.
This report covers geotextiles across all product forms (woven, non-woven, knitted), materials (synthetic, natural), and applications including separation, stabilization, drainage, erosion control, reinforcement, asphalt overlays, lining systems and silt fences. It sizes and forecasts the U.S., Canada and Mexico markets to 2030. This analysis does not cover adjacent geosynthetics such as geogrids, geomembranes, geocells or erosion-control blankets, nor does it cover raw polymer supply markets.
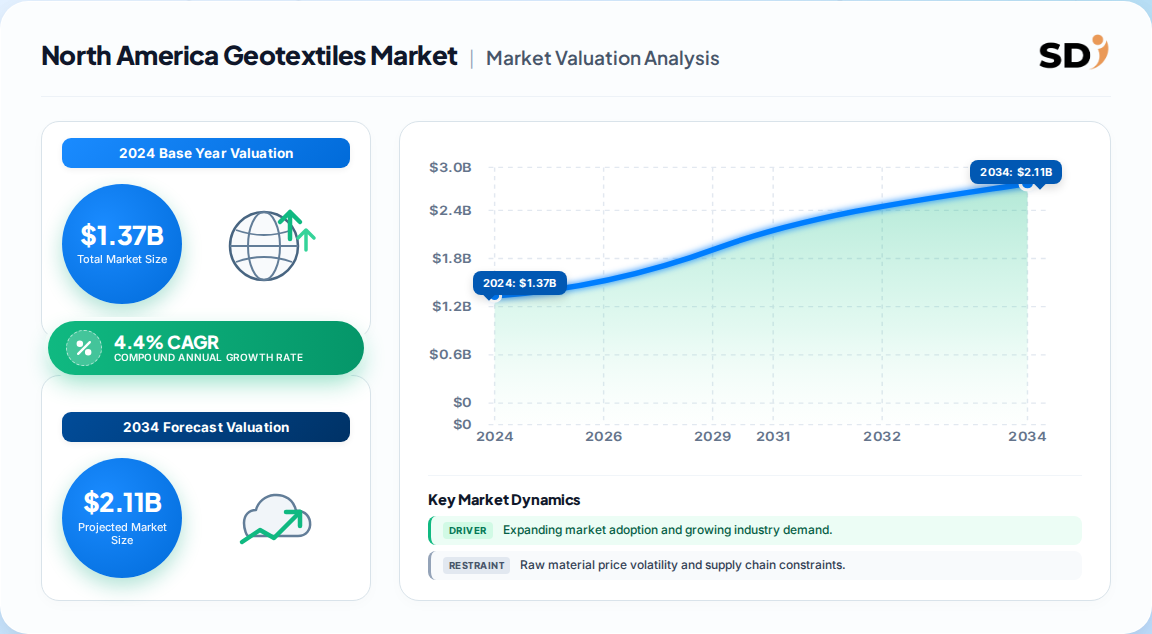
Estimates diverge sharply: one published estimate puts the 2024 base at 1.37 Billion with a 4.4% CAGR, while a competing analysis implies 1.09 Billion in 2022 growing at 8.0%. The 4.4% figure is more defensible for a mature, construction-linked region.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1.37 Billion | 2024 | 2030 | 4.4% | Regional geotextiles, all products and materials | One published estimate |
| 1.09 Billion | 2022 | 2032 | 8.0% | Regional geotextiles, includes COVID-19 impact analysis | A competing analysis |
| 1.8 Billion (non-woven only) | 2025 | 2030 | 6.2% | Non-woven geotextiles only, regional | Trade-press benchmark |
Our analysis suggests the 8.0% CAGR is inconsistent with North American construction spending growth of roughly 4-5% and likely conflates global or adjacent geosynthetics categories. The 1.37 Billion base and 4.4% CAGR align with U.S. DOT outlays and replacement-cycle dynamics, making it the most credible planning anchor.
Segmentation follows three axes: material (synthetic vs. natural), product form (non-woven, woven, knitted) and application (separation, drainage, erosion control and others). Synthetic and non-woven dominate, but natural and woven are the faster-growing niches.
| Parent Segment | Children | 2024 Share | Growth Outlook |
|---|---|---|---|
| By Material | Synthetic, Natural | Synthetic 92.0% | Natural 5.0% CAGR |
| By Product | Non-woven, Woven, Knitted | Non-woven 63.4% | Woven 5.3% CAGR |
| By Application | Separation & Stabilization, Drainage, Erosion Control, Reinforcement, Asphalt Overlays, Lining Systems, Silt Fences, Agriculture | Separation 27.3% | Drainage 4.8% CAGR |
The United States leads with 74% of regional revenue, driven by extensive highway networks, drainage maintenance and federal infrastructure programs. Canada follows with mature civil-engineering demand, while Mexico is the fastest-growing market.
Canada's growth is tied to transportation investment in the Northwest Territories and mining access roads, while Mexico benefits from nearshoring-driven industrial construction and coastal protection along the Gulf. The U.S. dominance means national specification changes, not regional ones, set the pace for the entire market.
Growth is driven by infrastructure rehabilitation, erosion-control regulation and the cost advantage of geotextiles over aggregate or stone alternatives. Restraints center on petroleum-linked resin price volatility and microplastic concerns that could trigger additive restrictions.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Federal infrastructure funding | Driver | High | RAISE grants and highway programs embed geotextiles in specifications |
| Soil erosion and climate resilience | Driver | High | Extreme weather raises demand for separation and erosion control |
| Cost and lifespan advantage | Driver | Medium | Lower aggregate thickness and longer asset life |
| Recycled and bio-based polymer adoption | Driver | Medium | ESG tender criteria favor certified recycled content |
| Resin price volatility | Restraint | High | Polypropylene and polyester costs track crude oil |
| Microplastic runoff regulation | Restraint | Medium | Potential additive bans force reformulation |
The balance favors growth: public funding is multi-year and specification-driven, while resin volatility is cyclical. Our analysis suggests microplastic regulation is the underappreciated risk; suppliers who pre-certify low-shedding products will convert a restraint into a moat.
The competitive landscape is moderately consolidated, with global geosynthetics specialists and regional converters competing on technical specification, certification and distribution reach rather than price alone.
| Company | Positioning | Product Strength | Regional Presence |
|---|---|---|---|
| TenCate Geosynthetics | Global specialist | Woven and non-woven reinforcement | U.S., Canada |
| Fibertex Nonwovens | Non-woven leader | Needle-punched non-wovens | U.S., Mexico |
| Officine Maccaferri | Infrastructure solutions | Erosion control systems | U.S., Canada |
| Propex Operating Company | Technical textiles | Woven and non-woven | U.S. |
| HUESKER Group | Engineering-led | Reinforcement and drainage | U.S., Canada |
| NAUE GmbH | Technical geosynthetics | Clay liners and geotextiles | U.S. |
| Solmax | Geosynthetics consolidator | Full portfolio | North America |
| SKAPS Industries | Value-focused | Non-woven and drainage | U.S. |
Differentiation rests on state DOT approvals, ASTM test compliance and recycled-content certification. Smaller manufacturers can win in agricultural and erosion-control niches where specification barriers are lower.
Buyers should prioritize ASTM and state DOT qualification over unit price, because installation failure liabilities dwarf material savings. Procurement risk concentrates in resin price pass-through clauses, lead times for certified recycled grades and the availability of technical support for complex drainage designs. Switching costs are moderate: re-qualifying a geotextile with a state agency can take months, which locks in approved suppliers but also protects incumbents. Regulatory compliance now extends to microplastic shedding and recycled-content claims, so buyers should demand third-party test reports rather than supplier declarations.
The balance of evidence favors a steady, specification-driven expansion at 4.4% CAGR, not the 8% trajectory some analyses imply. The strongest counter-argument is that a renewed federal infrastructure package could push growth toward 6%, but even that scenario keeps North America behind global growth because the region's networks are mature and replacement-driven.
Our analysis suggests the most consequential shift is the divergence between synthetic dominance (92%) and natural growth (5.0% CAGR). This is not a substitution story yet; it is a compliance story. Public tenders increasingly reward recycled content, and suppliers who certify it first will capture specification share without eroding margins.
What would change our conclusion: a sustained crude oil spike above prior-cycle highs, or federal rules banning specific polymer additives, would compress margins and slow adoption faster than the base case assumes.
| Region | Market Share (%) |
|---|---|
| United States | 0.74% |
| Canada | 0.15% |
| Mexico | 0.11% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.4% from 2020-2034 |
| Segmentation |
|
The market was estimated at 1.37 Billion in 2024 and is forecast to grow at a 4.4% CAGR through 2030. The United States accounts for roughly 74% of regional revenue, with Mexico the fastest-growing country at 6.2% CAGR.
Non-woven geotextiles lead with 63.4% revenue share, driven by low cost and high tensile strength in transport infrastructure. Woven geotextiles are the faster-growing segment at 5.3% CAGR, favored for filtration and separation.
Federal infrastructure funding, aging road and drainage networks, and climate-driven erosion control are the primary drivers. The cost and lifespan advantage over aggregate alternatives also supports adoption across road, railway and landfill projects.
Key vendors include TenCate Geosynthetics, Fibertex Nonwovens, Officine Maccaferri, Propex Operating Company, HUESKER Group, NAUE, Solmax and SKAPS Industries. Competition centers on state DOT approvals, ASTM compliance and recycled-content certification.
Estimates diverge because some analyses include adjacent geosynthetics or use different base years and scopes. The 1.37 Billion base for 2024 with a 4.4% CAGR is most consistent with North American construction spending growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study rests on a 70/30 primary-to-secondary research split. Our analysts conducted in-depth interviews across the value chain, including raw material and polymer suppliers, specialized geotextile producers, contract manufacturers and regional distributors. Interviewees were drawn from decision-maker roles including VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring that both technical specification and commercial dynamics were validated.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & R&D Directors | 35% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Polymer Suppliers | 30% |
| Geotextile Producers | 40% |
| Contract Manufacturers | 15% |
| Distributors & Traders | 15% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K reports, patent databases, and recognized technical standards bodies. ASTM, ISO and EN test series were used to benchmark product specifications, while transportation-agency publications validated infrastructure-linked demand assumptions.
We applied simultaneous top-down and bottom-up triangulation. Top-down modeling allocated macroeconomic construction output and infrastructure spending to geotextile-intensive applications. Bottom-up modeling estimated manufacturer capacity, product pricing and end-use consumption by country, reconciling the two approaches to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |