 Aluminosilicate Glass Market
: Size, Share & 2033 Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 232

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Aluminosilicate Glass Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 16.20 B |
| 2025 | 17.50 B |
| 2026 | 18.80 B |
| 2027 | 20.30 B |
| 2028 | 22.00 B |
| 2029 | 23.80 B |
| 2030 | 25.70 B |

Aluminosilicate glass is a high-performance glass formulated with aluminum oxide and silica, enabling superior chemical strengthening. It delivers high scratch resistance, impact durability, and optical clarity, making it the material of choice for smartphone cover glass, automotive displays, and semiconductor substrates.
This report covers global supply and demand for aluminosilicate glass across chemically strengthened, thermally strengthened, and other product types used in consumer electronics, automotive, aerospace and defense, and other industrial applications. This analysis does not cover adjacent markets such as soda-lime glass, borosilicate glass, synthetic sapphire, or polymer-based protective films.
Valuations for 2025 cluster around 17.1 to 17.5 Billion USD, yielding a 2026-2033 forecast horizon of 32 to 34 Billion USD. The dispersion in estimates reflects divergent assumptions on foldable device adoption and automotive display penetration.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 17.5 Billion | 2025 | 2033 | 8.1% | Global supply and demand, product and end-use | One published benchmark |
| 17.11 Billion | 2025 | 2034 | 8.2% | Global, type and application segmentation | A competing analysis |
| 32.4 Billion | 2033 | 2033 | 8.1% | Forecast endpoint | One published benchmark |
| 34.52 Billion | 2034 | 2034 | 8.2% | Forecast endpoint | A competing analysis |
The more conservative 17.5 Billion to 32.4 Billion trajectory is the most defensible. It aligns with observed smartphone replacement cycles and moderate foldable adoption. Our analysis suggests the aggressive 8.2 CAGR rests on faster automotive display penetration and semiconductor substrate uptake, which remain uncertain. Buyers should model a base case near 8.0-8.1 percent and stress-test upside scenarios.
Segmentation follows three axes: product form, end-use application, and strengthening technology. Chemically strengthened glass dominates revenue, while ultra-thin glass represents the fastest-growing niche.
| Parent Segment | Sub-Segments | Share / Growth |
|---|---|---|
| By Product | Chemically Strengthened, Thermally Strengthened, Ultra-thin, Flat/Sheet | Chemically Strengthened ~49% share; Ultra-thin fastest CAGR |
| By Application | Cover Glass, Display & Panel Systems | Cover Glass largest |
| By End Use | Consumer Electronics, Automotive, Aerospace & Defense, Others | Consumer Electronics ~42% share; Automotive 8.6% CAGR |
| By Strengthening | Ion-exchange, Thermal | Ion-exchange dominant |
Our analysis suggests ultra-thin aluminosilicate glass will quietly become a 3-4 Billion sub-segment by 2033, but only if foldable device durability improves and price premiums compress. Vendors with ion-exchange depth and thin-glass handling capability are best positioned.
Asia Pacific leads the global aluminosilicate glass market with approximately 55 revenue share in 2025, anchored by China, South Korea, Japan, and Taiwan. North America follows at roughly 23 share, with Europe at 15.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.53% |
| North America | 0.23% |
| Europe | 0.15% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Countries |
|---|---|
| Asia Pacific | China, Japan, India, South Korea, Taiwan, Malaysia, Indonesia, Australia |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Netherlands, Russia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Israel |
Asia Pacific's dominance is structural, not cyclical. It hosts the largest electronics OEMs, the deepest glass processing ecosystem, and the fastest-growing domestic demand for mid-range devices. Our analysis suggests China alone accounts for 30-35 percent of global consumption, making it the single most strategically important country for capacity planning.
Demand for durable, lightweight glass in smartphones, foldables, and automotive displays is the primary growth engine, while high processing costs and alternative materials act as meaningful restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Consumer electronics proliferation | Driver | High | Rising smartphone and wearable penetration |
| Automotive display integration | Driver | High | Digital cockpits, HUDs, EV interiors |
| Foldable and flexible devices | Driver | Medium | Ultra-thin glass demand |
| Semiconductor substrate demand | Driver | Medium | High-purity glass for advanced packaging |
| High ion-exchange processing costs | Restraint | High | Limits adoption in cost-sensitive segments |
| Competition from sapphire, polymers | Restraint | Medium | Alternative materials for niche uses |
| Regulatory scrutiny and consolidation | Restraint | Medium | Antitrust probes, vendor exits |
The balance favors growth, but the drivers are concentrated. Consumer electronics and automotive together account for more than 70 percent of incremental demand. This concentration creates vulnerability to a single demand shock, such as a smartphone replacement cycle extension. The 2024-2025 regulatory scrutiny of cover glass exclusivity practices is a second-order risk that could reshape supply relationships.
The market is moderately consolidated, with Corning, AGC, Nippon Electric Glass, SCHOTT, and CSG leading through ion-exchange IP, OEM relationships, and vertical integration.
| Company | HQ | Strategic Focus | Moat |
|---|---|---|---|
| Corning Incorporated | USA | Gorilla Glass, automotive, semiconductor | Ion-exchange IP, Apple/Samsung ties |
| AGC Inc. | Japan | Automotive, architectural, cover glass | Float glass scale; exiting cover glass by 2026 |
| Nippon Electric Glass | Japan | Thin glass, semiconductor substrates | Glass-ceramic packaging innovation |
| SCHOTT AG | Germany | Medical, defense, optics | High-performance niche specialization |
| China South Glass (CSG) | China | Cost-competitive cover glass | Domestic OEM relationships, scale |
| Lens Technology | China | Cover glass processing | Apple supply chain integration |
Differentiation rests on three pillars: ion-exchange chemistry depth, OEM co-development relationships, and thin-glass handling capability. Corning's moat is the strongest, but AGC's announced exit from chemically strengthened cover glass by 2026 creates a supply gap. Our analysis suggests this gap will be filled by Chinese and Korean suppliers, accelerating price competition in mid-range segments.
Procurement decisions hinge on four criteria: scratch resistance performance, optical clarity, supply reliability, and total cost of ownership. Buyers should validate vendor claims against standardized abrasion tests, not marketing specifications, because benchmarks vary significantly across OEMs.
Switching costs are high. Qualifying a new glass supplier typically requires 6-12 months of device-level testing and OEM approval. This creates stickiness but also risk if a primary supplier exits, as AGC's 2026 withdrawal demonstrates. Operators should dual-source ultra-thin glass and maintain buffer inventory.
Regulatory compliance is tightening. EU circular economy rules favor durable glass with longer device lifecycles, while antitrust scrutiny of exclusivity arrangements may force supply chain diversification. Buyers should audit supplier concentration and build contingency plans for pricing volatility in specialty raw materials.
The balance of evidence favors a base case of 8.0-8.1 percent CAGR through 2033, with upside risk from automotive displays and downside risk from foldable adoption delays. The market is not slowing, but it is maturing in consumer electronics and accelerating in automotive and semiconductor applications. Vendors that treat aluminosilicate glass as a commodity will face margin compression.
The strongest counter-argument is that foldable devices could scale faster than expected, pulling ultra-thin glass into mainstream price points and lifting the entire market above 9 percent CAGR. However, current durability feedback and price premiums suggest this is a 2028+ scenario, not a 2026 one.
Actionable strategy:
What would change our conclusion: sustained foldable adoption above 15 percent of smartphone shipments, or a breakthrough in low-cost ion-exchange processing that collapses ultra-thin glass pricing.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.1% from 2020-2034 |
| Segmentation |
|
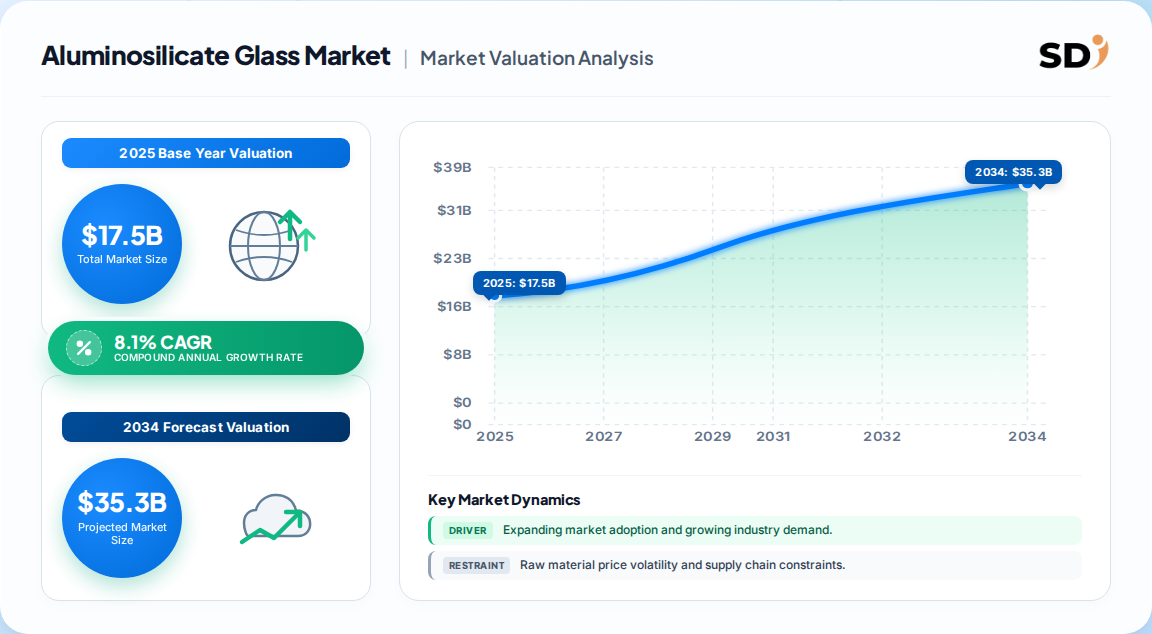
The global aluminosilicate glass market was valued at approximately 17.5 Billion USD in 2025, with competing estimates ranging from 17.1 to 17.5 Billion. It is projected to reach 32.4 Billion by 2033 at a 8.1 CAGR.
Asia Pacific dominates with approximately 55 percent revenue share in 2025, driven by electronics manufacturing in China, South Korea, Japan, and Taiwan. North America follows at roughly 23 percent and Europe at 15 percent.
Consumer electronics proliferation, automotive display integration, foldable device adoption, and semiconductor substrate demand are the primary drivers. Smartphones, wearables, and digital cockpits require scratch-resistant, durable cover glass.
Corning, AGC, Nippon Electric Glass, SCHOTT, China South Glass, Lens Technology, and Saint-Gobain lead the market. Corning holds the strongest moat through ion-exchange IP and OEM relationships.
Ultra-thin aluminosilicate glass is the fastest-growing product segment, driven by foldable smartphones and flexible displays. Consumer electronics leads end-use, while automotive displays grow at a faster 8.6 CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the aluminosilicate glass value chain. We engaged raw material suppliers, specialty glass producers, contract coaters and formulators, and global distributors to capture capacity, pricing, and qualification dynamics. Decision-maker interviews included VP-level sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads at OEMs and glass processors. Fieldwork focused on ion-exchange processing economics, thin-glass handling, and automotive qualification timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Glass Producers & Processors | 45% |
| Raw Material & Coating Suppliers | 30% |
| OEMs & Display Integrators | 25% |
We triangulated primary findings against official multilateral trade databases including UN Comtrade, WTO tariff schedules, US ITC trade data, and Eurostat industrial statistics. Corporate annual filings, 10-K disclosures, and investor presentations from publicly listed glass manufacturers were reviewed for capacity and revenue benchmarks. Patent databases informed our assessment of ion-exchange and ultra-thin glass innovation trajectories. Recognized technical standards bodies and industry associations provided validation of material performance claims.
We applied simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic indicators and electronics/automotive segment forecasts to size addressable demand. Bottom-up modeling used manufacturer capacity, product pricing, and end-use consumption estimates. The two approaches were reconciled to produce a base-year valuation and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |