 Bio Based Textile Fibers Market
 Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 257

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Bio Based Textile Fibers Market
Khageshwar Rongkali
Senior Analyst

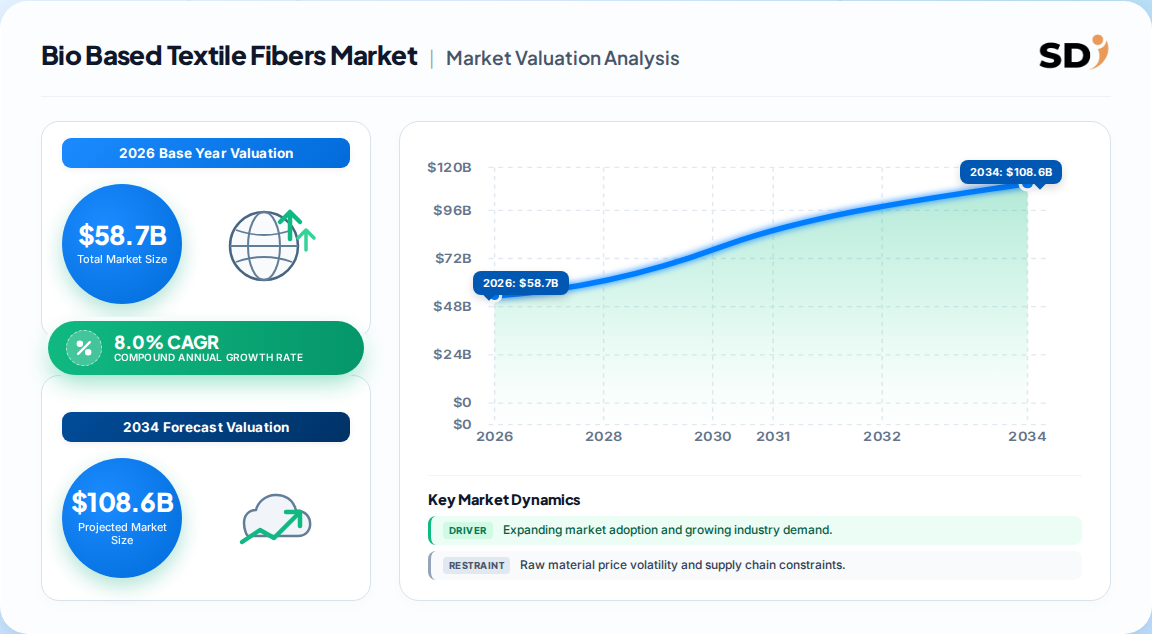
| Year | Market Size |
|---|---|
| 2025 | 54.10 B |
| 2026 | 58.70 B |
| 2027 | 63.40 B |
| 2028 | 68.50 B |
| 2029 | 73.90 B |
| 2030 | 79.80 B |
| 2031 | 86.20 B |

Bio-based textile fibers are textile raw materials derived from renewable biological sources—plants, animals, or microbial fermentation—rather than petroleum. They include cellulose fibers (viscose, lyocell, modal), natural fibers, and emerging bioengineered options like PLA and mycelium, offering biodegradability and lower carbon footprints.
This analysis covers global bio-based textile fibers across plant-based, animal-based, and microbial/bioengineered sources, segmented by application (apparel, home textiles, industrial textiles) and region. It excludes conventional synthetic fibers, purely petroleum-derived textiles, and non-fiber bio-based materials such as bioplastics or bio-chemicals used outside textile applications.
The market was valued at 54.1 Billion in 2025, with estimates for 2026 ranging from 58.7 Billion (broad bio-based textiles) to narrower fiber-only scopes. The table below compares competing published estimates and their definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 54.1 Billion | 2025 | 2033 | 8.0% | Bio-based textiles, all sources | One published estimate |
| 37.45 Billion | 2025 | 2034 | 6.50% | Cellulose fibers only (narrower) | A competing analysis |
| 6.64 Billion | 2026 | 2033 | 13.0% | Biodegradable fabrics (subset) | A competing analysis |
Our analysis suggests the 54.1 Billion figure is the most defensible for total market sizing because it captures the full bio-based fiber spectrum, while the cellulose-only and biodegradable-fabric figures represent narrower sub-segments with different growth trajectories.
Segmentation below reflects non-geographic parents only. Plant-based fibers dominate volume, while microbial/bioengineered fibers represent the fastest-growing niche.
| Parent Segment | Children | 2025 Share |
|---|---|---|
| Source Material | Plant-Based, Animal-Based, Microbial/Bioengineered | Plant-Based 63.9% |
| Application | Apparel, Home Textiles, Industrial Textiles | Apparel 51.0% |
Asia Pacific leads with 43.9% revenue share in 2025, driven by China's textile manufacturing base and export orientation. Europe and North America follow, propelled by regulatory pressure and sustainability mandates.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.44% |
| Europe | 0.24% |
| North America | 0.22% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | 2025 Share |
|---|---|
| Asia Pacific | 43.9% |
| Europe | 24.0% |
| North America | 22.0% |
| Latin America | 6.0% |
| Middle East & Africa | 4.1% |
Demand is anchored by sustainability mandates and brand commitments, but high production costs and limited large-scale infrastructure constrain mass-market adoption. The balance favors growth, though cost parity remains the gating factor.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Sustainability demand | Driver | High | Consumer preference and brand ESG targets |
| Regulatory pressure (EU Circular Economy) | Driver | High | Mandates for recycled/biodegradable content |
| High production costs | Restraint | High | Specialized feedstocks and limited capacity |
| Feedstock supply inconsistency | Restraint | Medium | Agricultural variability and logistics |
| Bioengineered fiber innovation | Opportunity | Medium | Mycelium, microbial cellulose scaling |
The market is moderately concentrated, with Lenzing AG and Birla Cellulose leading on lyocell and closed-loop technology, while Toyobo and others pursue bioengineered niches. Differentiation hinges on certified sustainable sourcing and capacity scale.
| Company | Specialty | Competitive Moat |
|---|---|---|
| Lenzing AG | Lyocell, modal, viscose | Closed-loop technology, brand certification |
| Birla Cellulose | Viscose, lyocell | Integrated pulp supply, Asia scale |
| Toyobo | Bio-based specialty fibers | R&D pipeline, niche applications |
| Fulgar | Bio-based nylon, yarns | Brand partnerships, innovation |
Buyers must prioritize certified sustainable sourcing (e.g., FSC, EU Ecolabel) to meet regulatory requirements and brand audits. Switching costs are moderate—qualification cycles for new fiber suppliers typically run 6–12 months—so early engagement is critical. Procurement risks include feedstock price volatility and limited lyocell capacity, which can delay orders. Operators should monitor EU circular economy mandates and invest in traceability systems to avoid compliance penalties and margin erosion.
The balance of evidence favors accelerated adoption of bio-based fibers, with Asia Pacific as the manufacturing anchor and Europe as the regulatory catalyst. However, the strongest counter-argument is that high production costs could cap growth in price-sensitive segments, slowing mass-market penetration until cost parity is achieved.
Our analysis suggests that the 8.0% CAGR is achievable if lyocell capacity scales and bioengineered fibers commercialize. The divergence between broad bio-based textiles (54.1 Billion) and cellulose-only (37.45 Billion) estimates implies that investors should focus on cellulose as the near-term volume driver while watching bioengineered fibers for long-term upside.
Actionable Strategy:
What would change our conclusion: A sharp decline in bio-based fiber production costs or a breakthrough in feedstock scalability would accelerate growth beyond 8.0%, while sustained high costs could push the CAGR toward 6.5%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
The global bio-based textile fibers market was valued at 54.1 Billion in 2025 and is projected to reach 58.7 Billion in 2026, growing to 100.4 Billion by 2033 at an 8.0% CAGR.
Asia Pacific leads with 43.9% revenue share in 2025, driven by China's large textile manufacturing base and strong export demand from the US and EU.
Key drivers include rising consumer demand for sustainable textiles, stringent environmental regulations like the EU Circular Economy Action Plan, and brand commitments to reduce carbon footprints.
Leading companies include Lenzing AG, Birla Cellulose, Toyobo, and Fulgar, competing on closed-loop production technology, certified sustainable sourcing, and capacity scale.
Microbial/bioengineered fibers represent the fastest-growing niche, while man-made cellulose fibers lead volume with a 53.9% share, driven by lyocell capacity expansion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain: raw material suppliers, specialized fiber producers, contract formulators, and global distributors. Decision-maker roles interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Compliance Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Fiber Producers | 45% |
| Contract Formulators & Processors | 30% |
| Global Distributors & Traders | 25% |
We validate findings against UN Comtrade, WTO, US ITC, and Eurostat trade databases, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations.
Our simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption modeling) triangulation ensures robust market sizing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |