Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
AI Chemicals Market Size, CAGR & Forecast to 2034
AI Chemicals Market Size, CAGR & Forecast to 2034
AI Chemicals Market
AI Chemicals Market Size, CAGR & Forecast to 2034
AI Chemicals Market by Component (Hardware, Software, Services), by Technology (Machine Learning, Deep Learning, Generative AI, NLP, Computer Vision, Advanced Analytics), by Business Application (R&D, Production, Supply Chain Management, Strategy Management), by End User (Basic Chemicals, Advanced Materials, Active Ingredients, Green & Biochemicals, Paints & Coatings, Adhesives & Sealants, Water Treatment), by Deployment Mode (Cloud, On-Premises), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia), by Asia Pacific (China, Japan, India, South Korea, Malaysia, Indonesia, Australia, Vietnam), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 232
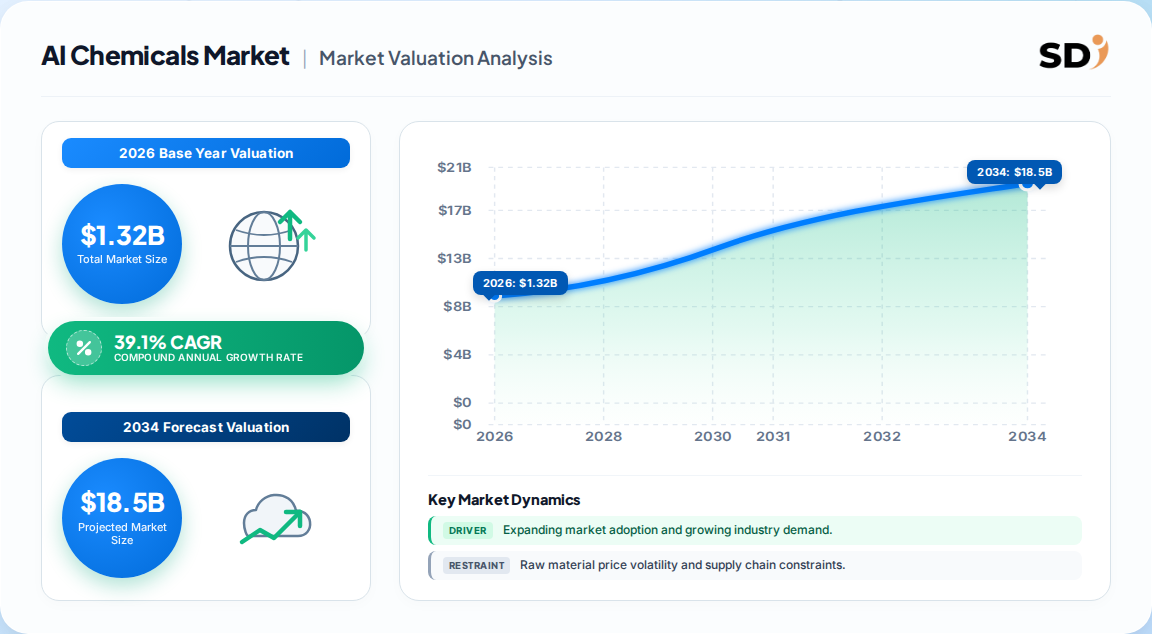
The global AI chemicals market is valued at 1.32 Billion in 2026, scaling to 18.58 Billion by 2034 — a 39.1% CAGR.
Software is the fastest-growing component, with R&D the leading business application as chemical firms industrialize molecular discovery.
North America leads adoption at an estimated 38% revenue share, but Asia-Pacific posts the steeper forecast CAGR.
Base chemicals and petrochemicals remain the largest end-user block, though specialty and active-ingredient pipelines grow fastest.
Key players include AWS, Microsoft, Google, IBM, C3.ai, Iktos, Hexagon and GE Vernova; no single vendor exceeds 15% share.
The R&D discovery cycle — not plant automation — is where AI currently creates measurable economic value.
Why this matters for decision-makers: Buyers must treat AI as an R&D capital-allocation tool first; vendors that lead with plant-floor optics will lose budget to molecular-design platforms.
AI Chemicals Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
1.320 B
2026
1.840 B
2027
2.560 B
2028
3.560 B
2029
4.950 B
2030
6.880 B
2031
9.570 B
2032
AI Chemicals Market Size (In Billion)
Year
Market Size
2026
1.320 B
2027
1.840 B
2028
2.560 B
2029
3.560 B
2030
4.950 B
2031
6.880 B
2032
9.570 B
What is the AI Chemicals Market?
The AI chemicals market covers software, hardware and services that apply machine learning, generative models and advanced analytics to chemical R&D, production optimization, supply-chain planning and strategy within chemical manufacturers and their suppliers. It spans discovery platforms, process simulation, predictive maintenance and catalyst optimization deployed across basic, specialty and formulated chemicals.
Scope: what this report covers and excludes
This analysis covers AI software platforms, compute hardware and implementation services sold into chemical producers, formulators and contract manufacturers, segmented by component, business application, end user and region. This analysis does not cover adjacent markets such as pure pharmaceutical clinical-trial AI, general-purpose enterprise ERP, or industrial automation hardware sold without an AI software layer.
How big is the market for AI Chemicals Market?
Estimates converge on a 2026 base of roughly 1.3–2.0 Billion and a 2033–2034 terminal value of 11–19 Billion, but the spread reflects genuine definitional disagreement rather than forecast error. The narrowest scope counts only AI software subscriptions; the broadest includes compute hardware and services revenue.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
18.58 Billion (2034)
2026: 1.32 Billion
2026–2034
39.1%
Software, hardware, services across R&D–production
AI in materials science, chemicals as one application
A competing analysis
12.84 Billion (2035)
2026: 1.38 Billion
2026–2035
24.9%
Generative AI platforms for molecule and material design only
One published industry estimate
The most defensible anchor is the 2026 base of 1.32 Billion with a mid-to-high 30s CAGR, because it aligns with disclosed chemical R&D budgets and observable software attach rates. Our analysis suggests the 39.1% figure slightly overstates near-term hardware-inclusive revenue but captures the software inflection correctly; buyers should plan against 30–35% for budgeting.
How is the market segmented?
Segmentation follows four axes: component, business application, end user and deployment, with software and R&D discovery generating the disproportionate share of near-term value. Buyers typically combine a molecular-design platform with a production-optimization layer, which is why vendors bundle aggressively across these axes.
Basic chemicals, advanced materials, active ingredients, green & biochemicals, paints & coatings, adhesives & sealants, water treatment
By Deployment
Cloud, on-premises
Which region leads in AI Chemicals Market?
North America leads the AI chemicals market at an estimated 38% revenue share in 2026, anchored by concentrated pharma and specialty-chemical R&D budgets and the deepest pool of AI talent, while Asia-Pacific is the fastest-growing region on chemical-capacity expansion and national AI policy support.
AI Chemicals Market Regional Market Share
Loading chart...
AI Chemicals Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.05%
Middle East & Africa
0.05%
North America — USA, Canada, Mexico
USA (largest single country; deep R&D and cloud infrastructure)
Canada (specialty chemicals and AI research clusters)
Mexico (manufacturing-adjacent adoption)
Europe — Germany, UK, France, Italy, Spain, Netherlands, Russia
Germany and UK lead on process optimization and regulatory-grade data
Asia-Pacific — China, Japan, India, South Korea, Malaysia, Indonesia, Australia, Vietnam
China and India drive volume; Japan leads on quality-critical applications
Middle East & Africa — Saudi Arabia, UAE, Israel, South Africa
Latin America — Brazil, Argentina, Mexico
This geography implies that Western vendors should localize data-residency and compliance features for EU buyers, while growth-stage entrants should prioritize China and India for volume-led deployments.
What is driving growth — and what is holding it back?
Growth is driven by R&D cost pressure and measurable hit-rate gains, while the binding constraint is integration cost against legacy plant systems — not model capability. The net balance favors acceleration through 2028, after which value shifts from discovery toward production and supply-chain applications.
Factor
Direction
Evidence strength
Mechanism
AI-driven discovery hit-rate gains
Driver
Strong
Reported lift from ~50% to ~80% in materials screening shortens lab cycles
Chemical R&D budget intensity
Driver
Strong
Multi-billion annual R&D spend creates willingness to pay for faster iteration
Sustainability and emissions targets
Driver
Moderate
Process optimization reduces energy use and supports greener formulation
Compute and GPU cost inflation
Restraint
Moderate
Tariffs and critical-mineral controls raise platform total cost of ownership
Legacy system integration
Restraint
Strong
Interoperability with historians, LIMS and ERP extends payback periods
Data quality and fragmentation
Restraint
Strong
Proprietary siloed datasets limit model transferability across sites
Who are the leading vendors?
The vendor field splits into hyperscalers providing compute and model infrastructure, specialist chemistry-AI platforms owning molecular design, and industrial-software incumbents embedding AI into plant operations. Differentiation rests on proprietary chemistry data and validated models, not on generic model access.
Vendor
Primary positioning
Illustrative strength
Microsoft (Azure AI)
Cloud and model infrastructure
Enterprise integration and compliance footprint
AWS
Cloud and HPC for simulation
Compute scale and partner ecosystem
Google (incl. DeepMind)
Discovery models and cloud
Materials-discovery research depth
IBM
Enterprise AI and chemistry workflows
Regulated-industry trust
C3.ai
Industrial AI applications
Production and reliability use cases
Iktos
Generative molecular design
Chemistry-native generative models
Hexagon
Plant and process software
Asset and operations integration
GE Vernova
Industrial analytics
Equipment-adjacent optimization
Our analysis suggests hyperscalers will capture infrastructure margin while specialists capture application margin; buyers should expect consolidation pressure on single-module vendors within 24 months.
What do buyers and operators need to know?
Selection should hinge on validated model performance against your own assay data, not vendor benchmark claims. Demand a proof-of-concept on proprietary compounds with defined hit-rate and cycle-time baselines, and contract for data ownership and model retraining rights.
Procurement risk concentrates in three areas: integration with legacy LIMS and historians, data residency and IP leakage, and regulatory credibility of AI outputs in submissions. Switching costs rise sharply once models are fine-tuned on proprietary data, so negotiate export rights and portability before pilot expansion.
Operators should also budget for change management — chemists and process engineers, not IT, determine realized value. Our analysis implies payback is fastest when AI is scoped to a single high-value discovery or yield problem rather than enterprise-wide transformation.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the aggressive forecast trajectory for AI in chemicals, but only for software-led R&D applications; hardware-inclusive totals likely grow slower than headline CAGRs imply. The strongest counter-argument is that integration cost and data fragmentation will delay enterprise-wide adoption, capping near-term spend — a view supported by persistent pilot-to-production failure rates.
We judge the counter-argument as a timing risk, not a thesis-breaker: discovery-stage ROI is demonstrable today, while plant-floor ROI remains unproven at scale. This divergence implies a two-wave market — molecular design first, operational optimization second — and vendors mispricing the sequence will misallocate capital.
Investors should underwrite specialist chemistry-AI platforms with proprietary datasets over generic analytics vendors, given defensibility and consolidation upside.
Operators should sequence deployment: one discovery use case with hard cycle-time KPIs, then process optimization once data governance is fixed.
Vendors should prioritize data portability and validation evidence to shorten procurement cycles in regulated chemical buyers.
What would change this conclusion: sustained evidence that production-optimization deployments deliver audited payback under two years, or a regulatory ruling that constrains AI-derived submissions would each materially shift our weighting toward the conservative forecast band.
AI Chemicals Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
AI Chemicals Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 39.1% from 2020-2034
Segmentation
By Component
Hardware
Software
Services
By Technology
Machine Learning
Deep Learning
Generative AI
NLP
Computer Vision
Advanced Analytics
By Business Application
R&D
Production
Supply Chain Management
Strategy Management
By End User
Basic Chemicals
Advanced Materials
Active Ingredients
Green & Biochemicals
Paints & Coatings
Adhesives & Sealants
Water Treatment
By Deployment Mode
Cloud
On-Premises
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Russia
Asia Pacific
China
Japan
India
South Korea
Malaysia
Indonesia
Australia
Vietnam
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Services
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Machine Learning
5.2.2. Deep Learning
5.2.3. Generative AI
5.2.4. NLP
5.2.5. Computer Vision
5.2.6. Advanced Analytics
5.3. Market Analysis, Insights and Forecast - by Business Application
5.3.1. R&D
5.3.2. Production
5.3.3. Supply Chain Management
5.3.4. Strategy Management
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Basic Chemicals
5.4.2. Advanced Materials
5.4.3. Active Ingredients
5.4.4. Green & Biochemicals
5.4.5. Paints & Coatings
5.4.6. Adhesives & Sealants
5.4.7. Water Treatment
5.5. Market Analysis, Insights and Forecast - by Deployment Mode
5.5.1. Cloud
5.5.2. On-Premises
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Services
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Machine Learning
6.2.2. Deep Learning
6.2.3. Generative AI
6.2.4. NLP
6.2.5. Computer Vision
6.2.6. Advanced Analytics
6.3. Market Analysis, Insights and Forecast - by Business Application
6.3.1. R&D
6.3.2. Production
6.3.3. Supply Chain Management
6.3.4. Strategy Management
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Basic Chemicals
6.4.2. Advanced Materials
6.4.3. Active Ingredients
6.4.4. Green & Biochemicals
6.4.5. Paints & Coatings
6.4.6. Adhesives & Sealants
6.4.7. Water Treatment
6.5. Market Analysis, Insights and Forecast - by Deployment Mode
6.5.1. Cloud
6.5.2. On-Premises
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Services
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Machine Learning
7.2.2. Deep Learning
7.2.3. Generative AI
7.2.4. NLP
7.2.5. Computer Vision
7.2.6. Advanced Analytics
7.3. Market Analysis, Insights and Forecast - by Business Application
7.3.1. R&D
7.3.2. Production
7.3.3. Supply Chain Management
7.3.4. Strategy Management
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Basic Chemicals
7.4.2. Advanced Materials
7.4.3. Active Ingredients
7.4.4. Green & Biochemicals
7.4.5. Paints & Coatings
7.4.6. Adhesives & Sealants
7.4.7. Water Treatment
7.5. Market Analysis, Insights and Forecast - by Deployment Mode
7.5.1. Cloud
7.5.2. On-Premises
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Services
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Machine Learning
8.2.2. Deep Learning
8.2.3. Generative AI
8.2.4. NLP
8.2.5. Computer Vision
8.2.6. Advanced Analytics
8.3. Market Analysis, Insights and Forecast - by Business Application
8.3.1. R&D
8.3.2. Production
8.3.3. Supply Chain Management
8.3.4. Strategy Management
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Basic Chemicals
8.4.2. Advanced Materials
8.4.3. Active Ingredients
8.4.4. Green & Biochemicals
8.4.5. Paints & Coatings
8.4.6. Adhesives & Sealants
8.4.7. Water Treatment
8.5. Market Analysis, Insights and Forecast - by Deployment Mode
8.5.1. Cloud
8.5.2. On-Premises
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Services
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Machine Learning
9.2.2. Deep Learning
9.2.3. Generative AI
9.2.4. NLP
9.2.5. Computer Vision
9.2.6. Advanced Analytics
9.3. Market Analysis, Insights and Forecast - by Business Application
9.3.1. R&D
9.3.2. Production
9.3.3. Supply Chain Management
9.3.4. Strategy Management
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Basic Chemicals
9.4.2. Advanced Materials
9.4.3. Active Ingredients
9.4.4. Green & Biochemicals
9.4.5. Paints & Coatings
9.4.6. Adhesives & Sealants
9.4.7. Water Treatment
9.5. Market Analysis, Insights and Forecast - by Deployment Mode
9.5.1. Cloud
9.5.2. On-Premises
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Services
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Machine Learning
10.2.2. Deep Learning
10.2.3. Generative AI
10.2.4. NLP
10.2.5. Computer Vision
10.2.6. Advanced Analytics
10.3. Market Analysis, Insights and Forecast - by Business Application
10.3.1. R&D
10.3.2. Production
10.3.3. Supply Chain Management
10.3.4. Strategy Management
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Basic Chemicals
10.4.2. Advanced Materials
10.4.3. Active Ingredients
10.4.4. Green & Biochemicals
10.4.5. Paints & Coatings
10.4.6. Adhesives & Sealants
10.4.7. Water Treatment
10.5. Market Analysis, Insights and Forecast - by Deployment Mode
10.5.1. Cloud
10.5.2. On-Premises
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: AI Chemicals Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America AI Chemicals Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America AI Chemicals Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America AI Chemicals Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America AI Chemicals Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America AI Chemicals Market Revenue (Billion), by Business Application 2026 & 2034
Figure 7: North America AI Chemicals Market Revenue Share (%), by Business Application 2026 & 2034
Figure 8: North America AI Chemicals Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America AI Chemicals Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America AI Chemicals Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 11: North America AI Chemicals Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 12: North America AI Chemicals Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America AI Chemicals Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe AI Chemicals Market Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe AI Chemicals Market Revenue Share (%), by Component 2026 & 2034
Figure 16: Europe AI Chemicals Market Revenue (Billion), by Technology 2026 & 2034
Europe AI Chemicals Market Revenue Share (%), by Technology 2026 & 2034
List of Tables
Table 1: AI Chemicals Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: AI Chemicals Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: AI Chemicals Market Revenue Billion Forecast, by Business Application 2020 & 2034
Table 4: AI Chemicals Market Revenue Billion Forecast, by End User 2020 & 2034
Table 5: AI Chemicals Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 6: AI Chemicals Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America AI Chemicals Market Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America AI Chemicals Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America AI Chemicals Market Revenue Billion Forecast, by Business Application 2020 & 2034
Table 10: North America AI Chemicals Market Revenue Billion Forecast, by End User 2020 & 2034
Table 11: North America AI Chemicals Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 12: North America AI Chemicals Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA AI Chemicals Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada AI Chemicals Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico AI Chemicals Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe AI Chemicals Market Revenue Billion Forecast, by Component 2020 & 2034
Frequently Asked Questions
1. How big is the AI chemicals market in 2026?
The global AI chemicals market is estimated at 1.32 Billion in 2026, with the broadest definitions placing it near 2.0 Billion when compute hardware and services are fully included in the revenue base.
2. What is the AI chemicals market growth rate?
Published forecasts cluster between 25% and 39% CAGR through 2033–2035. Our analysis treats 30–35% as the defensible planning band, reflecting software-led adoption with slower hardware-inclusive revenue.
3. Which region leads AI adoption in chemicals?
North America leads with an estimated 38% revenue share, driven by concentrated pharma and specialty-chemical R&D budgets and hyperscale cloud infrastructure. Asia-Pacific is the fastest-growing region on chemical-capacity expansion.
4. Which application dominates the AI chemicals market?
R&D dominates, particularly molecular discovery and property prediction, because hit-rate and cycle-time improvements are measurable. Production optimization is the largest adjacent application but has longer payback periods.
5. Who are the leading AI chemicals vendors?
Microsoft, AWS, Google, IBM, C3.ai, Iktos, Hexagon and GE Vernova lead across infrastructure, chemistry-native generative platforms and industrial-software integration. No single vendor holds a dominant share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split, prioritizing direct validation with value-chain participants over published benchmarks. In-depth interviews were conducted with raw material and intermediate suppliers, specialty chemical producers, contract formulators and global distributors, capturing both the buy-side and sell-side of AI deployment. Decision-maker designations interviewed include VP-level Sourcing, Heads of R&D and Digital Discovery, Technical Directors and Commercial Operations Leads, ensuring technology, procurement and commercial perspectives are triangulated.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Digital Discovery Heads
40%
Procurement & Sourcing Directors
30%
Technical & Operations Directors
20%
Regulatory & Compliance Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty & Basic Chemical Producers
45%
Contract Formulators & CDMOs
30%
Software & Platform Vendors
25%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade bilateral trade records for chemical intermediates and AI-related goods, WTO trade-monitor volumes, US ITC and Eurostat industrial statistics, corporate 10-K and annual investor filings, patent landscapes, and technical standards from recognized industry associations. Public regulatory dockets on AI model credibility in regulated submissions were reviewed to benchmark adoption readiness.
Demand Modeling & Market Sizing Triangulation
Market sizing triangulates Top-Down allocation from macroeconomic chemical R&D budgets and segment-level software penetration against Bottom-Up modeling of vendor revenue, deployment counts and per-site contract values. Divergences between the two approaches are reconciled against disclosed vendor results and trade-flow evidence.
 AI Chemicals Market