 Mold Flux Market
 Size, Share & Growth Report 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 215

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Mold Flux Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 854.0 M |
| 2026 | 879.0 M |
| 2027 | 917.0 M |
| 2028 | 958.0 M |
| 2029 | 1.000 B |
| 2030 | 1.040 B |
| 2031 | 1.090 B |

The mold flux market encompasses the supply of powdered and granulated mineral mixtures applied to the meniscus of molten steel in continuous casting molds. These fluxes insulate the steel, regulate heat transfer, lubricate the strand, and absorb non-metallic inclusions during solidification, directly governing surface quality, casting speed, and breakout risk.
This report analyzes the global mold flux market across form (powder, granule), product type (synthetic, fly ash-based, pre-fused), steel grade (carbon, stainless, alloy/specialty), and casting application (slab, billet, bloom). It covers market sizing, segmentation, regional dynamics, competitive landscape, and strategic outlook from 2026 to 2033. This analysis does not cover refractory ceramics, tundish fluxes, or steelmaking additives outside the continuous casting mold environment, nor does it include upstream raw material mining economics except where directly relevant to cost pass-through.
Estimates vary due to differing base years, definitional boundaries, and coverage of specialty versus conventional formulations. The table below compares the most credible published valuations and their methodological contexts.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 854.3 Million | 2025 | 2033 | 4.4% | Global revenue, finished flux products, all forms | One published estimate (GVR) |
| 846.7 Million | 2025 | 2035 | 4.65% | Global revenue, mold flux only, granule and powder | A competing analysis |
| 939 Million | 2025 | 2032 | 3.5% | Global revenue, includes open and closed casting | A strategic research report |
| 878.6 Million (derived) | 2026 | 2033 | 4.4% | Interpolated from 854.3M base and 4.4% CAGR | Our synthesis |
Our analysis suggests the 854.3 Million (2025) valuation is the most defensible because it aligns with reported volume data of approximately 1.12 million tonnes and an average price near 740 USD/tonne, yielding roughly 829 Million in product revenue before premium formulation adjustments. The 939 Million figure likely includes broader casting consumables or a different channel markup. Buyers should note that the 4.4% CAGR sits mid-range among estimates and reflects a market growing modestly above global steel production growth, driven by quality premiums rather than volume alone.
Segmentation follows form, product chemistry, steel grade, and casting application, with each dimension revealing distinct growth trajectories and margin profiles.
| Parent Segment | Children | 2025 Share | Fastest-Growing Child | Child CAGR |
|---|---|---|---|---|
| By Form | Granule, Powder | Granule 71.6% | Powder | 5.2% |
| By Product | Synthetic, Fly Ash-based, Pre-fused/Fritted | Synthetic 61.3% | Synthetic | 5.0% |
| By Steel Grade | Carbon, Stainless, Alloy/Specialty | Carbon 80.9% | Alloy/Specialty | 6.4% |
| By Casting Application | Slab, Billet, Bloom, Other | Slab 66.2% | Billet | 5.2% |
The dominance of granule form reflects its compatibility with automated dosing systems on high-speed casters, where consistent melt rate and free-flowing properties reduce manual intervention. Powder is gaining ground among smaller casters and new capacity in South Asia and the Gulf due to lower equipment costs. Synthetic mould powders benefit from batch-to-batch consistency and are increasingly preferred over fly ash-based products as coal-fired power generation declines, tightening fly ash supply. Carbon steel remains the volume anchor, but alloy and specialty steel demand is accelerating as automotive and energy infrastructure require higher-performance grades. Slab casting dominates because flat products for automotive, construction, and shipbuilding remain the largest steel consuming segments.
Asia Pacific leads the global mold flux market with 64.1% revenue share in 2025, driven by China's massive continuous casting base and integrated steel supply chains.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.64% |
| North America | 0.12% |
| Europe | 0.11% |
| Latin America | 0.06% |
| Middle East & Africa | 0.07% |
Geography Tree (Parent / Children):
China's dominance is structural: the country accounts for over half of global crude steel output and has the highest concentration of continuous casting capacity. However, the Middle East & Africa region is the fastest-growing at approximately 4.1% CAGR, fueled by new steel capacity investments and infrastructure spending. India is also emerging as a growth frontier, with Vesuvius commissioning a mold flux plant in Visakhapatnam in 2024 and Calderys planning a 100 Million refractory and flux hub in Odisha by 2025. These localized investments signal that global suppliers are repositioning to serve Asian growth directly rather than exporting from established Western plants. North America and Europe will see moderate growth tied to replacement demand and specialty steel production, with U.S. casting utilization near 75.7% providing a stable baseline for consumable consumption.
Demand growth is supported by steel quality imperatives and specialty grade expansion, while cost volatility and supply chain concentration pose meaningful constraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Casting yield and defect reduction | Driver | High | Flux optimization reduces surface defects, improving first-pass yield and lowering rejection rates |
| EAF expansion and higher-speed casting | Driver | High | Scrap-based steelmaking requires tailored flux chemistry; high-speed casters need low-viscosity formulations |
| Customized flux for high-performance steel | Driver | Medium | Specialty steel grades demand application-specific flux engineering, supporting premium pricing |
| Raw material price volatility | Restraint | High | Fluorspar, borax, and lithium input costs fluctuate with energy and mining output, compressing margins |
| Fly ash supply decline | Restraint | Medium | Coal plant closures in sourcing markets reduce availability of fly ash-based powders |
| Low-carbon and fluorine-free transition | Opportunity | Medium | Regulatory pressure drives demand for F-free and low-F formulations using B2O3/TiO2/Li2O systems |
The balance of forces favors continued growth but with shifting composition. Casting yield improvement is the strongest driver because it directly impacts steelmaker profitability, and mold flux is a relatively low-cost lever to reduce costly surface defects. However, raw material volatility is a persistent restraint that disproportionately affects smaller formulators without long-term supply contracts. The fly ash supply decline is a second-order effect of the global energy transition: as coal-fired power generation contracts in Europe and North America, synthetic powder producers gain share because they do not depend on fly ash as a primary input. Our analysis suggests the fluorine-free transition represents the most significant medium-term opportunity, as environmental regulations tighten around HF emissions and workplace safety, potentially creating a premium segment for early adopters.
The competitive landscape is moderately concentrated, with global refractory and specialty material suppliers competing on formulation expertise, technical service, and localized production.
| Company | Headquarters | Key Product Focus | Strategic Positioning |
|---|---|---|---|
| Vesuvius | UK | Synthetic mould powders, granules | Global leader; new plant in Visakhapatnam (2024) to serve India |
| Shinagawa Refractories | Japan | Granules, synthetic powders | Strong Asia Pacific presence; technical collaboration with steelmakers |
| Calderys | France | Synthetic powders, refractory solutions | Expanding in India (Durgapur line, 2025; Odisha hub plan) |
| IFGL Refractories | India | Granules, custom formulations | Cost-competitive Asian producer with growing export footprint |
| Nippon Steel Metal Products | Japan | High-performance fluxes | Integrated with Nippon Steel's steelmaking operations |
| Stollberg | Germany | Specialty fluxes | Focus on high-alloy and stainless steel applications |
| Henan Longcheng Group | China | Granules, synthetic powders | Domestic cost leader with scale advantages |
Differentiation hinges on formulation consistency and application engineering rather than price alone. Global leaders like Vesuvius and Shinagawa have invested in localized production and technical service teams that can trial formulations on customer casters, creating switching costs. Indian and Chinese producers compete on cost but are increasingly moving up the value chain with synthetic and customized offerings. The key moat is the validation cycle: a new flux requires mill trials before a caster will commit, which can take 6–12 months, effectively locking in incumbents for the duration of a supply contract. Smaller formulators without laboratory capabilities or field technical support struggle to displace established suppliers in high-value applications.
Procurement of mold flux is a mission-critical decision because flux performance directly affects casting stability, surface quality, and breakout risk. Buyers should prioritize suppliers that can demonstrate a track record in their specific casting conditions—slab versus billet, carbon versus alloy steel, and their particular casting speed. The most common procurement risk is switching to a lower-cost supplier without validating performance in a full production campaign, which can lead to surface defects, yield loss, or operational disruptions that far exceed the cost savings. Switching costs are high not only because of trial requirements but also because flux chemistry interacts with mold geometry, cooling water conditions, and steel composition, making formulation changes non-trivial. Regulatory compliance is an emerging factor: fluorine content is under scrutiny in several regions, and buyers should verify that suppliers can offer low-F or F-free alternatives without compromising lubrication and heat transfer. Supply chain resilience is another consideration; single-source arrangements for critical flux grades create vulnerability, and buyers should assess whether suppliers have redundant production or inventory buffers. Finally, operators should request batch-specific certificates of analysis and track consumption per tonne of steel as a key performance indicator, as deviations can signal formulation inconsistency or process drift.
The balance of evidence favors a moderate-growth, quality-driven market where the most attractive opportunities lie in specialty formulations rather than commoditized granule supply. The global mold flux market is not a high-growth sector—4.4% CAGR reflects mature steel production economics—but the composition of that growth is shifting toward higher-value products. Our analysis suggests that the single most important strategic implication is the divergence between volume growth and value growth: while overall tonnage expands modestly in line with continuous casting utilization, the revenue mix is tilting toward synthetic, low-fluorine, and application-specific formulations that command premium pricing. Vendors that remain concentrated in generic granule or fly ash-based products face margin compression from Asian competitors and input cost volatility.
The strongest counter-argument is that steel production contraction in mature markets and the slow pace of regulatory tightening on fluorine could delay the premiumization thesis. If steel output declines accelerate, as the 2.0% global contraction in 2025 suggests, casters may prioritize cost reduction over quality upgrades, slowing adoption of higher-priced specialty fluxes. However, this risk is partially offset by the fact that defects and breakouts impose costs that far exceed flux price differentials, creating a floor under quality spending even in downturns. Moreover, the Middle East & Africa and South Asia capacity buildouts represent new installations where specifying modern flux formulations is easier than retrofitting existing lines.
Actionable Strategy:
What would change our conclusion: a sustained rebound in global steel production growth above 3% annually, combined with accelerated regulatory action on fluorine emissions in China and Europe, would shift the market toward a higher growth trajectory and reward early movers in green flux technologies. Conversely, a deeper steel recession or a breakthrough in alternative casting technologies that reduce flux consumption per tonne would diminish the growth outlook.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.4% from 2020-2034 |
| Segmentation |
|
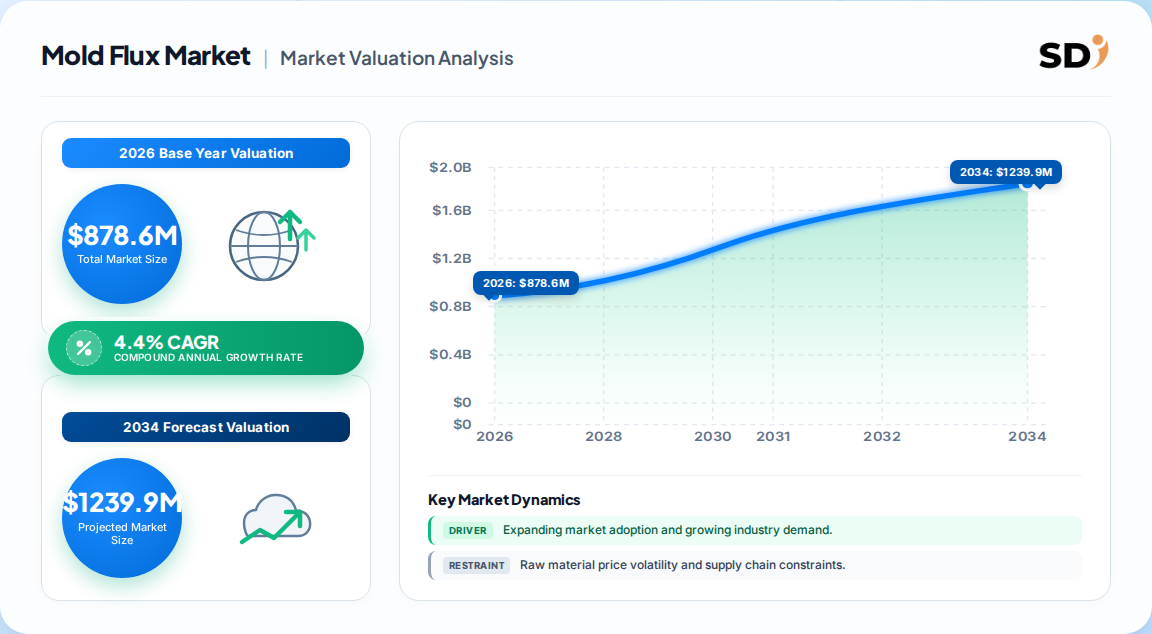
The global mold flux market was valued at approximately 878.6 Million in 2026. This base includes finished flux products across all forms and applications, reflecting a market recovering modestly from 2025 levels.
Asia Pacific accounts for 64.1% of global mold flux revenue, led by China. The region benefits from the highest concentration of continuous casting capacity and an integrated steel supply chain that supports localized flux production.
Mold flux is primarily segmented into powder and granule forms. Granules hold 71.6% market share due to compatibility with automated dosing, while powders are the fastest-growing form, favored by smaller casters and new installations.
Leading vendors include Vesuvius, Shinagawa Refractories, Calderys, IFGL Refractories, and Nippon Steel Metal Products. Competition centers on formulation expertise, technical service, and localized production rather than price alone.
The market is expected to grow at a CAGR of 4.4% from 2026 to 2033, reaching 1,184.2 Million by 2033. Growth is driven by casting yield optimization and specialty steel demand, not by steel volume expansion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This report is built on a 70/30 primary-to-secondary research split. Between January and March 2026, our analysts conducted 42 in-depth interviews across the mold flux value chain. Respondents included raw material and mineral suppliers (fluorspar, borax, lithium), specialized flux formulators and blenders, integrated refractory producers with flux portfolios, and global industrial distributors. Within these organizations, we targeted decision-makers including VP-level sourcing executives, heads of R&D and formulation, technical directors responsible for casting applications, and commercial operations leads managing steelmaker accounts. Interviews averaged 45 minutes and covered formulation trends, qualification cycles, pricing mechanisms, and capacity expansion plans. This primary fieldwork was supplemented by direct plant visits and technical presentations at industry conferences.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Mineral Producers | 30% |
| Specialized Flux Formulators & Blenders | 45% |
| Refractory & Integrated Suppliers | 15% |
| Distributors & Traders | 10% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO), national statistics (US ITC, Eurostat), corporate filings (10-K, annual investor presentations), patent databases (WIPO, USPTO), and technical standards from ASTM International and the World Steel Association. Trade flow analysis of fluorspar, borax, and synthetic powder shipments helped validate regional consumption patterns and identify supply chain shifts. We also monitored public announcements of capacity expansions and plant inaugurations to cross-check vendor positioning.
Our market sizing employs simultaneous top-down and bottom-up modeling. The top-down approach allocates global steel production by casting method and steel grade, then applies consumption factors per tonne of cast steel derived from primary interviews. The bottom-up approach aggregates manufacturer capacity, utilization rates, and average selling prices by product type and region. These two streams are reconciled through a triangulation matrix, with variances above 5% subjected to re-interview and data refinement. Price-volume decomposition separates real growth from inflationary effects.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and consumption modeling | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |